
Cheap Car Insurance in PA With No Down Payment
If you are shopping for cheap car insurance in PA with no down payment, you probably want two things at once: a low price and a small amount due today. Pennsylvania is one of the better states to look. Its full-coverage averages sit below the national figures, and the state gives you two choices, limited tort and unstacked uninsured motorist coverage, that can shrink your premium and, with it, your first payment.
This guide covers what Pennsylvania law says about down payments, what drivers pay in 2026, five vehicles that are cheap to insure, and how to start coverage for less.
KEY TAKEAWAYS
- No Pennsylvania law we found sets a minimum or maximum down payment. Each insurer's payment plan decides the amount due today, so the first payment varies widely.
- Full coverage averages $123 a month for a 40-year-old driver in an August 2026 study, and Travelers was cheapest at $68.
- There is no grace period. The Pennsylvania Insurance Department (PID) says insurers do not have to give one, so a missed installment can end your policy.
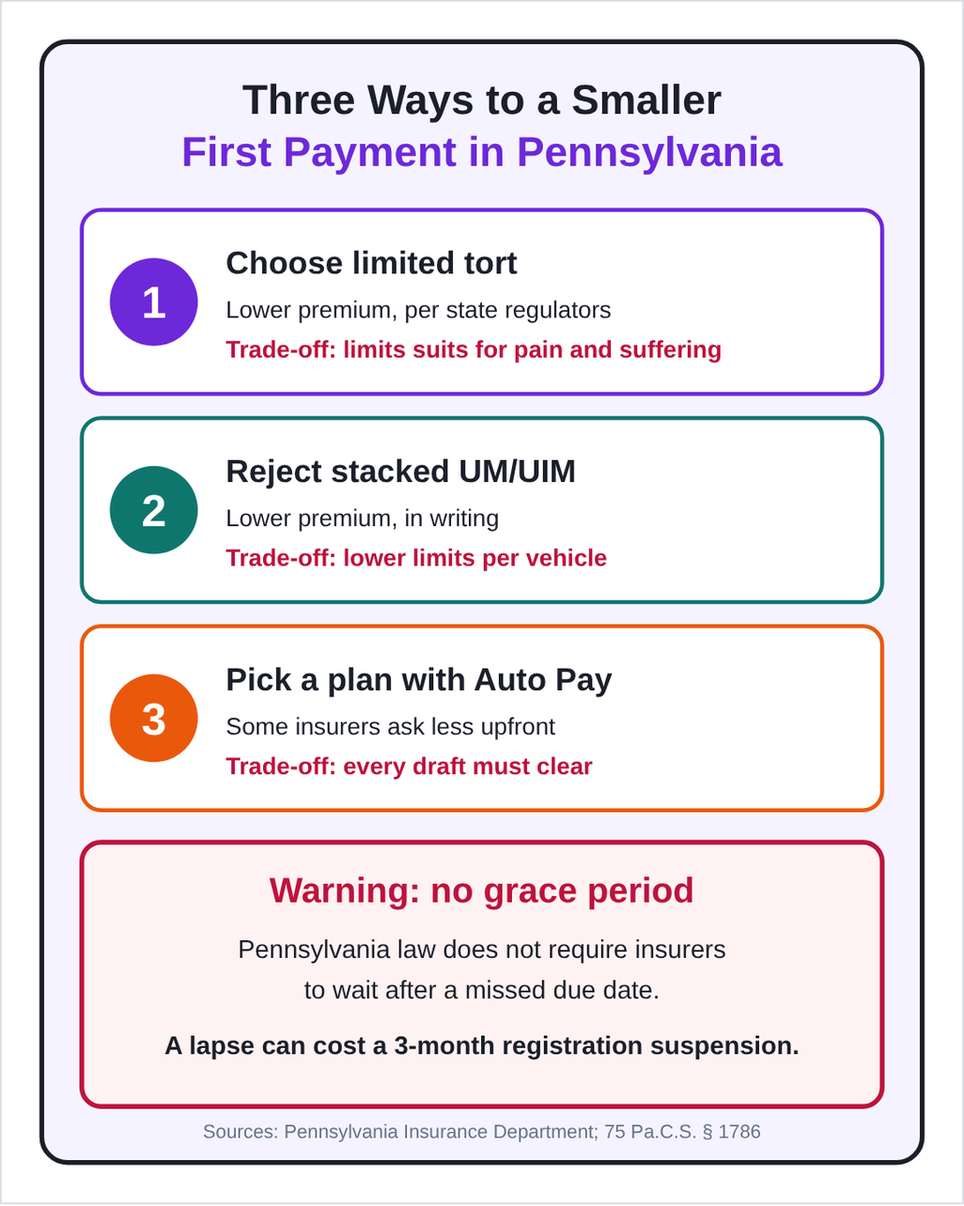
Three choices that can lower a Pennsylvania premium, and therefore the first payment, with the trade-off of each. The grace-period warning comes from the Pennsylvania Insurance Department's auto insurance guide; the suspension rule comes from 75 Pa.C.S. § 1786.
What "no down payment" means for Pennsylvania drivers
A car insurance down payment is the first installment of your premium. The premium is what the whole policy costs for its term, usually six or twelve months. You pay part of it before coverage begins and the rest on a schedule.
"No down payment" is an advertising phrase rather than a type of policy. In practice, it usually means the first payment is no larger than the monthly payments after it. Insurers also call it a "deposit," "initial payment," or "amount due today." Whatever the label, it is money you pay before the policy is in force.
Three figures to compare on every Pennsylvania quote
| Figure | What it means | What to watch for |
|---|---|---|
| Amount due today | What you pay before the policy becomes effective | The share of the premium the plan asks for upfront |
| Each installment | Every later payment, plus any fee | A fee on each payment adds up over the term |
| Total for the term | All payments added together | The number that shows the real price |
Pennsylvania car insurance requirements
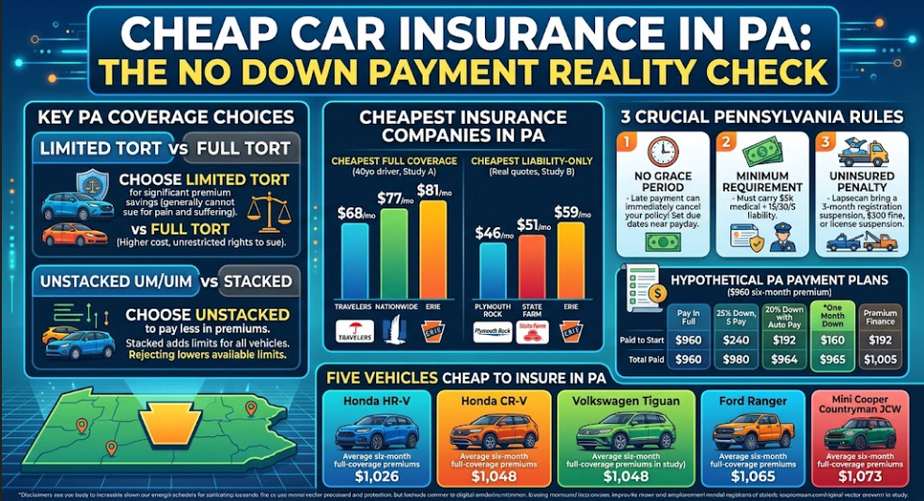
Every registered vehicle in Pennsylvania needs at least $5,000 of medical benefits, $15,000/$30,000 of bodily injury liability, and $5,000 of property damage liability, according to PID. Medical benefits pay your own medical bills after a crash, whoever caused it. Liability pays for injuries and damage you cause to others.
Penalties for a lapse or driving uninsured
Under 75 Pa.C.S. § 1786, PennDOT suspends a vehicle's registration for three months if required coverage lapses. If the vehicle was driven while uninsured, the owner's driving privilege is also suspended for three months, and driving without coverage is a summary offense with a $300 fine.
There are two narrow outs. The suspension does not apply if you prove the lapse lasted less than 31 days and the vehicle was not driven. You can also pay a $500 civil penalty, plus the restoration fee and proof of insurance, instead of serving the registration suspension, but only once in any 12-month period. If you cancel your policy, PennDOT says to return the plate and registration card within 30 days to avoid a suspension.
Can you get cheap car insurance in PA with no down payment?
You can usually start with a modest first payment, but a true $0 start is uncommon. We found no Pennsylvania statute or regulation that sets a minimum or maximum down payment for private passenger auto insurance. That is different from Florida, which requires one month's premium on most new policies, and from Texas, where a 1997 state rule capped the down payment at about two months.
In Pennsylvania, the amount depends on each company's payment plans. PID's consumer guide says many companies have plans that let you pay over time, "sometimes for an extra fee." It also warns that if you finance your premium through a premium finance company, "the monthly payments may be easier, but the total of payments could be larger."
What a typical payment plan looks like
Insurers publish their own plans. GEICO, for example, lists plans for new policies that start at 25% of the premium on a five-payment plan, or 20% with automatic payments. It says installment fees may apply and that some plans are not available in every state, so ask for the Pennsylvania terms before you buy.
The rule that matters most: no grace period
PID’s guide is blunt: “Pennsylvania law does not require companies to extend a grace period for premium payments.” If the insurer does not receive your payment by the due date, it can cancel the policy. A small first payment only helps if you can make every payment after it on time.
If no company will insure you
Drivers who cannot buy coverage in the regular market can apply to the Pennsylvania Assigned Risk Plan, which every insurer writing auto coverage in the state must take part in. You apply through a producer certified by the plan, and you must certify that you tried and failed to get coverage within the previous 60 days. Assigned risk is usually a last resort, not a budget option.
How Pennsylvania compares on first-payment rules
| State | State rule on the first payment | Source |
|---|---|---|
| Pennsylvania | No state minimum or maximum found; set by each insurer's plan | PID auto insurance guide; our review |
| Florida | At least one month's premium before most new policies start, with exceptions | Fla. Stat. § 627.7295(7) |
| Texas | Down payment capped at about two months of premium under a 1997 rule | TDI Bulletin B-0039-97 |
The cheapest car insurance companies in Pennsylvania
Travelers had the lowest full-coverage rate in an August 2026 study of a 40-year-old Pennsylvania driver, at $68 a month. Nationwide followed at $77, and Erie at $81. For minimum coverage, Westfield was cheapest at $20 a month, ahead of Erie at $29 and Travelers at $30.
A second analysis, based on real quotes current to September 30, 2026, found different leaders. State Farm had the lowest full-coverage average at $83 a month, and Plymouth Rock had the lowest liability-only average at $46. The studies use different drivers and limits, so compare each study's numbers only with each other.
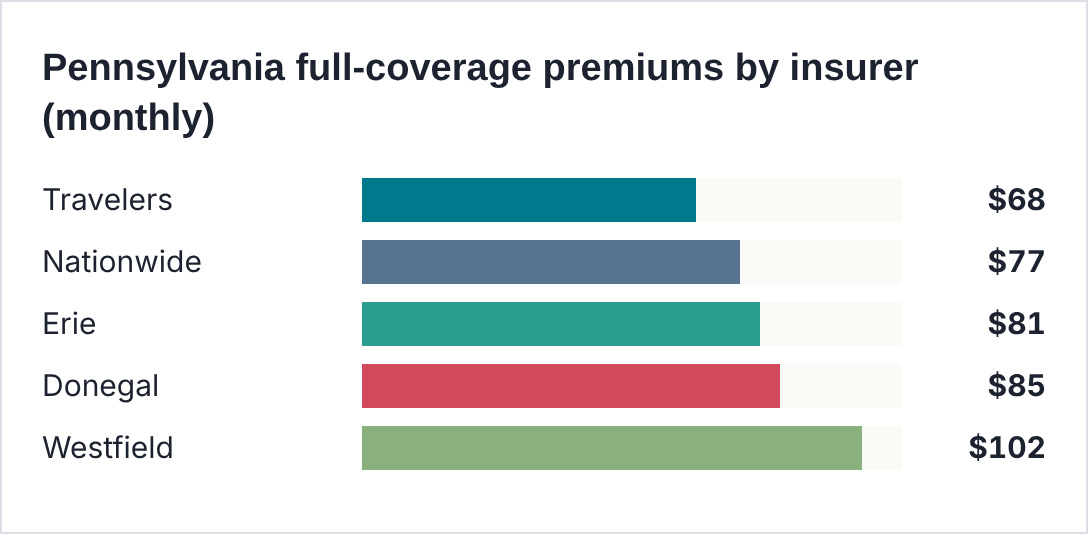
Study A: rate study updated August 25, 2026. Driver: 40-year-old man, clean record, good credit. Full coverage: 100/300/100 liability with a $1,000 deductible. Statewide Pennsylvania averages.
Pennsylvania insurers in two 2026 rate studies
| Insurer | Minimum, study A (monthly) | Full coverage, study A (monthly) | Liability-only, study B (monthly) | Full coverage, study B (monthly) |
|---|---|---|---|---|
| Travelers | $30 | $68 | Not publicly confirmed | Not publicly confirmed |
| Nationwide | $33 | $77 | Not publicly confirmed | Not publicly confirmed |
| Erie | $29 | $81 | $59 | $96 |
| Westfield | $20 | $102 | Not publicly confirmed | Not publicly confirmed |
| State Farm | Not publicly confirmed | Not publicly confirmed | $51 | $83 |
| Plymouth Rock | Not publicly confirmed | Not publicly confirmed | $46 | $111 |
| Auto-Owners | Not publicly confirmed | Not publicly confirmed | $63 | $103 |
Study A: rate study updated August 25, 2026 (profile above); minimum coverage uses Pennsylvania's 15/30/5 limits plus $5,000 of medical benefits, with full tort. Study B: real quotes current to September 30, 2026, drivers ages 20 to 70 with clean records and credit scores of 600 or higher, and $1,000 deductibles on full coverage. "Not publicly confirmed" means the study did not publish that figure.
How much does car insurance cost in Pennsylvania?
Pennsylvania full coverage averages $123 a month in study A. In study B, the state averages $90 a month for liability-only coverage and $162 for full coverage, compared with $99 and $187 nationally. That puts Pennsylvania $9 and $25 a month below the national figures (our calculation).
Your own price depends on your ZIP code, age, driving record, vehicle, coverage choices, and credit-based insurance score. The chart shows the cheapest full-coverage rate study A found for three different driver profiles.
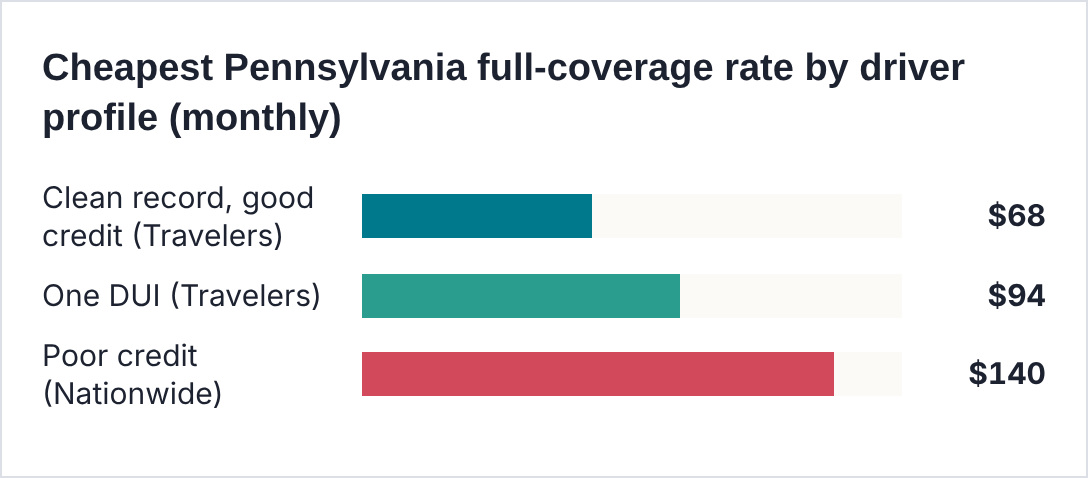
Study A, updated August 25, 2026. Cheapest company rate for each profile, 40-year-old driver, 100/300/100 limits, $1,000 deductible. Each profile changes one factor from the clean-record, good-credit driver.
Teen drivers pay far more. In study A, the cheapest full-coverage rate for a 16-year-old on a family policy was Erie at $315 a month. At 18, Travelers was cheapest at $211, and at 25, Travelers was $132. Since your first payment is a share of your premium, every one of these differences shows up on day one.
Minimum coverage vs. full coverage in Pennsylvania
| Minimum required coverage | Full coverage | |
|---|---|---|
| What it pays for | Medical bills for you up to $5,000, plus injuries and property damage you cause to others | Minimum coverage plus higher limits and damage to your own car |
| Required by Pennsylvania law? | Yes: $5,000 medical benefits and 15/30/5 liability | No, but lenders and leasing companies usually require collision and comprehensive |
| Average monthly cost, study A (40-year-old) | Not publicly confirmed | $123 (100/300/100 limits) |
| Average monthly cost, study B (real quotes) | $90 (liability-only) | $162 |
| What it leaves out | Repairs to your own car; injuries above low limits | Little for most drivers, depending on limits |
Figures are averages, not quotes. Study B's liability-only policies include limits between the state minimum and $50,000/$100,000.
Prices are steady. On April 22, 2026, PID said approved private passenger auto rate filings averaged a 0.2% decrease in 2025 and a 0.5% decrease so far in 2026, after significant increases from 2022 to 2024. The department said more than 200 insurers compete in the state's personal auto market.
Pennsylvania choices that lower your premium and first payment
Pennsylvania gives you two coverage decisions most states do not, and both affect your price. Each saves money by giving up something, so understand the trade before you take it.
Limited tort vs. full tort
When you buy a policy, you choose a tort option. PID says limited tort "offers you significant savings on your premium," but you generally cannot recover damages for pain and suffering unless an exception in the law applies, such as a serious injury. Full tort keeps unrestricted rights to sue. If you do not choose limited tort, you are treated as having chosen full tort.
Stacked vs. unstacked uninsured motorist coverage
"Stacking" lets you add together the uninsured and underinsured motorist limits for each vehicle on your policy. PID says stacked coverage applies by law unless you reject it, and "you will pay less in premiums if you reject stacked coverage." Rejecting it lowers your available limits if a driver with little or no insurance injures you. About 11.0% of Pennsylvania drivers were uninsured in 2023, according to the Insurance Research Council.
Pennsylvania coverage choices that change your price
| Choice | Effect on premium | What you give up | Our take |
|---|---|---|---|
| Limited tort | Lower, per PID | Most claims for pain and suffering unless an exception applies | Worth pricing; know the limits first |
| Reject stacked UM/UIM | Lower, per PID | Combined limits across your vehicles | Matters most with several cars |
| Higher deductible | Lower | More out of pocket after a claim | Only if you have savings |
| Drop collision on an older car | Lower | Repairs to your own car | Consider when the car's value is low |
Five vehicles that cost less to insure in Pennsylvania
The vehicle you insure moves your premium, and a smaller premium means a smaller first payment. A vehicle-model rate study compared average six-month full-coverage premiums across Pennsylvania. It used sample 18- and 40-year-old drivers, 100/300/100 limits, and $500 deductibles. The study's page shows no update date; we accessed it in October 2026.
Unlike the lists for many other states, Pennsylvania's top five includes a pickup truck. Two models tied for fifth place; we show the Mini Cooper Countryman JCW and note the Subaru Outback below.
1. Honda HR-V
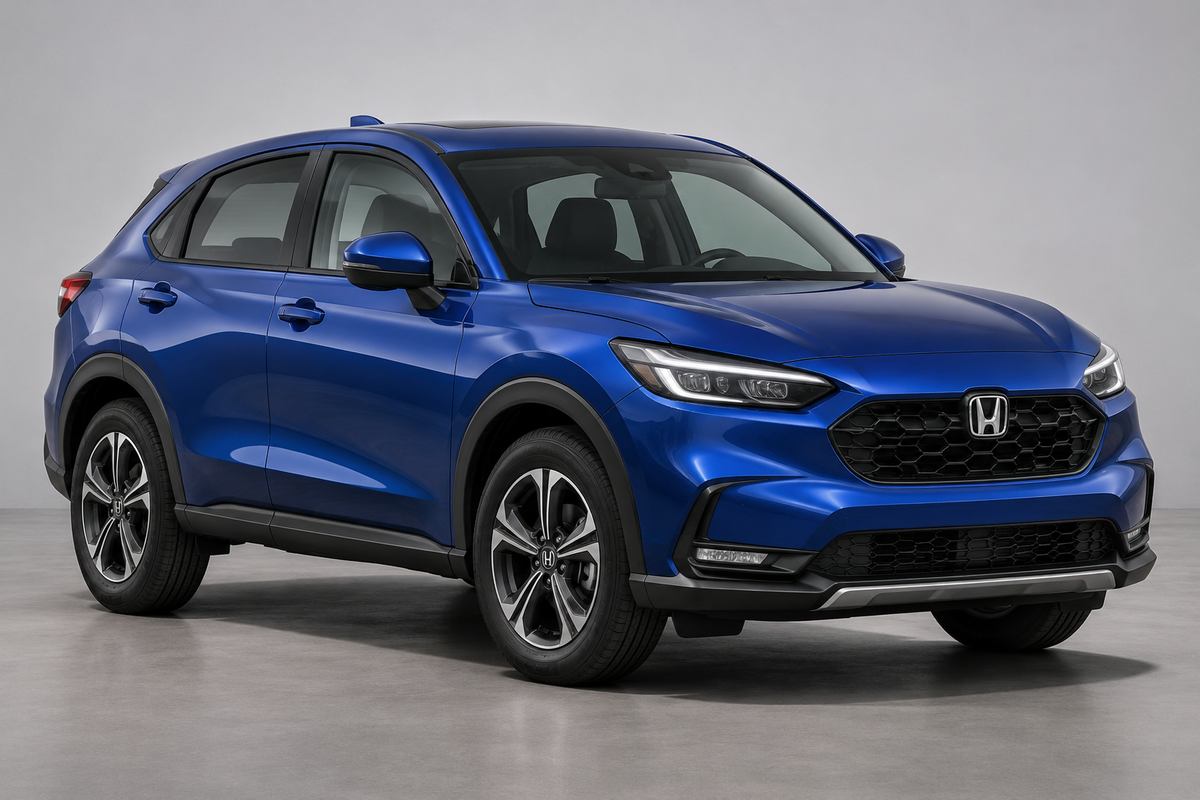
Original vector illustration of the Honda HR-V, a subcompact SUV. Illustration only; not to scale.
Average premium: $1,026 for six months of full coverage in Pennsylvania. The Honda HR-V is a subcompact SUV. It had the lowest average premium of any model in the Pennsylvania study.
2. Honda CR-V
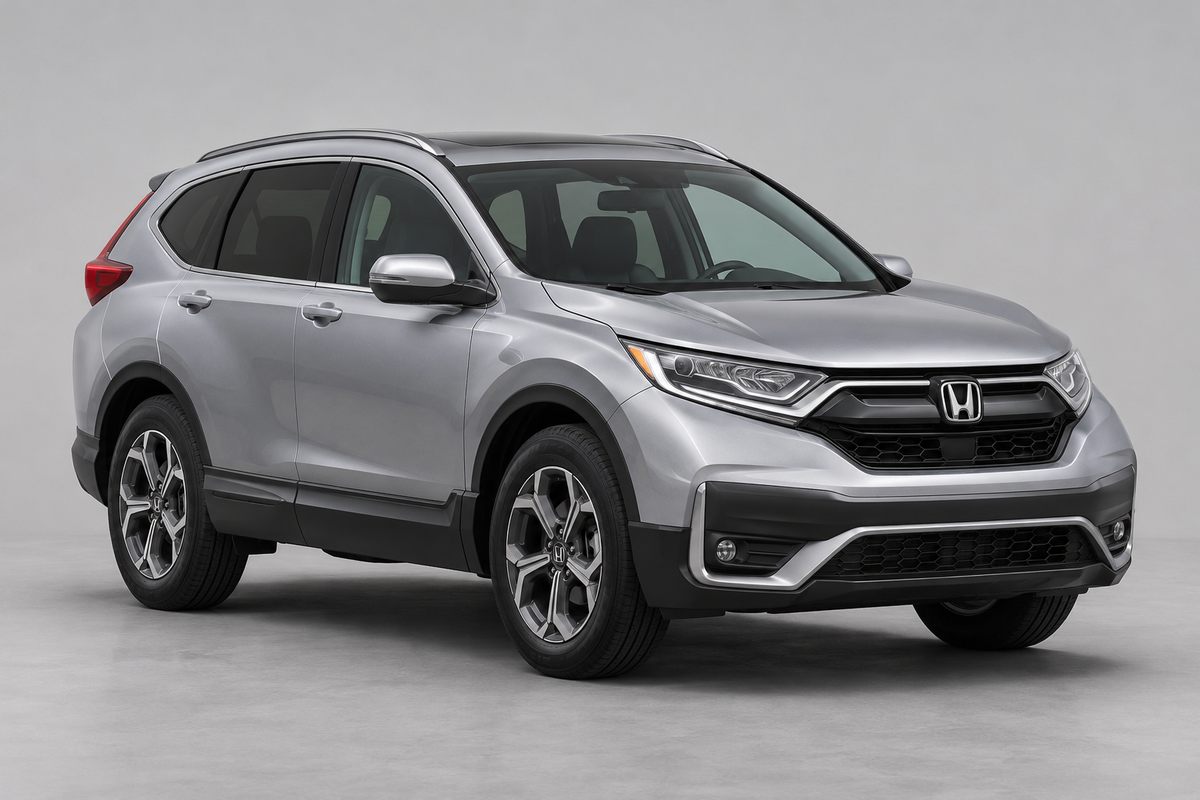
Original vector illustration of the Honda CR-V, a compact SUV. Illustration only; not to scale.
Average premium: $1,048 for six months of full coverage in Pennsylvania. The Honda CR-V is a compact SUV. It tied for second, $22 above the HR-V over six months.
3. Volkswagen Tiguan
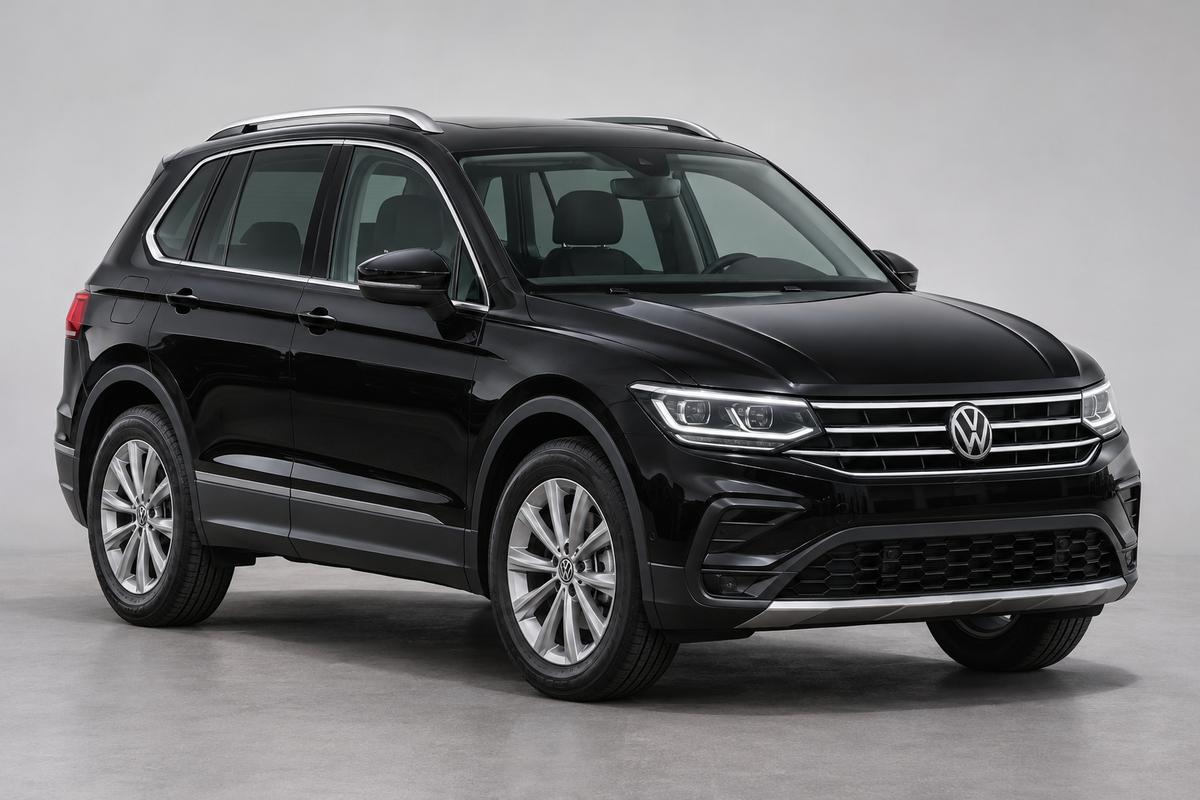
Original vector illustration of the Volkswagen Tiguan, a compact SUV. Illustration only; not to scale.
Average premium: $1,048 for six months of full coverage in Pennsylvania. The Volkswagen Tiguan is a compact SUV. It tied the CR-V for second place at the same average premium.
4. Ford Ranger
Original vector illustration of the Ford Ranger, a midsize pickup truck. Illustration only; not to scale.
Average premium: $1,065 for six months of full coverage in Pennsylvania. The Ford Ranger is a midsize pickup truck. It is the only pickup in the top five, $39 above the HR-V over six months.
5. Mini Cooper Countryman JCW
Original vector illustration of the Mini Cooper Countryman JCW, a small performance crossover. Illustration only; not to scale.
Average premium: $1,073 for six months of full coverage in Pennsylvania. The Mini Cooper Countryman JCW is a small performance crossover. It tied with the Subaru Outback for fifth place, $47 above the HR-V.
Five vehicles with the lowest average insurance premiums in Pennsylvania
| Rank | Make and model | Model year | Average six-month premium | Insurance-cost finding | Source |
|---|---|---|---|---|---|
| 1 | Honda HR-V | Not specified by source | $1,026 | Lowest in the Pennsylvania study | Vehicle-model rate study, accessed Oct. 2026 |
| 2 (tie) | Honda CR-V | Not specified by source | $1,048 | Tied with the Tiguan | Vehicle-model rate study, accessed Oct. 2026 |
| 2 (tie) | Volkswagen Tiguan | Not specified by source | $1,048 | Tied with the CR-V | Vehicle-model rate study, accessed Oct. 2026 |
| 4 | Ford Ranger | Not specified by source | $1,065 | Only pickup in the top five | Vehicle-model rate study, accessed Oct. 2026 |
| 5 (tie) | Mini Cooper Countryman JCW | Not specified by source | $1,073 | Tied with the Subaru Outback | Vehicle-model rate study, accessed Oct. 2026 |
Statewide Pennsylvania averages for sample 18- and 40-year-old drivers, full coverage at 100/300/100 with $500 deductibles. The study does not publish model years. For an 18-year-old, the HR-V averaged $2,898 for six months.
To connect the car to your first payment: one month of a six-month premium is one-sixth of it. On these averages, that is about $171 for the HR-V and $179 for the Countryman (our calculation). These are illustrations, not quotes.
How to start Pennsylvania coverage with a small first payment
Aim for the smallest first payment on a policy whose total you can also afford. Follow these steps in order.
- 1. Get at least three quotes. In study A, full coverage ranged from $68 to $102 a month among the five insurers listed.
- 2. Use identical coverage on every quote. Match liability limits, medical benefits, tort option, stacking choice, deductibles, drivers, and term.
- 3. Price limited tort and unstacked coverage on each quote, and decide whether the savings are worth the trade-offs.
- 4. Ask for the amount due today, with and without automatic payments.
- 5. Compare fees and due dates. Because there is no required grace period, choose due dates that fall right after payday.
- 6. Confirm the effective date and amount in writing, and keep your old policy active until the new one starts.
First payment vs. total cost: a hypothetical comparison
The chart uses a hypothetical $960 six-month premium, or $160 a month. It compares paying in full, GEICO's published 25% and 20% plans, a one-month start with automatic payments, and financing through a premium finance company. Installment fees of $5, or $1 with automatic payments, and a $45 finance charge are our assumptions, not real charges.
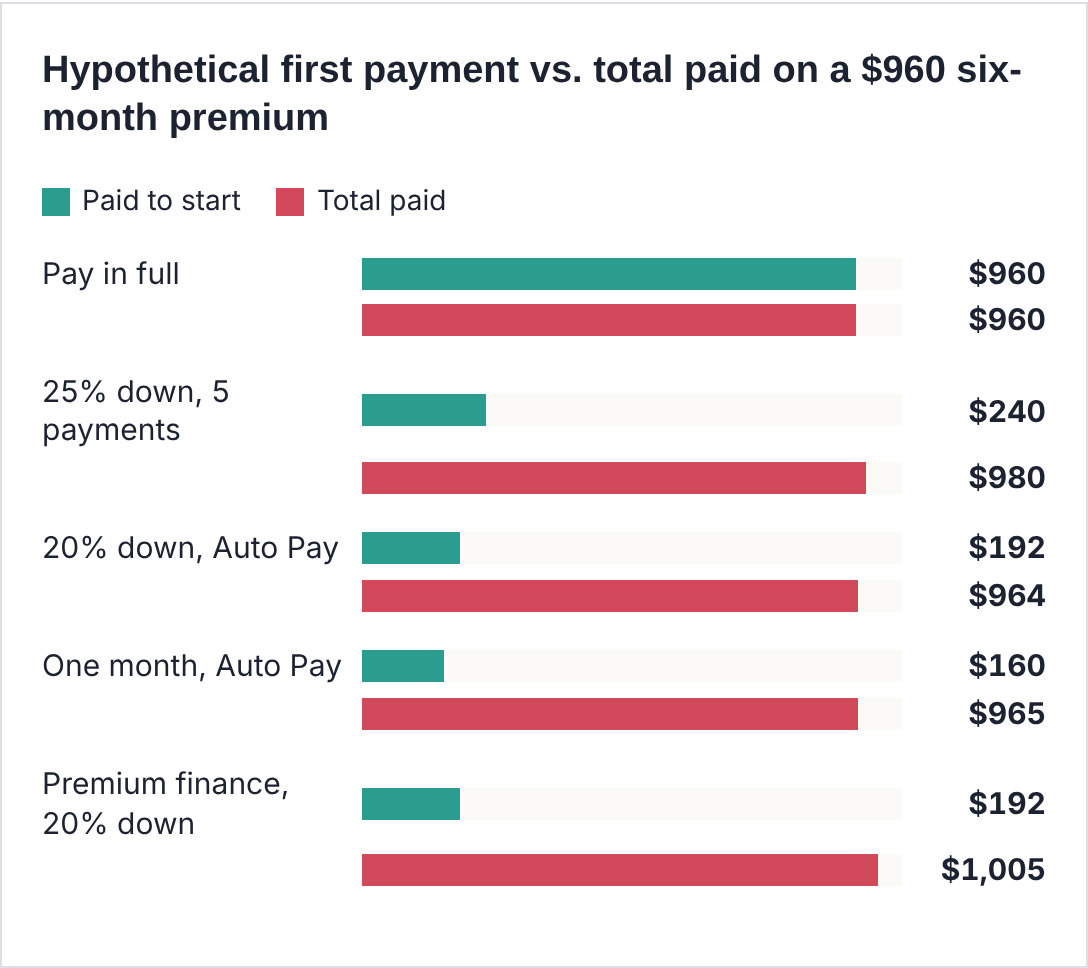
Hypothetical example calculated by us. The 25% and 20% levels are GEICO's published plans for new policies; the finance charge and fees are assumptions, not quotes.
Hypothetical payment plans on a $960 six-month premium
| Plan | Paid to start | Later payments | Assumed fees or charges | Total paid |
|---|---|---|---|---|
| Pay in full | $960 | None | $0 | $960 |
| 25% down, 5 payments | $240 | 4 × $180 | $20 (4 × $5) | $980 |
| 20% down with Auto Pay | $192 | 4 × $192 | $4 (4 × $1) | $964 |
| One month down with Auto Pay | $160 | 5 × $160 | $5 (5 × $1) | $965 |
| Premium finance, 20% down | $192 | Balance plus charge, monthly | $45 finance charge | $1,005 |
All figures are hypothetical and calculated by us. They are not insurer quotes. A one-month Auto Pay start is shown for comparison; not every insurer offers it on new policies.
Discounts and other ways to cut the cost
Every dollar you take off the premium also comes off the first payment. One Pennsylvania discount is required by law: PID says insurers must give drivers 55 and older at least a 5% discount per vehicle after completing an approved driver improvement course.
Ways to lower your Pennsylvania premium or first payment
| Discount or strategy | Who may qualify | What to verify | Limitation |
|---|---|---|---|
| Driver improvement course (55 and older) | Drivers 55+ who complete an approved course | Course approval and proof | At least 5% per vehicle under state law |
| Automatic payments | Drivers with a reliable bank account or card | Whether it lowers the amount due today or the fees | A missed draft can lead to cancellation |
| Bundling auto with home or renters | Drivers who need property insurance | The combined total of both policies | Can raise the total if the second policy is costly |
| Choose a car that is cheaper to insure | Drivers buying a vehicle | Actual quotes on each car | Averages may not match your quote |
Apart from the 55-and-older course, discount amounts vary by insurer, so we do not list percentages. Never misstate your address, garaging location, mileage, driving record, or household drivers; doing so can void a claim.
Common mistakes when shopping for low-cost insurance in PA
Comparing quotes with different tort or stacking choices. A limited-tort, unstacked quote will look cheaper than a full-tort, stacked one. Match these first.
Judging a quote by the first payment alone. Ask for the total for the term, including every fee.
Assuming you have a grace period. Pennsylvania law does not require one. Pay on or before each due date.
Letting coverage lapse between policies. A lapse of 31 days or more can bring a three-month registration suspension, so start the new policy before the old one ends.
Frequently asked questions
Can I get car insurance in PA with no money down?
Rarely with literally nothing paid. We found no Pennsylvania law setting a down payment, so each insurer's plan decides it, and most collect a first installment before coverage starts. Ask several insurers for the amount due today, with and without automatic payments, and compare the total for the term.
How much is the first payment for car insurance in Pennsylvania?
It depends on your premium and plan. On a hypothetical $960 six-month premium, a one-month start is $160, and a 25% start is $240. GEICO publishes new-policy plans starting at 25% of the premium, or 20% with automatic payments. Get each insurer's Pennsylvania terms in writing.
Is there a grace period for car insurance payments in Pennsylvania?
Not by law. The Pennsylvania Insurance Department says state law does not require insurers to offer a grace period, and an insurer can cancel a policy when payment is not received by the due date. Some companies may allow extra time, but ask; never assume.
Does limited tort lower my car insurance payment?
Yes. The Pennsylvania Insurance Department says limited tort offers significant premium savings, which also reduces each payment. In exchange, you generally cannot sue for pain and suffering unless an exception applies, such as a serious injury. Ask each insurer to quote both options.
What is the minimum car insurance required in Pennsylvania?
Pennsylvania requires $5,000 of medical benefits, bodily injury liability of $15,000 per person and $30,000 per crash, and $5,000 of property damage liability. Lenders usually require collision and comprehensive on financed or leased cars. Many drivers choose higher liability limits.
Who has the cheapest car insurance in Pennsylvania?
In an August 2026 study of a 40-year-old driver, Travelers had the cheapest full coverage at $68 a month, and Westfield the cheapest minimum coverage at $20. A real-quote study ranked State Farm first for full coverage. Your cheapest company depends on your profile, so compare quotes.
Which cars are cheapest to insure in Pennsylvania?
A vehicle-model rate study found the lowest average full-coverage premiums for the Honda HR-V, Honda CR-V, Volkswagen Tiguan, Ford Ranger, and Mini Cooper Countryman JCW, with the Subaru Outback tied for fifth. All were within $47 of each other over six months.
What happens if my car insurance lapses in Pennsylvania?
PennDOT suspends the vehicle's registration for three months unless you prove the lapse lasted under 31 days and the car was not driven. You may instead pay a $500 civil penalty once in 12 months. Driving while uninsured adds a $300 fine and a license suspension.
Final recommendation
In Pennsylvania, your insurer's payment plan, not state law, sets your first payment, so shop for the plan as carefully as the price. Compare the amount due today and the total for the term, along with tort option, stacking choice, limits, fees, and due dates.
Premiums, payment plans, and eligibility vary by insurer and by your circumstances. The rates in this article are averages and hypothetical examples, not quotes. This article is for information only and is not legal or financial advice. The publisher is not an insurance company or a licensed insurance agency.
The bottom line on cheap car insurance in PA with no down payment: expect a modest first installment rather than $0, use Pennsylvania's tort and stacking choices wisely, and choose the policy whose first payment and total cost both fit your budget.
Sources
- Pennsylvania Insurance Department, Auto Insurance Guide (accessed October, 2026).
- Pennsylvania Insurance Department, auto rate stabilization announcement (April 22, 2026).
- 75 Pa.C.S. § 1786, Required financial responsibility (accessed October, 2026).
- PennDOT, Insurance Overview (accessed October 2026).
- Pennsylvania Assigned Risk Plan (AIPSO) (accessed October 2026).
- GEICO, Auto Payment Methods and Plans (accessed October 2026).
- MoneyGeek, Cheapest Car Insurance in Pennsylvania (updated August 25, 2026).
- Insurify, Pennsylvania Car Insurance and Average Cost in Pennsylvania (rates current to September 30, 2026).
- CarInsurance.com, Cheapest Cars to Insure in Pennsylvania (accessed October 2026).
- Insurance Information Institute, Uninsured Motorists, citing the Insurance Research Council.
- Florida Statutes § 627.7295 and TDI Bulletin B-0039-97, for the state comparison.