
Cheap Car Insurance in New York With No Down Payment
If you are looking for cheap car insurance in New York with no down payment, there is one state law to know first. New York's Vehicle and Traffic Law requires the insurance certificate on a new policy to state that at least 10% of the annual premium has been paid. In other words, a true $0 start is not available on a new New York policy, but a first payment as low as one-tenth of the yearly premium is legal.
This guide explains that rule, shows what New Yorkers pay in 2026, lists five vehicles that are cheap to insure, and shows how to start coverage with a small first payment.
KEY TAKEAWAYS
- New York sets a 10% floor. On a new policy, at least 10% of the annual premium must be paid, under Vehicle and Traffic Law § 311(5)(c).
- Minimum coverage averages $57 a month and full coverage $108 for a 40-year-old driver in an August 2026 study, with NYCM and Progressive cheapest.
- Rates may get help from new laws. 2026 reforms target fraud and lawsuit costs, and DFS told insurers to build the projected savings into their rates.
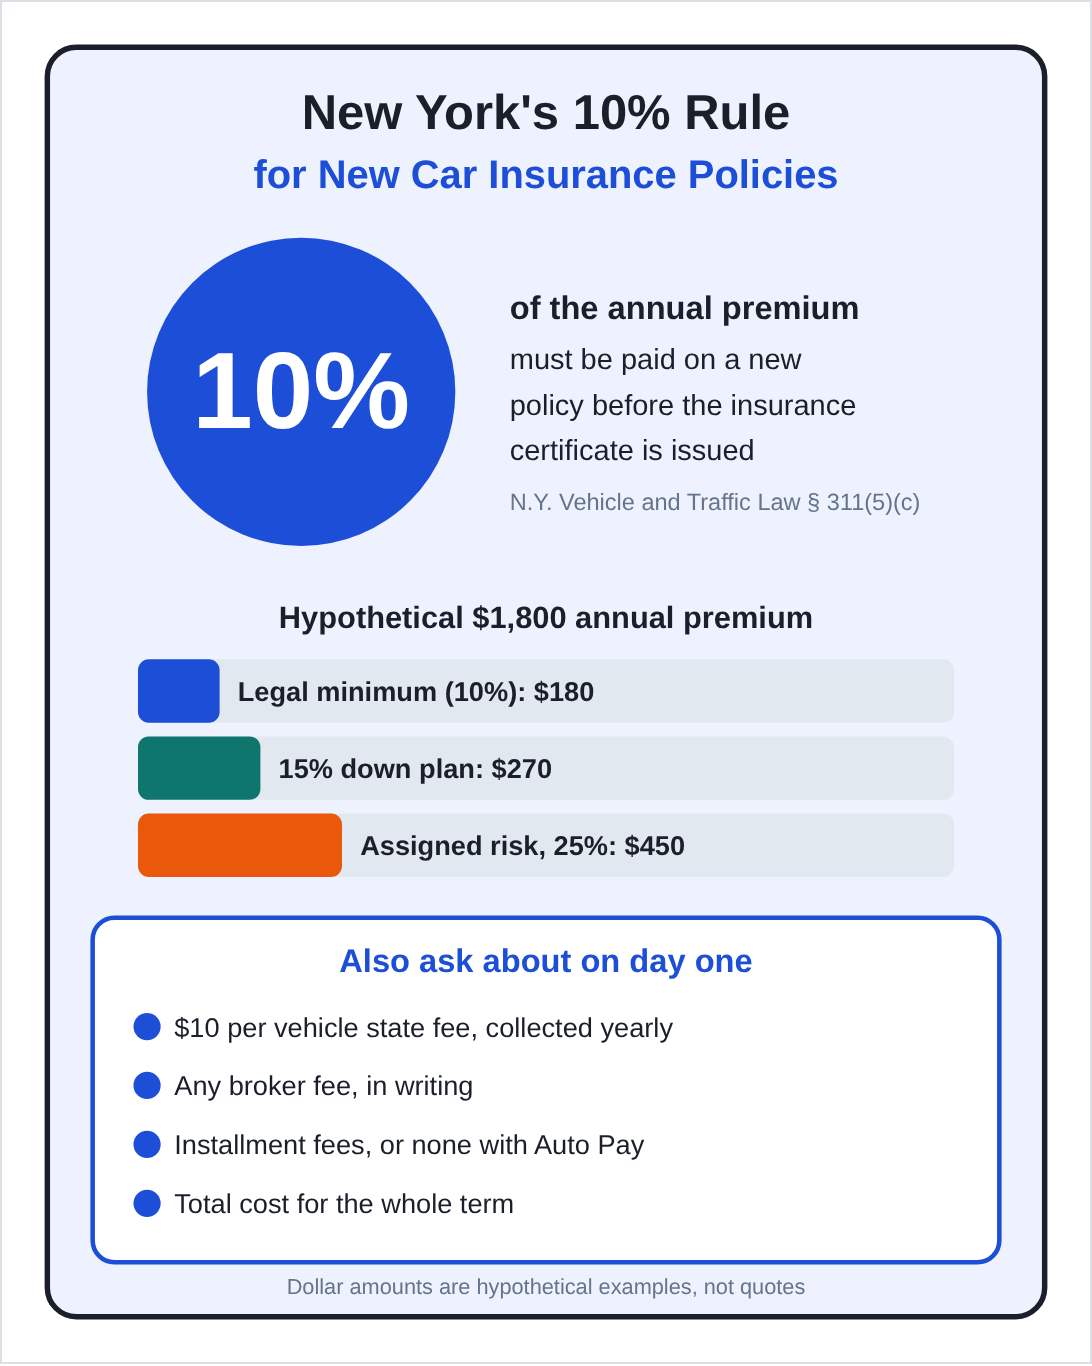
New York's 10% first-payment rule, with a hypothetical $1,800 annual premium. The 15% plan reflects NYCM's published five-, six-, and eleven-payment plans; the 25% figure reflects its published assigned-risk plans. Not quotes.
What "no down payment" means in New York
A car insurance down payment is simply the first part of your premium. The premium is the full price of the policy for its term. In New York, many policies run twelve months, though six-month policies also exist. You pay part of the premium before the policy starts, and the rest in installments.
When an ad says "no down payment," it usually means the first payment is about the same as the payments that follow. In New York, that first payment still has to meet the 10% rule on a new policy.
Three amounts to compare on every New York quote
| Amount | What it covers | Why it matters |
|---|---|---|
| Due today | Your first premium payment plus any fees collected at the start | Decides whether you can start coverage now |
| Each installment | Every later payment, plus any per-payment fee | Must fit your budget for the whole term |
| Total for the term | All payments and fees added together | The true price you are comparing |
New York car insurance requirements
New York requires every registered vehicle to carry bodily injury liability of $25,000 per person and $50,000 per accident, $10,000 of property damage liability, $50,000 of no-fault personal injury protection, and uninsured motorist coverage of $25,000/$50,000, according to DFS.
New York is a no-fault state, so your own no-fault coverage pays your medical bills and some lost wages after a crash, regardless of who caused it. Coverage must come from an insurer licensed in New York; the DMV says out-of-state insurance is not acceptable, and your insurer must report your coverage to the DMV electronically. About 8.6% of New York drivers were uninsured in 2023, among the lowest rates in the country, according to the Insurance Research Council.
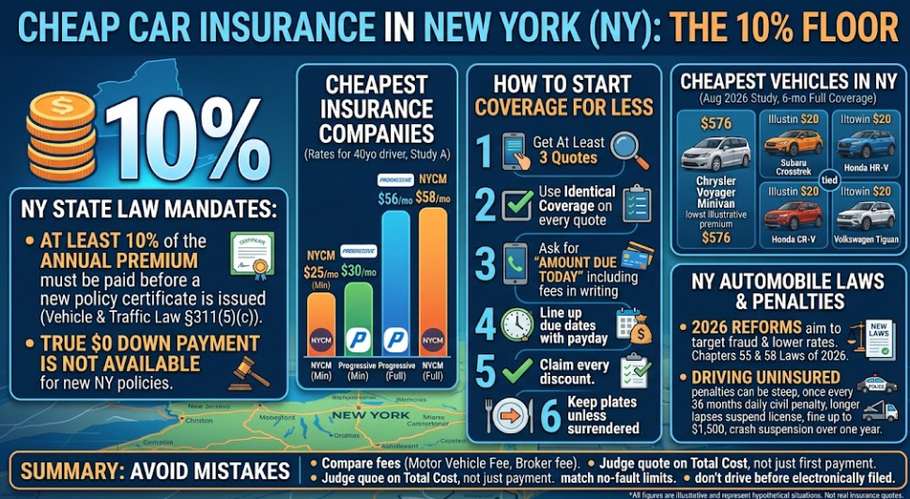
Penalties for a lapse or driving uninsured
If your coverage lapses, the DMV requires you to turn in your plates before the coverage ends. For a lapse of 90 days or less, you may be able to pay a civil penalty instead of a suspension: $8 a day for days 1 to 30, $10 a day for days 31 to 60, and $12 a day for days 61 to 90. The option is limited to once every 36 months.
If the lapse runs past 90 days, your driver's license is suspended too, and reinstatement costs $50.
Driving uninsured can bring a traffic court fine of up to $1,500. If you are in a crash while uninsured, your license and registration are revoked for at least a year, and getting your license back requires an extra $750 civil penalty.
Can you get cheap car insurance in New York with no down payment?
Not with literally $0 on a new policy, because of state law. Vehicle and Traffic Law § 311(5)(c) says the certificate of insurance for a new policy must state that "at least ten per cent of the annual premium due on the policy has been paid." The Department of Financial Services (DFS) confirmed in a 2008 legal opinion that this requires insurers to collect at least 10% of the annual premium on all new policies.
The same opinion added two consumer protections. An insurer must apply the down payment rule in a fair and non-discriminatory manner, and different down payments are allowed only when they are based on underwriting criteria related to the risk. DFS also warned that varying down payments based only on where a driver lives could violate New York's anti-redlining law.
When the 10% rule does not apply
The statute says a transfer of insurance from one company to another by an agent or broker is not treated as issuing a new policy. Renewals of an existing policy are also not new policies.
New York protects installment plans
In a 2000 circular letter, DFS warned insurers that offering installment options to some classes of policyholders but withholding them from others could raise unfair-discrimination concerns. It also said refusing financed premiums could, in some cases, violate state insurance law. Premium finance companies in New York must be licensed under Article XII-B of the Banking Law.
First-payment levels we could verify in New York
| Source | Upfront amount | Later payments | Note |
|---|---|---|---|
| State law (VTL § 311(5)(c)) | At least 10% of the annual premium on a new policy | Set by the insurer | The legal floor, not a guaranteed offer |
| NYCM published plans | 15% on five-, six-, or eleven-payment plans | Balance split over the remaining installments | No installment fees with Auto-Pay, per NYCM |
| NYCM two-payment plan | 50% | Balance due 60 days later | Fewer payments, larger start |
| Assigned risk plans (as published by NYCM) | 25% | Two-pay: balance in 30 days; six-pay: five payments of 15% | Six-pay requires a premium of at least $300 |
NYCM says payment plan options, fees, and availability vary by policy. Ask each insurer for its New York terms in writing.
Day-one costs beyond the premium
- Motor Vehicle Law Enforcement Fee: NYCM lists a $10 fee per insured vehicle, collected annually by New York State.
- Broker fees: some brokers charge a fee on top of the premium. DFS says the New York Automobile Insurance Plan caps the broker's fee at $50 for assigned-risk policies.
- Installment fees: many insurers charge a fee per installment, though some waive it with automatic payments.
The cheapest car insurance companies in New York
NYCM had the lowest minimum-coverage rate in an August 2026 study of a 40-year-old New York driver, at $25 a month, and Progressive had the lowest full-coverage rate, at $56. Kemper, American Family, and GEICO also came in well below the state averages.
A second analysis, based on real quotes current to September 30, 2026, ranked Erie first, at $62 a month for liability-only coverage and $94 for full coverage, followed by USAA, which serves military members and their families. The two studies use different drivers and limits, so compare each study’s numbers only with each other.
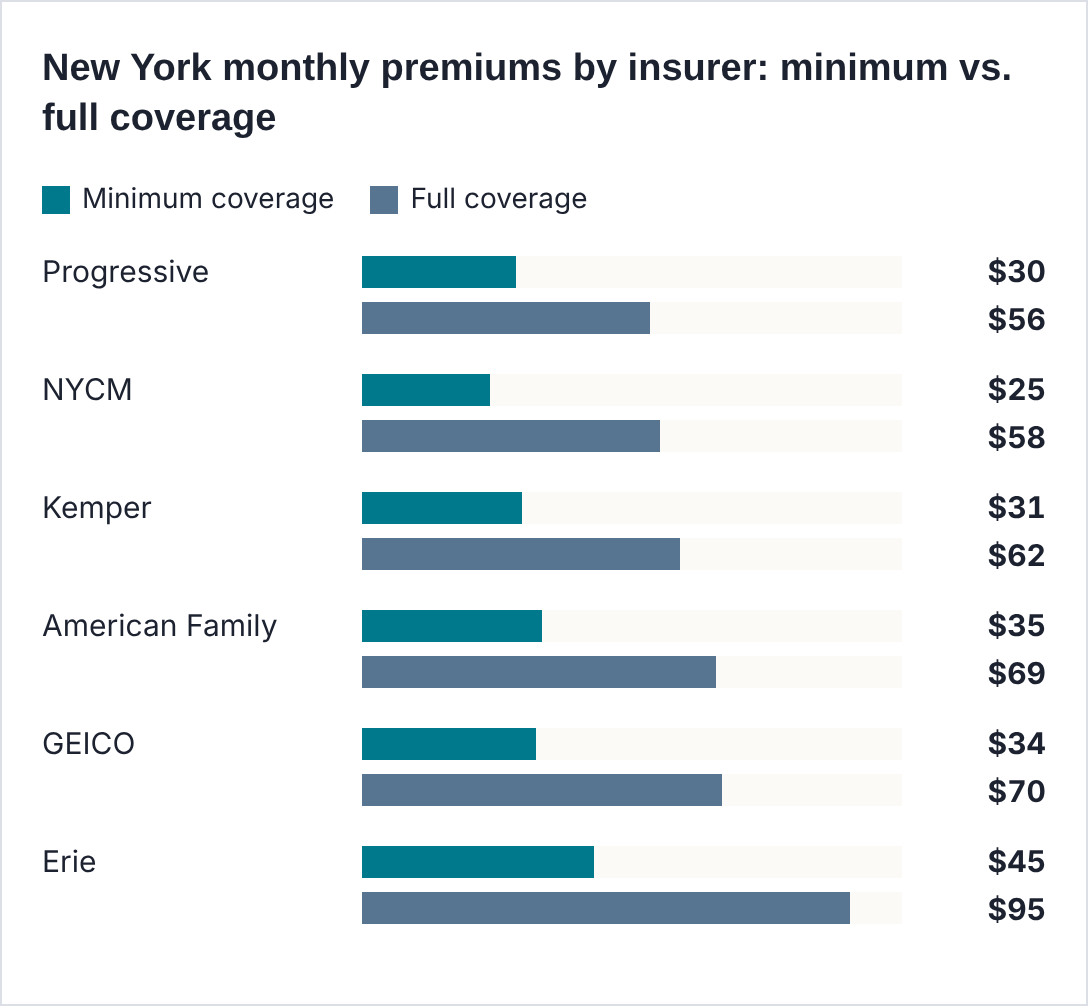
Study A: rate study updated August 13, 2026. Driver: 40-year-old man, clean record, good credit. Full coverage: 100/300/100 liability with a $1,000 deductible. Minimum: New York minimum limits with $50,000 PIP and 25/50 uninsured motorist coverage. Statewide averages.
New York insurers in two 2026 rate studies
| Insurer | Minimum, study A (monthly) | Full coverage, study A (monthly) | Liability-only, study B (monthly) | Full coverage, study B (monthly) |
|---|---|---|---|---|
| Progressive | $30 | $56 | Not publicly confirmed | Not publicly confirmed |
| NYCM | $25 | $58 | Not publicly confirmed | Not publicly confirmed |
| Kemper | $31 | $62 | Not publicly confirmed | Not publicly confirmed |
| GEICO | $34 | $70 | $101 | $152 |
| Erie | $45 | $95 | $62 | $94 |
| State Farm | $62 | $113 | $89 | $134 |
| Allstate | $80 | $146 | $103 | $161 |
Study A: rate study updated August 13, 2026 (profile above). Study B: real quotes current to September 30, 2026; its liability-only policies use limits between the state minimum and $50,000/$100,000, with $1,000 deductibles on full coverage. "Not publicly confirmed" means the study did not publish that figure.
How much does car insurance cost in New York?
New York minimum coverage averages $57 a month, and full coverage averages $108 in study A. Study B, which uses real quotes from a broader group of drivers, puts the averages much higher: $145 for liability-only coverage and $218 for full coverage.
Where you live matters a great deal in New York, along with your age, driving record, vehicle, coverage, and credit history. The chart shows how one change in the profile moved the statewide full-coverage average in study A.
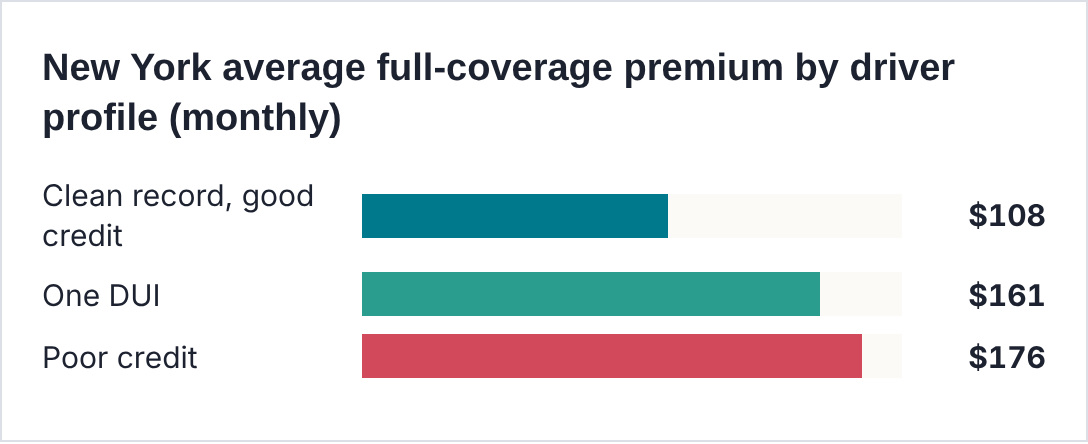
Study A, updated August 13, 2026. Statewide averages for a 40-year-old driver with 100/300/100 limits and a $1,000 deductible; each bar changes one factor from the clean-record, good-credit profile.
Young drivers on a family policy pay more, though study A found some low figures for New York. NYCM was cheapest for an 18-year-old male at $112 a month and a 21-year-old male at $86, and Progressive for a 25-year-old male at $65.
Minimum coverage vs. full coverage in New York
| Minimum required coverage | Full coverage | |
|---|---|---|
| What it pays for | Injuries and damage you cause, your own no-fault benefits, and injuries from uninsured drivers | Minimum coverage plus higher limits and damage to your own car |
| Required by New York law? | Yes: 25/50 bodily injury, $10,000 property damage, $50,000 no-fault, 25/50 uninsured motorist | No, but lenders and leasing companies usually require collision and comprehensive |
| Average monthly cost, study A (40-year-old) | $57 | $108 (100/300/100 limits) |
| Average monthly cost, study B (real quotes) | $145 (liability-only) | $218 |
| What it leaves out | Repairs to your own car | Little for most drivers, depending on limits |
Figures are averages, not quotes. Minimum limits are from DFS's auto insurance checklist.
New York's 2026 auto insurance reforms
New York changed its auto insurance laws in 2026, and the goal is lower premiums. Chapters 55 and 58 of the Laws of 2026, signed in May, expanded the definition of insurance fraud to target staged crashes, revised the serious injury threshold under the no-fault law, adopted a modified comparative negligence standard for motor vehicle injury claims, and limited non-economic damages in certain cases involving uninsured, impaired, or felony offenders.
On July 1, 2026, DFS told insurers to estimate the savings from these reforms and build them into pending and future rate filings, and it gave insurers with pending filings until August 31 to amend them. On September 9, DFS proposed a regulation requiring prior approval for any private passenger auto rate increase. DFS says the changes take effect November 27, 2026. No one can promise your premium will fall, but compare quotes again at renewal.
Five vehicles that cost less to insure in New York
Your vehicle affects your premium, and a smaller premium means a smaller first payment. A rate study updated August 13, 2026, compared average six-month full-coverage premiums by model across New York, using sample 18- and 40-year-old drivers, 100/300/100 limits, and $500 deductibles.
A minivan led the list by a wide margin, and the next four were small SUVs within $20 of each other over six months.
1. Chrysler Voyager
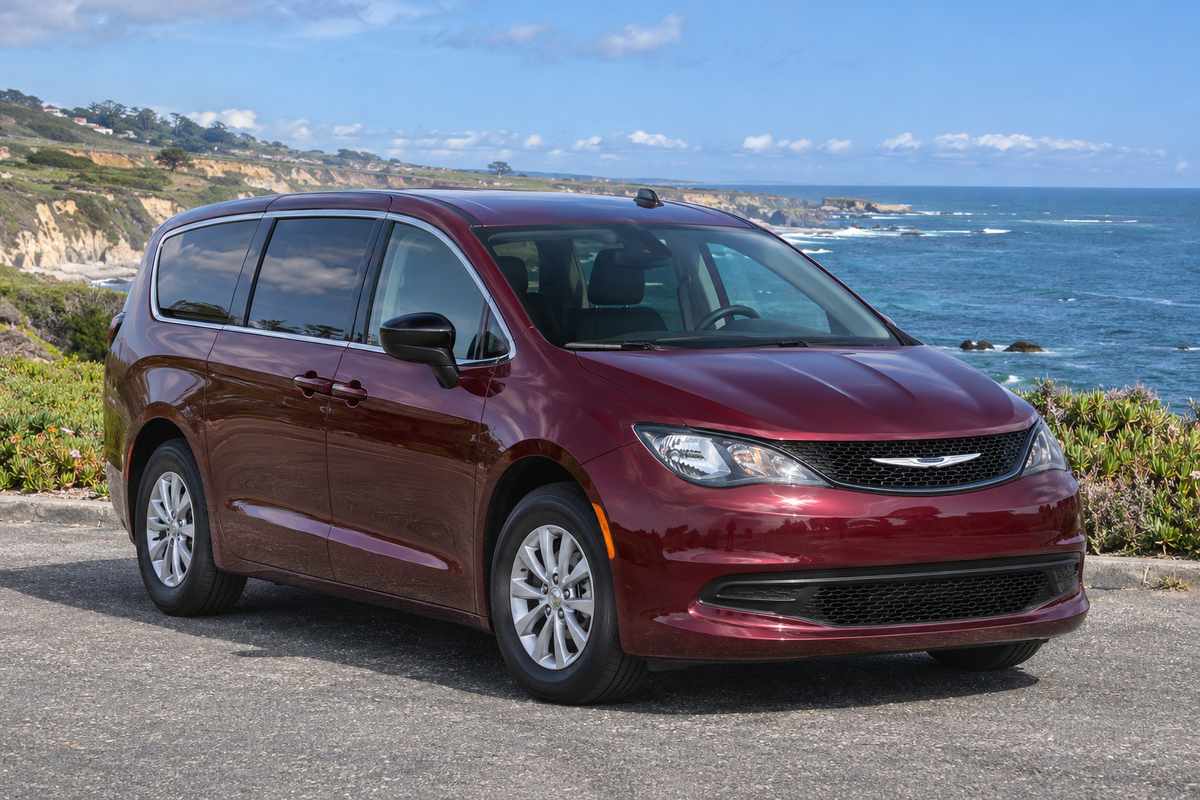
Original vector illustration of the Chrysler Voyager, a minivan. Illustration only; not to scale.
Average premium: $576 for six months of full coverage in New York. The Chrysler Voyager is a minivan. It had the lowest average premium in the New York study, $127 below the next model over six months.
2. Subaru Crosstrek
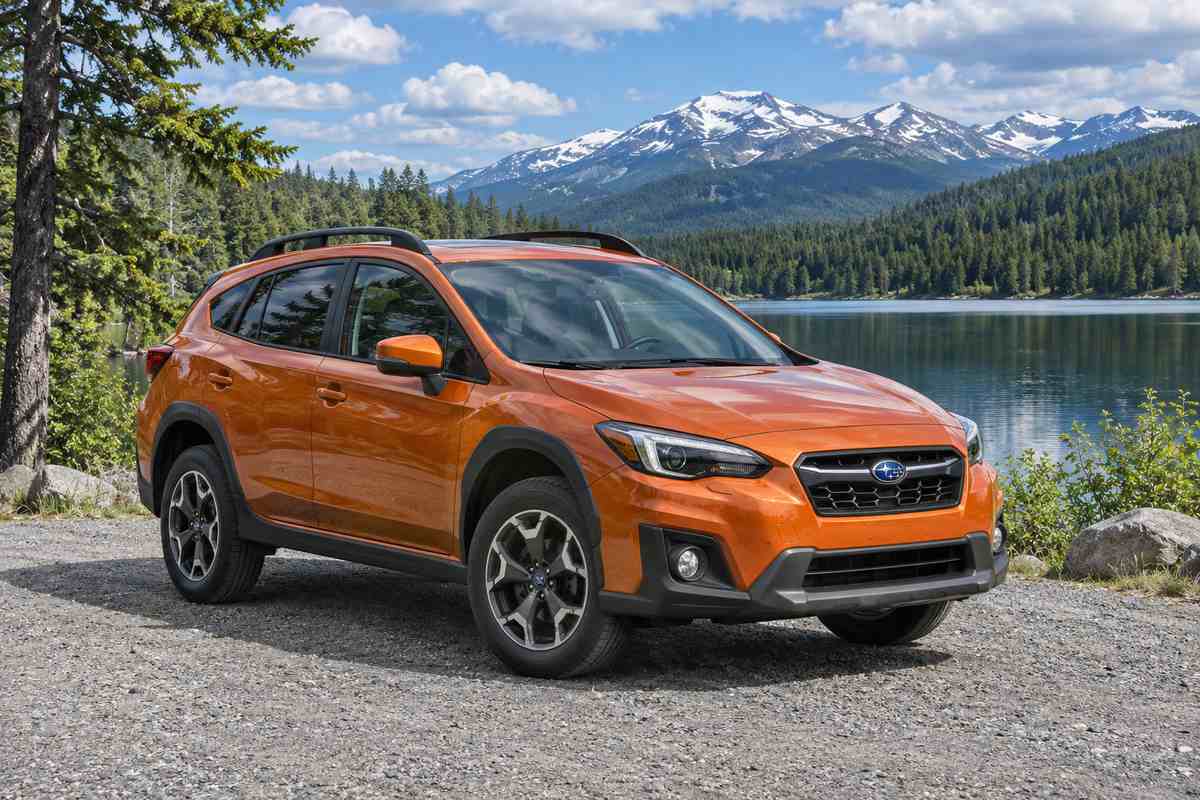
Original vector illustration of the Subaru Crosstrek, a subcompact SUV. Illustration only; not to scale.
Average premium: $703 for six months of full coverage in New York. The Subaru Crosstrek is a subcompact SUV. It ranked second, the lowest-priced SUV on the list.
3. Honda HR-V
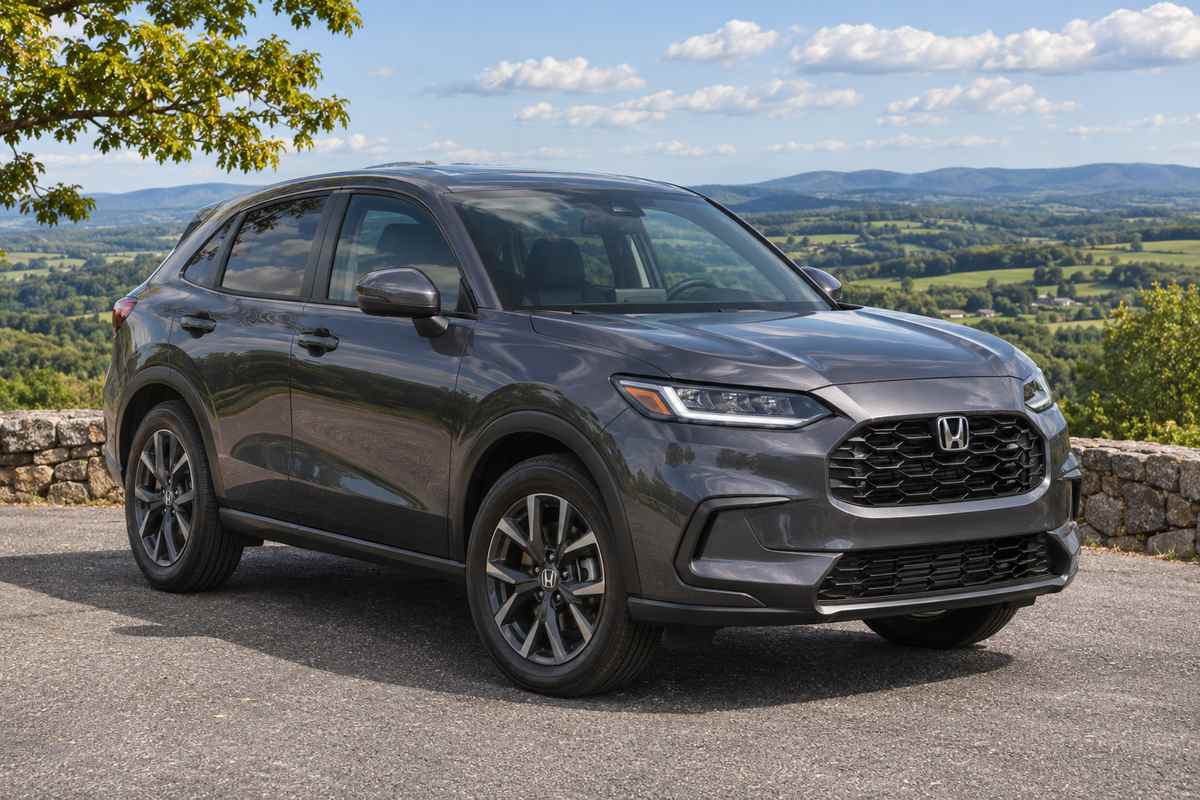
Original vector illustration of the Honda HR-V, a subcompact SUV. Illustration only; not to scale.
Average premium: $704 for six months of full coverage in New York. The Honda HR-V is a subcompact SUV. It ranked third, just $1 behind the Crosstrek.
4. Honda CR-V
Original vector illustration of the Honda CR-V, a compact SUV. Illustration only; not to scale.
Average premium: $715 for six months of full coverage in New York. The Honda CR-V is a compact SUV. It ranked fourth, $12 above the HR-V over six months.
5. Volkswagen Tiguan
Original vector illustration of the Volkswagen Tiguan, a compact SUV. Illustration only; not to scale.
Average premium: $723 for six months of full coverage in New York. The Volkswagen Tiguan is a compact SUV. It rounded out the five, $147 above the Voyager over six months.
Five vehicles with the lowest average insurance premiums in New York
| Rank | Make and model | Model year | Average six-month premium | Insurance-cost finding | Source and date |
|---|---|---|---|---|---|
| 1 | Chrysler Voyager | Not specified by source | $576 | Lowest in the study; only minivan | Vehicle-model rate study, Aug. 13, 2026 |
| 2 | Subaru Crosstrek | Not specified by source | $703 | Lowest-priced SUV | Vehicle-model rate study, Aug. 13, 2026 |
| 3 | Honda HR-V | Not specified by source | $704 | $1 behind the Crosstrek | Vehicle-model rate study, Aug. 13, 2026 |
| 4 | Honda CR-V | Not specified by source | $715 | $12 above the HR-V | Vehicle-model rate study, Aug. 13, 2026 |
| 5 | Volkswagen Tiguan | Not specified by source | $723 | Fifth-lowest; $147 above first | Vehicle-model rate study, Aug. 13, 2026 |
Statewide New York averages for sample 18- and 40-year-old drivers, full coverage at 100/300/100 with $500 deductibles. The study does not publish model years. For an 18-year-old, the Voyager averaged $1,625 for six months.
To connect the car to your first payment: on a six-month policy, 10% of the annual premium equals 20% of the six-month premium. On these averages, that is about $115 for the Voyager and $145 for the Tiguan (our calculation), before fees. These are illustrations, not quotes.
How to get cheap car insurance in New York with no down payment
Aim for the smallest legal first payment on a policy whose total you can also afford. Work through these steps in order.
- 1. Get at least three quotes. In study A, full coverage ranged from $56 to $175 a month among the ten insurers listed.
- 2. Use identical coverage on every quote. Match liability limits, no-fault and uninsured motorist limits, deductibles, drivers, and term.
- 3. Ask for the amount due today, including fees, with and without automatic payments.
- 4. Ask whether your quote is a new policy or a transfer, since a broker-arranged transfer is not treated as a new policy under the 10% rule.
- 5. Compare installment fees and due dates, and add them to find the total for the term.
- 6. Confirm the effective date and that the insurer has reported coverage to the DMV, and keep your old policy active until the new one starts.
First payment vs. total cost: a hypothetical comparison
The chart uses a hypothetical $1,800 annual premium. It compares paying in full, the 10% legal minimum, a 15% start on an eleven-payment plan with and without automatic payments, and a 25% assigned-risk six-payment plan. A $5 installment fee without automatic payments is our assumption; NYCM says its Auto-Pay has no installment fees.
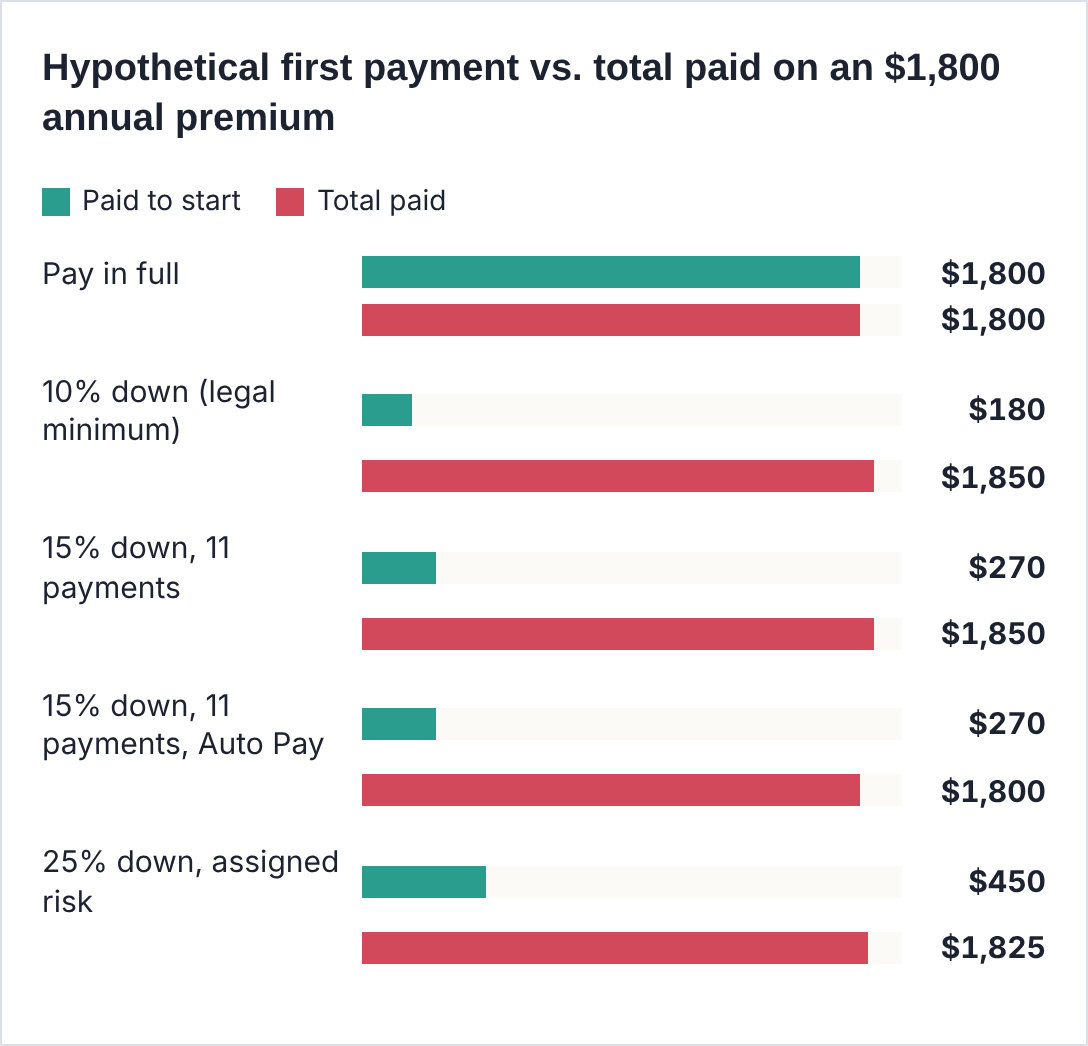
Hypothetical example calculated by us. The 10% floor is from N.Y. VTL § 311(5)(c); the 15% and 25% levels are from NYCM's published plans. The $5 fee is an assumption, not a real charge, and state fees are excluded.
Hypothetical payment plans on an $1,800 annual premium
| Plan | Paid to start | Later payments | Assumed fees | Total paid |
|---|---|---|---|---|
| Pay in full | $1,800 | None | $0 | $1,800 |
| 10% down (legal minimum), 11 payments | $180 | 10 × $162 | $50 (10 × $5) | $1,850 |
| 15% down, 11 payments | $270 | 10 × $153 | $50 (10 × $5) | $1,850 |
| 15% down, 11 payments, Auto Pay | $270 | 10 × $153 | $0 | $1,800 |
| 25% down, assigned-risk six-payment | $450 | 5 × $270 | $25 (5 × $5) | $1,825 |
All figures are hypothetical and calculated by us. They are not insurer quotes, and they exclude the $10-per-vehicle state fee and any broker fee. Not every insurer offers a 10% start.
Discounts and other ways to lower the cost
Every dollar you take off the premium also comes off your first payment. One discount is especially valuable in New York: completing a DMV-approved accident prevention course, also called the Point and Insurance Reduction Program, reduces the base rate of your auto insurance premiums by 10% each year for three years, according to the DMV.
Ways to lower your New York premium or first payment
| Discount or strategy | Who may qualify | What to verify | Limitation |
|---|---|---|---|
| Accident prevention course (PIRP) | Drivers who complete a DMV-approved course | Proof of completion sent to the insurer | 10% of base rate for three years; retake every 36 months |
| Automatic payments | Drivers with a reliable bank account or card | Whether fees are waived | Missed drafts can lead to cancellation |
| Anti-theft device | Vehicles with qualifying devices | Which devices count | Savings vary by insurer |
| Bundling auto with home or renters | Drivers who need property insurance | The combined total of both policies | Can raise the total if the second policy is costly |
| Higher deductible | Drivers with savings for a claim | That you could pay it after a crash | Raises your out-of-pocket cost |
| Choose a car that is cheaper to insure | Drivers buying a vehicle | Actual quotes on each car | Averages may not match your quote |
Apart from the accident prevention course, discount amounts vary by insurer, so we do not list percentages. Never misstate your address, garaging location, mileage, driving record, or household drivers; doing so can void a claim.
Common mistakes when shopping for low-cost insurance in NY
Comparing the premium but not the fees. A broker fee, installment fees, and the state's $10 vehicle fee can all appear on day one. Ask for the full amount due.
Judging a quote by the first payment alone. A 10% start with fees can cost more over a year than a 15% start with no fees.
Comparing quotes with different no-fault or uninsured motorist limits. Match every limit before comparing prices.
Keeping plates on a car with no coverage. In New York, a lapse without surrendered plates leads to penalties or a suspension, so turn in the plates or keep coverage active.
Frequently asked questions
Can I get car insurance in New York with no money down?
Not on a new policy. New York's Vehicle and Traffic Law requires at least 10% of the annual premium to be paid before the insurance certificate is issued. A broker-arranged transfer between companies is not treated as a new policy. Ask insurers whether they accept a 10% start and what fees apply.
How much is the first payment for car insurance in New York?
At least 10% of the annual premium on a new policy, plus any fees. On a hypothetical $1,800 annual premium, that is $180. NYCM publishes plans with 15% down, and its assigned-risk plans start at 25%. Your amount depends on your premium and the insurer's plan.
Can I pay New York car insurance monthly?
Usually, yes. Many insurers offer monthly installment plans after the first payment, and DFS has warned insurers that withholding installment options from some policyholder groups can raise unfair-discrimination concerns. Ask each insurer to list its plans, fees, and due dates.
Does paying monthly cost more overall?
It can. Many insurers charge a fee on each installment, which adds up on an eleven-payment plan. Some, like NYCM, say their automatic payment option carries no installment fees. Compare the total of all payments, using identical coverage, before choosing a plan.
What is the minimum car insurance required in New York?
New York requires 25/50 bodily injury liability, $10,000 property damage liability, $50,000 of no-fault personal injury protection, and 25/50 uninsured motorist coverage. Coverage must come from an insurer licensed in New York. Lenders usually require collision and comprehensive on financed or leased cars.
Who has the cheapest car insurance in New York?
In an August 2026 study of a 40-year-old driver, NYCM was cheapest for minimum coverage at $25 a month and Progressive for full coverage at $56. A real-quote study ranked Erie first. Your cheapest company depends on your profile and location, so compare quotes.
Which cars are cheapest to insure in New York?
An August 2026 study found the lowest average full-coverage premiums for the Chrysler Voyager, Subaru Crosstrek, Honda HR-V, Honda CR-V, and Volkswagen Tiguan. The Voyager averaged $576 for six months, well below the rest. A cheaper car lowers your premium and, with it, your first payment.
What happens if my car insurance lapses in New York?
You must turn in your plates before coverage ends. For lapses of 90 days or less, you may pay a daily civil penalty of $8 to $12 instead of a suspension, once every 36 months. Longer lapses also suspend your license, and driving uninsured can bring fines up to $1,500.
Final recommendation
In New York, the smallest legal first payment on a new policy is 10% of the annual premium, and the real question is what each plan costs in total. Compare the amount due today, every fee, coverage limits, eligibility, and the effective date.
Premiums, payment plans, and eligibility vary by insurer and by your circumstances. The rates in this article are averages and hypothetical examples, not quotes. This article is for information only and is not legal or financial advice. The publisher is not an insurance company or a licensed insurance agency.
The bottom line on cheap car insurance in New York with no down payment: expect to pay at least 10% of the annual premium to start, ask about automatic payments and fees, and choose the policy whose first payment and total cost both fit your budget.
Sources
- N.Y. Vehicle and Traffic Law § 311 and § 313 (accessed October, 2026).
- NY Department of Financial Services, OGC Opinion No. 08-10-04: Down Payment for Personal Automobile Insurance (October, 2008).
- DFS, Insurance Circular Letter No. 25 (2000): Restriction of Installment Payment Plans and Financed Premiums.
- DFS, Auto Insurance Checklist (2025) and DFS Consumer Automobile FAQ.
- DFS press release on proposed auto rate regulation (September 9, 2026).
- PIA Northeast, DFS guidance on 2026 auto insurance reforms (July 8, 2026).
- NY DMV, Auto Liability Insurance and Point and Insurance Reduction Program (accessed October 2026).
- NYCM Insurance, Payment Plans and Assigned Risk Plans (accessed October 2026).
- MoneyGeek, Cheapest Car Insurance in New York (updated August 13, 2026).
- Insurify, New York Car Insurance (rates current to September 30, 2026).
- CarInsurance.com, Cheapest Cars to Insure in New York (updated August 13, 2026).
- Insurance Information Institute, Uninsured Motorists, citing the Insurance Research Council.