
Pay As You Go Car Insurance in Arizona
Arizona has more choices than almost any other state for drivers shopping for the best pay as you go car insurance in Arizona, from a homegrown pay-per-mile insurer to Lemonade, Mile Auto, Allstate Milewise, and Nationwide SmartMiles. Arizona drivers also log fewer miles than the national average, and the state lets you "de-insure" a car you are not driving, which makes paying by the mile a natural fit for many households.
This guide ranks the best options, names the overall cheapest pay as you go company in Arizona, and explains how each one charges. It also shows what Arizona drivers pay, how many miles you can drive before pay-per-mile stops saving money, how Arizona's lapse rules and $50 reinstatement fee work, and which safe-driving discounts can beat pay-per-mile for higher-mileage drivers.
KEY TAKEAWAYS
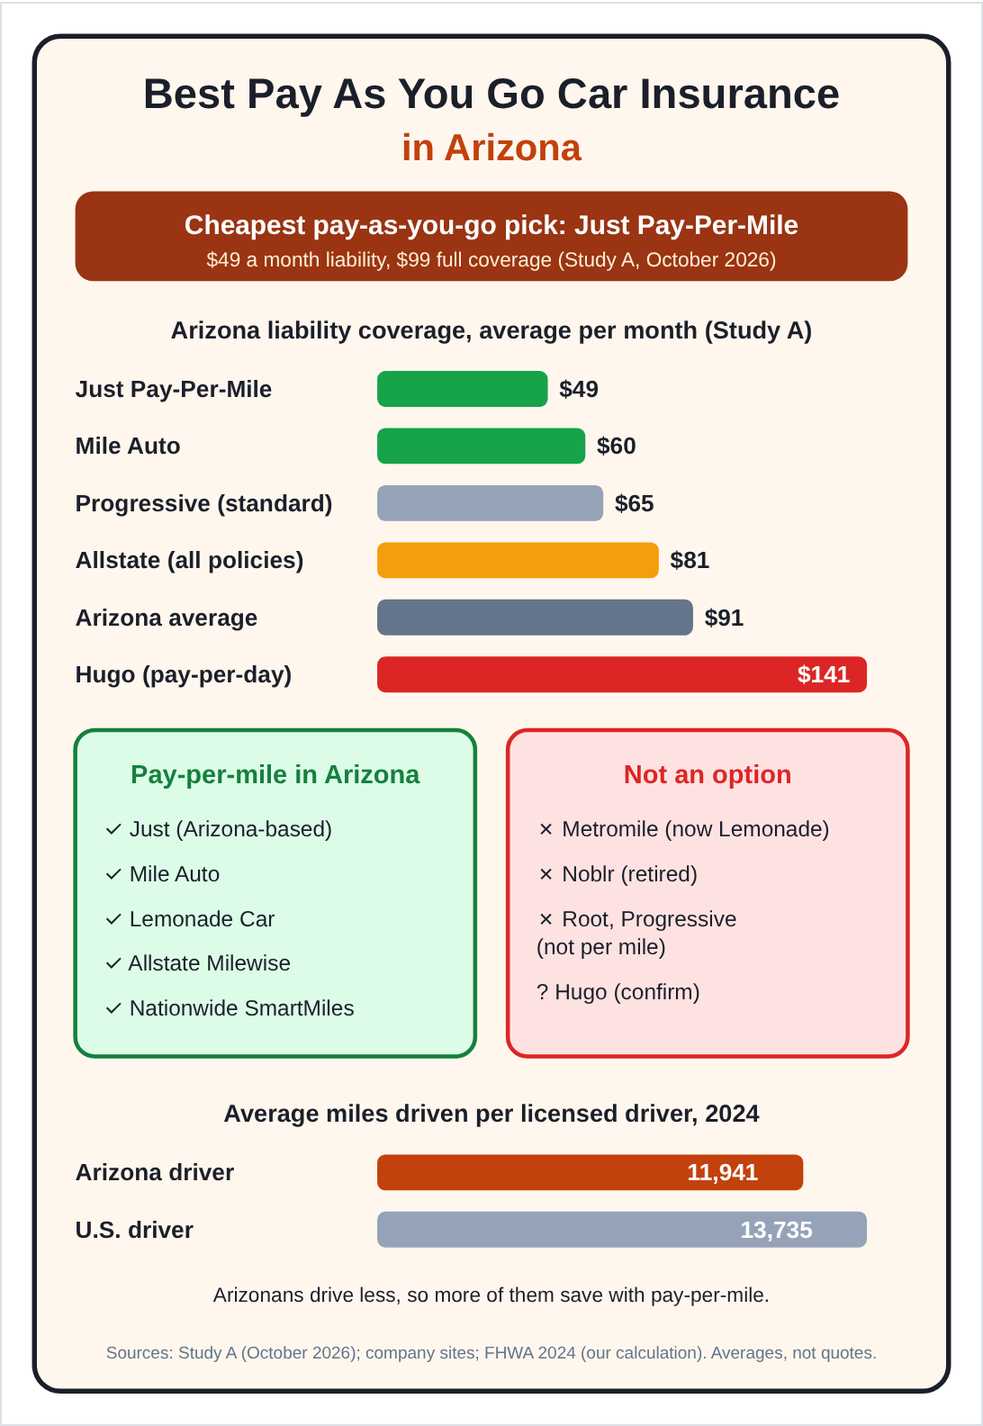
- Just Pay-Per-Mile is the cheapest pay as you go car insurance company in Arizona in 2026 data, averaging $49 a month for liability and $99 for full coverage in Study A, followed by Mile Auto at $60 and $112.
- Arizona is one of only three states where Lemonade still prices by the mile, and Nationwide SmartMiles, Allstate Milewise, and USAA SafePilot Miles are sold here too.
- Arizona drivers average about 11,900 miles a year, below the roughly 13,700 national figure, so pay-per-mile saves money for more Arizonans than in most states.
What "pay as you go" car insurance means in Arizona
The phrase covers three different products, and only two of them change your price based on how much you drive. Knowing which one you are buying is the first step to finding the best fit.
Three types of pay as you go car insurance in Arizona
Type | How you pay | Arizona examples | Watch out for |
|---|---|---|---|
Pay-per-mile | A base rate plus a charge for each mile | Just, Mile Auto, Lemonade, Milewise, SmartMiles | Costs more if you drive a lot |
Pay-per-day | Coverage bought in short blocks of days | Hugo (availability unconfirmed) | Among the priciest options in Study A |
Monthly or low down payment | A standard policy paid month to month | Many standard insurers | The total premium does not drop |
Company sites and 2025 to 2026 reviews (accessed November 13, 2026). Availability can change; confirm with a quote.
A fourth option often lumped in is usage-based insurance, or telematics, which prices how you drive rather than how far. Arizona drivers have plenty of these, including Nationwide SmartRide and American Family's mileage-based MilesMyWay, and they are covered later in this guide.
How pay-per-mile insurance charges you
Every pay-per-mile policy uses one formula. A base rate covers your car while it is parked and reflects your age, record, car, credit, and ZIP code. Then you pay a few cents for each mile you drive, so your bill rises and falls with your mileage.
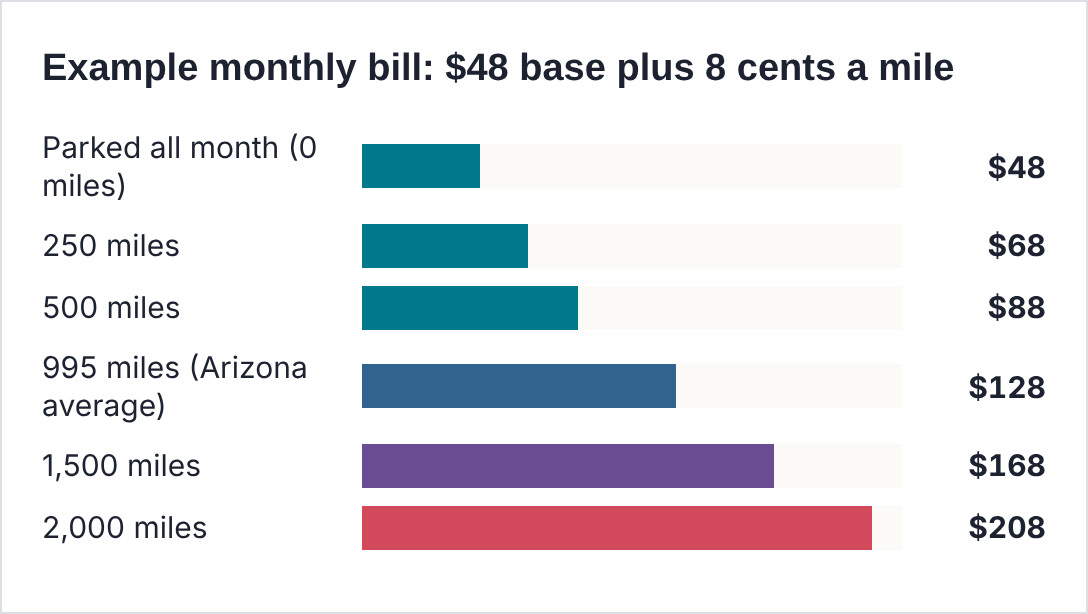
Programs track miles in different ways. Just and Mile Auto rely on odometer photos, Lemonade and Milewise use apps or devices, and SmartMiles uses a plug-in device or a connected car. Some cap the miles they charge in a day; SmartMiles counts only the first 250, which helps on a drive from Phoenix to San Diego or the Grand Canyon.
The best pay as you go car insurance companies in Arizona
We compared every major pay-per-mile and pay-per-day program against official availability pages and 2026 reviews. Here is how they rank for Arizona drivers, based on price, availability, and features.
Best pay as you go car insurance in Arizona, 2026
Rank | Company | Best for | Arizona details |
|---|---|---|---|
1 | Just Pay-Per-Mile | Lowest price; prepaid flexibility | $49 liability, $99 full coverage (Study A); Arizona-based |
2 | Mile Auto | No app or device | $60 liability, $112 full coverage (Study A); odometer photo |
3 | Lemonade Car | App-first drivers and Tesla owners | Pay-per-mile in Arizona; 50% off Full Self-Driving miles |
4 | Nationwide SmartMiles | Big-name insurer and road trips | 250-mile daily cap; up to 10% safe-driving discount |
5 | Allstate Milewise | Bundling with Allstate home or renters | About $79 liability in an older review; device or app |
6 | USAA SafePilot Miles* | Military families | Up to 20% for low mileage plus up to 20% for safe driving |
Study A: Arizona rate data updated October 21 to 28, 2026, from the publisher's user quotes. Company pages and 2023 to 2026 reviews (accessed November 13, 2026). Allstate's and Mile Auto's own sites could not be checked for this article. *USAA is available only to military members, veterans, and their families.
1. Just Pay-Per-Mile: best overall and cheapest
Just is an Arizona-based insurer that launched its pay-per-mile coverage in Arizona in 2020, and its app now lists Arizona and Nevada as its states. Instead of a monthly bill, you prepay a balance that is drawn down as you drive, and its liability plan starts with a 30-day prepaid option of about $30. You report miles with odometer photos, and the app also tracks your driving to build a score.
Its price is its biggest strength. In Study A, Just Pay-Per-Mile averaged $49 a month for liability and $99 for full coverage, the lowest of any pay-as-you-go company in Arizona and well below the state averages of $91 and $162. Just's pay-per-mile plan is designed for people who drive under 1,000 miles a month; it also sells an Unlimited plan at a flat rate, which averaged $82 and $174 in Study A, for drivers who go over that.
2. Mile Auto: best for drivers who want no tracking
Mile Auto uses no app and no plug-in device. Each month, you photograph your odometer, and your bill is a base rate plus your miles times a per-mile rate, with one 2026 review citing about $48 a month plus 8 cents a mile. Arizona is one of its seven states.
In Study A, Mile Auto averaged $60 a month for liability and $112 for full coverage. Send each photo on time; a 2024 firsthand review in another state reported that late photos were billed as if the driver had covered 75 miles a day.
3. Lemonade Car: best for app-first drivers and Tesla owners
Arizona is one of only three states, along with Oregon and Washington, where Lemonade still sets rates by the mile, according to two 2025 to 2026 reviews. Lemonade launched its car insurance in Arizona in November 2023 and took over Metromile's customers after buying the company in 2022.
Pricing is a base rate plus a per-mile rate, tracked through its app. Tesla owners get a standout perk: miles driven on Full Self-Driving are charged at a 50% discount, measured through Tesla's data connection. No third-party Arizona average was available, so get a quote to compare.
4. Nationwide SmartMiles: best big-name option
SmartMiles is available in Arizona; Nationwide's page excludes only Alaska, Hawaii, Louisiana, Michigan, North Carolina, New York, and Oklahoma. A footnote says program criteria differ in Arizona, without details, so ask about Arizona terms.
Your bill is a base premium plus a per-mile rate; only the first 250 miles a day count, and safe drivers can earn up to 10% off at renewal. Study A did not publish an Arizona SmartMiles average, but a 2025 review of real quotes in another state found about $984 a year plus 5.5 cents a mile for full coverage.
5. Allstate Milewise: best for Allstate bundlers
Milewise charges a daily base rate plus a per-mile rate; one commonly cited example is $1.50 a day plus 6 cents a mile.
Arizona was Allstate's test market for a twist: in 2019, it began a pilot that recalculated Arizona Milewise rates weekly based on both miles and driving quality, so rates could move up or down. We could not confirm whether that format is still in use, so ask when you quote. An older review put Arizona Milewise averages at $79 a month for liability and $125 for full coverage.
6. USAA SafePilot Miles: best for military families
Arizona is home to several military bases, and USAA's SafePilot Miles is available in every state except California, Maryland, Michigan, New Jersey, New York, North Carolina, and Pennsylvania. It combines a fixed rate with a monthly mileage adjustment and promises up to 20% savings for low mileage, plus up to 20% at renewal for safe driving. USAA's overall Arizona averages in Study A were $67 a month for liability and $114 for full coverage.
Hugo, Metromile, and Noblr
Hugo sells pay-by-the-day coverage in blocks of 3 to 30 days or six months. It holds an Arizona license, and Study A listed an Arizona average of $141 a month for liability, but one competitor says Hugo sells only in three other states, so confirm with a quote. Metromile no longer exists as a brand after Lemonade bought it, and USAA wound down its Noblr pay-per-mile program, so pages that still recommend either in Arizona are out of date.
The overall cheapest pay as you go car insurance company in Arizona
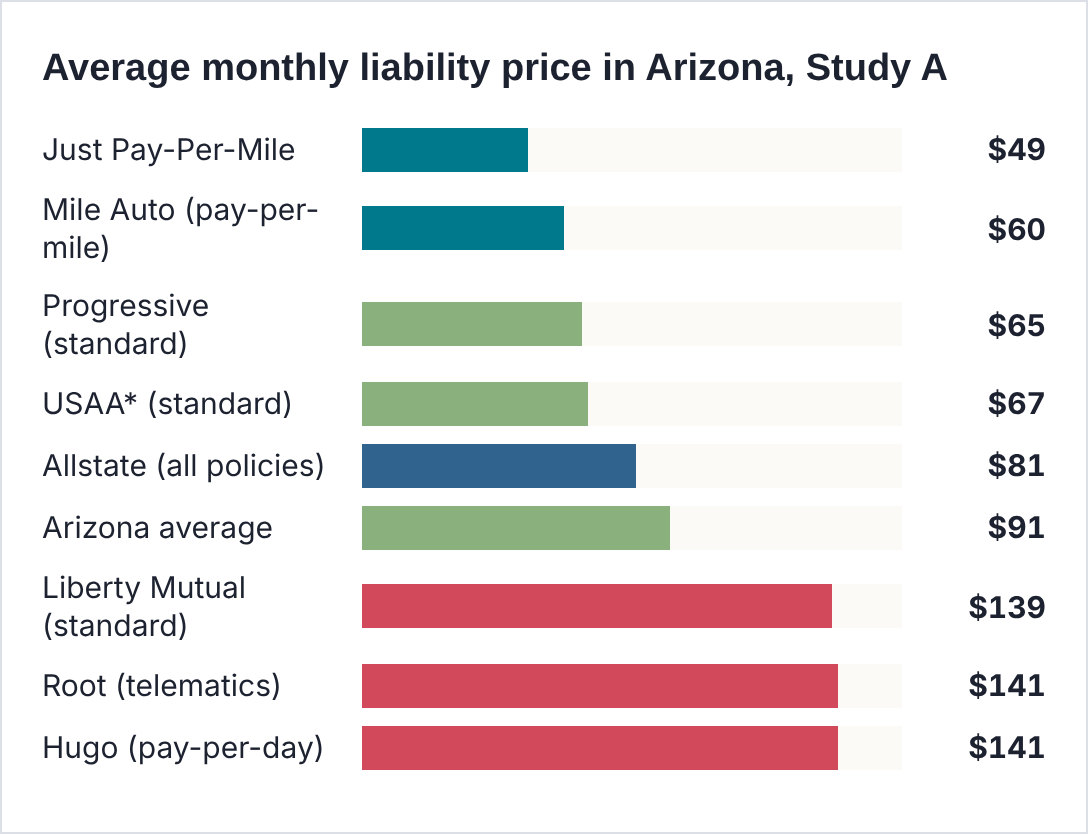
Just Pay-Per-Mile is the overall cheapest pay as you go car insurance company in Arizona, based on the most recent published data. In Study A, an Arizona rate study updated October 21 to 28, 2026, Just averaged $49 a month for liability-only coverage and $99 for full coverage. That was 46% less than the $91 state liability average and 39% less than the $162 full coverage average (our calculation).
Cheapest pay as you go options in Arizona, ranked by price
Rank | Company | Type | Liability (monthly) | Full coverage (monthly) |
|---|---|---|---|---|
1 | Just Pay-Per-Mile | Pay-per-mile | $49 | $99 |
2 | Mile Auto | Pay-per-mile | $60 | $112 |
3 | Allstate Milewise | Pay-per-mile | $79 (older data) | $125 (older data) |
4 | Just Unlimited | Flat monthly rate | $82 | $174 |
5 | Hugo | Pay-per-day | $141 | Not published |
Not rated | Lemonade Car and Nationwide SmartMiles | Pay-per-mile | No Arizona average | Get a quote |
Study A: Arizona rate data updated October 21 to 28, 2026; Milewise figures from an older review of uncertain date. Figures from different dates and programs are not directly comparable.
Two caveats matter. Study A's averages reflect the people who bought each policy, and pay-per-mile buyers tend to drive less, so Just's and Mile Auto's averages partly reflect their customers' low mileage. Also, nearly all Arizona pay-as-you-go price data comes from one source, and two strong options, Lemonade and SmartMiles, have no published Arizona averages. Treat the ranking as a starting point.
The practical takeaway: if you drive little and want the lowest likely price, get a quote from Just first, then compare Mile Auto, Lemonade, and SmartMiles, plus one standard quote. In Study A, the cheapest standard liability average was Auto-Owners at $48 a month, so a low-cost standard policy can still compete.
How much can you save with pay-per-mile in Arizona?
Savings depend almost entirely on mileage. For this hypothetical example, we compared a standard full coverage policy at $1,944 a year, Study A's Arizona average of $162 a month, with a pay-per-mile policy charging $90 a month plus 6 cents a mile. These rates are illustrations, not quotes from any company.
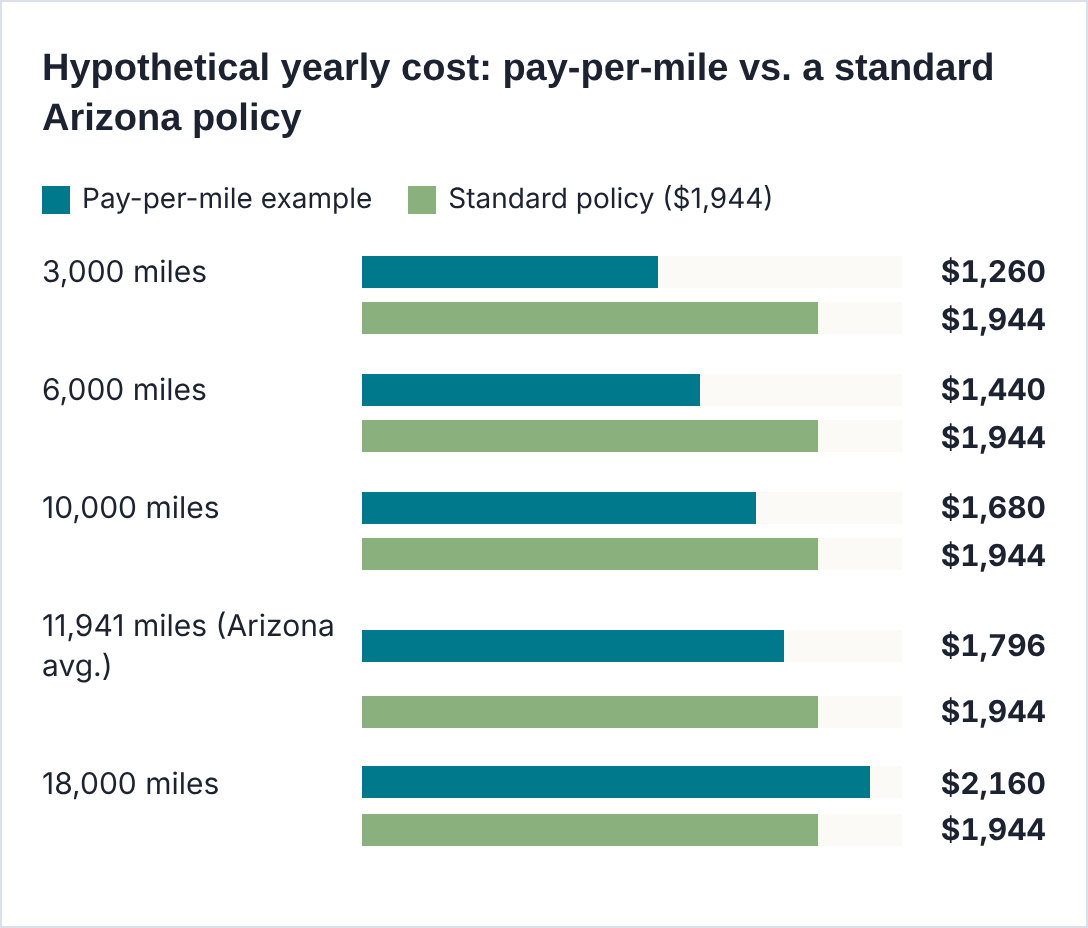
Hypothetical savings by yearly mileage (our calculation)
Miles a year | Pay-per-mile cost | vs. $1,944 standard |
|---|---|---|
3,000 | $1,260 | Saves $684 |
6,000 | $1,440 | Saves $504 |
10,000 | $1,680 | Saves $264 |
11,941 (Arizona average) | $1,796 | Saves $148 |
14,400 (break-even) | $1,944 | Even |
18,000 | $2,160 | Costs $216 more |
In this example, pay-per-mile beat the standard policy up to about 14,400 miles a year. Based on 2024 federal highway data, Arizona's licensed drivers averaged about 11,941 miles a year (our calculation), below the roughly 13,735 national figure. That means even a typical Arizona driver would have come out ahead in this example, and that retirees, remote workers, and part-year residents would save much more.
Four Arizona drivers, four results
Hypothetical Arizona drivers (our calculation)
Driver | Miles a year | Pay-per-mile cost | Result vs. $1,944 |
|---|---|---|---|
Winter visitor in Mesa, car parked in summer | 3,000 | $1,260 | Saves $684 |
Retiree in Tucson | 5,000 | $1,380 | Saves $564 |
Phoenix commuter, 15 miles each way | 12,000 | $1,800 | Saves $144 |
Flagstaff resident who drives to Phoenix often | 25,000 | $2,580 | Costs $636 more |
Hypothetical drivers using a $90 monthly base and 6 cents a mile. Real base rates vary by city, record, and car; Phoenix base rates are typically higher than Tucson's or Flagstaff's.
Snowbirds and part-year residents
Arizona's winter visitors are a natural fit. A car that sits in a Mesa or Yuma carport from May to October costs only the base rate on a pay-per-mile policy, and comprehensive coverage stays in place for monsoon damage or theft. Owners who will not drive a car for months can also consider Arizona's de-insurance option, explained below, but must not drive the car until it is insured again.
When a standard policy is the better deal
If you drive more than about 14,000 miles a year, commute long distances, or qualify for a low standard rate from an insurer such as Auto-Owners, Travelers, or Progressive, a standard policy with a safe-driving discount will often cost less. The same goes for drivers with the Valley's longest commutes, such as Buckeye or Queen Creek to central Phoenix.
What Arizona car insurance costs without pay-as-you-go
To judge any pay-as-you-go quote, compare it with standard prices. Rate studies vary widely, so we name each one. Study A, based on user quotes, found Arizona averages of $91 a month for liability and $162 for full coverage. Study B, a national rate study that prices a 30-year-old man with good credit, found $90 for minimum coverage and $236 for full coverage. A separate analysis of policies actually sold put full coverage at $210 a month.
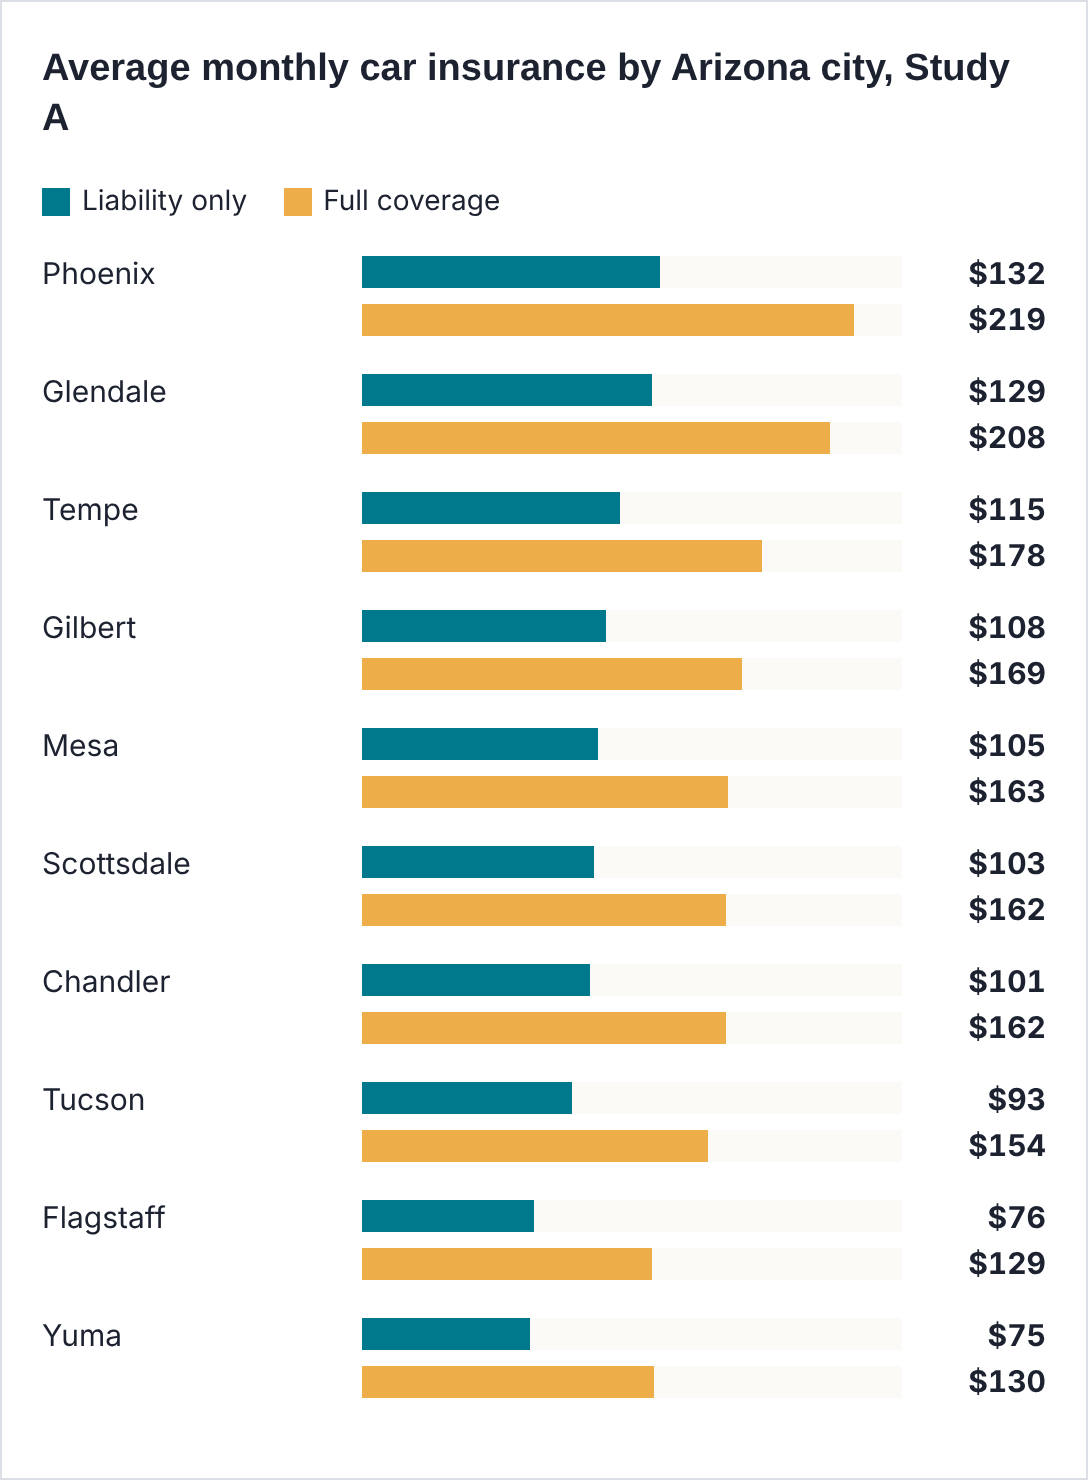
Phoenix drivers pay the most, at $132 a month for liability in Study A, while drivers in Flagstaff and Yuma pay about $75. Because pay-per-mile base rates follow the same ZIP code pattern, Phoenix-area drivers with short commutes often see the biggest dollar savings from switching.
Cheapest standard insurers in Arizona by driver type
Driver | Cheapest company | Monthly price | Study |
|---|---|---|---|
Minimum coverage | Travelers | $45 | Study C |
Full coverage | Travelers | $138 | Study C |
Age 20, full coverage | Travelers | $240 | Study C |
Age 70, full coverage | Travelers | $129 | Study C |
After an at-fault accident | Travelers | $185 | Study C |
After a DUI | Travelers | $198 | Study C |
Poor credit | Travelers | $208 | Study C |
Study C: national rate study updated November 2, 2026; 35-year-old driver, 12,000 miles a year. GEICO tied Travelers for minimum coverage at $45.
Prices have moved in both directions. One rate tracker found Arizona full coverage rose about 16% in 2024, fell 7% in 2025, and rose 3% in the first half of 2026, for a 54% increase from January 2021 to March 2026. That history is a good reason to recheck your price each renewal, whether you choose pay-per-mile or a standard policy.
Arizona law: insurance, lapses, and de-insuring a car
Arizona Revised Statutes Section 28-4135 requires insurance on a vehicle operated on Arizona roads, and you can show proof on your phone. Arizona also tracks coverage electronically. Insurers report new policies, cancellations, and nonrenewals to the Motor Vehicle Division, and a 2017 state release said they have seven days to report changes.
If your coverage ends on a registered car, the MVD mails a notice, and you have 15 days to show proof of insurance. If you do not, your registration and plate are suspended. To clear the suspension, you either prove you had coverage on the date in question or pay a $50 reinstatement fee per vehicle and show current insurance.
Arizona car insurance rules every pay-as-you-go driver should know
Rule | Details |
|---|---|
Minimum liability | $25,000 per person; $50,000 per accident for injuries; $15,000 property damage (25/50/15), since July 1, 2020 |
Uninsured and underinsured motorist | Insurers must offer it in writing; you can decline it |
Lapse on a registered car | MVD notice, 15 days to respond, then registration suspended |
Reinstatement | $50 per vehicle plus proof of current insurance |
De-insured vehicle | Not suspended for lack of insurance unless it is driven |
SR-22 | Required for 3 years after a no-insurance suspension |
Arizona Department of Insurance and Financial Institutions; ADOT FAQs; Arizona Revised Statutes Sections 28-4135 and 28-4149 (accessed November 13, 2026).
The de-insurance option is unusual and useful. According to ADOT, a vehicle you de-insure online through AZ MVD Now "will not be suspended due to lack of insurance unless it is driven on Arizona roads." That gives owners of stored or seasonal cars a legal way to stop paying for liability coverage. Never drive a de-insured car, and consider keeping comprehensive-only coverage if your insurer offers it, since theft and monsoon damage can happen to a parked car.
Uninsured drivers are less common in Arizona than in most states. The Insurance Research Council estimated that 10.6% of Arizona drivers were uninsured in 2023, below the 15.4% national rate. Still, uninsured motorist coverage is inexpensive and protects you from the one-in-ten driver who has none, so think twice before declining it.
PRO TIP #1
Before you de-insure a car or switch policies, check the start date of the new coverage and the end date of the old one. If a registered car shows a gap in MVD's records, you can face a suspension notice and a $50 reinstatement fee even if you never drove it.
Safe-driving discounts in Arizona
If pay-per-mile does not fit, usage-based programs reward careful driving at any mileage. Arizona has a wide menu, including mileage-based options from big insurers that work like a lighter version of pay-per-mile.
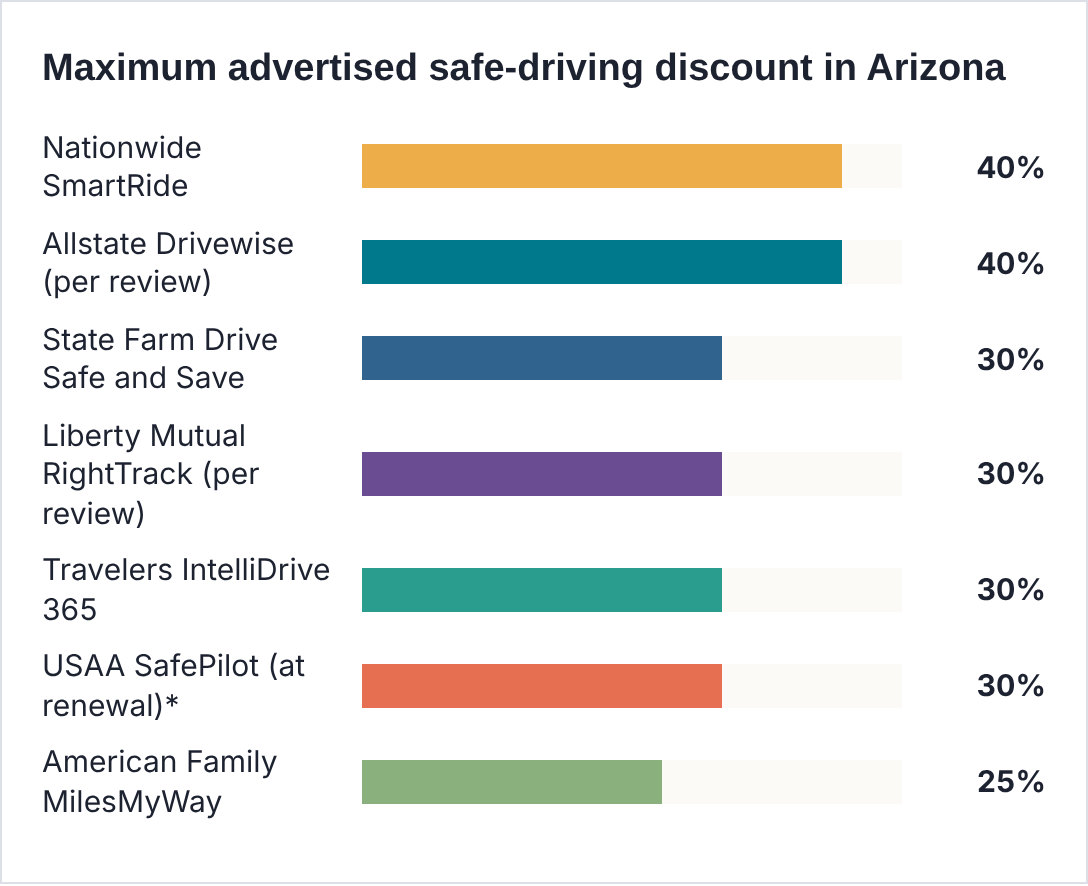
Telematics programs available to Arizona drivers
Program | Maximum savings | Can your rate go up? |
|---|---|---|
Nationwide SmartRide | Up to 40% | No, according to Nationwide |
Allstate Drivewise | Up to 40%, plus up to 10% to enroll (per review) | Yes, for risky driving |
State Farm Drive Safe and Save | Up to 30% | Recalculated at each renewal |
Travelers IntelliDrive 365 | Up to 30%; up to 10% to enroll | Yes, in most states |
Liberty Mutual RightTrack | Up to 30%; about 5% to enroll | Not for driving, per review |
USAA SafePilot* | Up to 30% at renewal; enrollment discount not offered in Arizona | Yes, on some newer policies |
American Family MilesMyWay | Up to 25% for 20 miles a day or less; 10% to enroll | Yes, above 8,000 miles a year |
Progressive Snapshot | Average $328 at renewal | Yes, for about 2 in 10 drivers |
GEICO DriveEasy | Not published | Yes |
Company pages and 2025 to 2026 reviews (accessed November 13, 2026). HiRoad, a State Farm-owned app insurer sold in Arizona, advertises up to 50% off the variable part of its premium. *USAA is available only to military members, veterans, and their families.
Pay-per-mile vs. telematics vs. a low-mileage program
Three ways Arizona drivers can pay less
Feature | Pay-per-mile | Behavior telematics | Low-mileage program |
|---|---|---|---|
What lowers your bill | Fewer miles | Safe driving habits | Staying under a mileage limit |
Best for | Under about 12,000 miles a year | Careful drivers at any mileage | Drivers under 8,000 miles a year |
Arizona examples | Just, Mile Auto, Lemonade, SmartMiles | SmartRide, Drivewise, Snapshot | American Family MilesMyWay |
Bill changes monthly? | Yes | No; set at renewal | No |
Who benefits from pay as you go car insurance in Arizona
Is pay-as-you-go right for you?
Driver | Good fit? | Best option |
|---|---|---|
Snowbird or part-year resident | Yes | Just, Mile Auto, or SmartMiles |
Retiree under 6,000 miles a year | Yes | Just or Mile Auto |
Remote or hybrid worker in the Valley | Yes | Just, Lemonade, or SmartMiles |
Tesla owner who uses Full Self-Driving | Yes | Lemonade Car |
Household with a rarely used second car | Yes | Pay-per-mile on the second car |
Long-distance commuter | No | Standard policy plus telematics |
Military family | Yes | USAA SafePilot Miles* |
Pros and cons of pay as you go car insurance in Arizona
Pros and cons
Pros | Cons |
|---|---|
More pay-per-mile choices than almost any state | Long commutes can erase the savings |
Arizonans drive less than the national average | Bills change month to month |
Just and Mile Auto posted the lowest Arizona averages | Odometer photos, apps, or devices required |
De-insurance option for stored cars | Lapses on registered cars bring MVD notices |
Works with full coverage for financed cars | Little published price data for Lemonade and SmartMiles |
Privacy: device, app, or photo?
Odometer-photo programs such as Mile Auto collect the least data, while Just pairs photos with an app that scores your driving. Device and app programs, including SmartMiles, Milewise, and Lemonade, may record speed, braking, and location even when your price is based mainly on miles. Ask what is collected, how long it is kept, and whether it is shared.
Road trips and out-of-state driving
Arizona road trips add up fast: Phoenix to Los Angeles is about 370 miles, and Phoenix to the Grand Canyon's South Rim is about 230. SmartMiles counts only the first 250 miles a day, and Metromile uses a similar cap, but not every program publishes one. Check the cap before a long drive, and remember that Just's pay-per-mile plan is aimed at drivers under 1,000 miles a month.
Full coverage, loans, and leases
Pay-per-mile policies can include collision and comprehensive, so they work for financed and leased cars. Comprehensive matters in Arizona, where monsoon hail, dust storms, and windshield damage are common, so check your deductibles and glass coverage before you switch.
How to switch without a gap
Start the new policy before you cancel the old one, and confirm the new insurer has reported it to the MVD. Because Arizona flags coverage gaps on registered cars, even a few days without coverage can trigger a suspension notice.
How to get the best pay as you go car insurance in Arizona
- Check your real annual mileage using two odometer readings or service records.
- Get a Just quote, since it posted the lowest pay-as-you-go average in Arizona.
- Get quotes from Mile Auto, Lemonade, and Nationwide SmartMiles with the same coverage.
- Get one standard quote from a low-cost insurer such as Auto-Owners, Travelers, or Progressive.
- Compare the total yearly cost, including base rate, per-mile charges, and fees.
- Ask about daily mileage caps and what happens if a photo or device report is missed.
- Start the new policy before canceling the old one.
Questions to ask before you buy
- What are my base rate and per-mile rate, and are they fixed for the term?
- Is there a daily cap on counted miles in Arizona?
- Can my rate change because of how I drive, as in Allstate's Arizona pilot?
- How do I report miles, and what happens if I miss a report?
- Are there monthly fees beyond the base and per-mile charges?
PRO TIP #2
Track your miles for one normal month before buying, and multiply by 12. If the total is under about 12,000 miles a year, pay-per-mile is worth a quote in Arizona; if it is above 15,000, start with standard insurers and a safe-driving discount.
Best pay as you go car insurance in Arizona at a glance
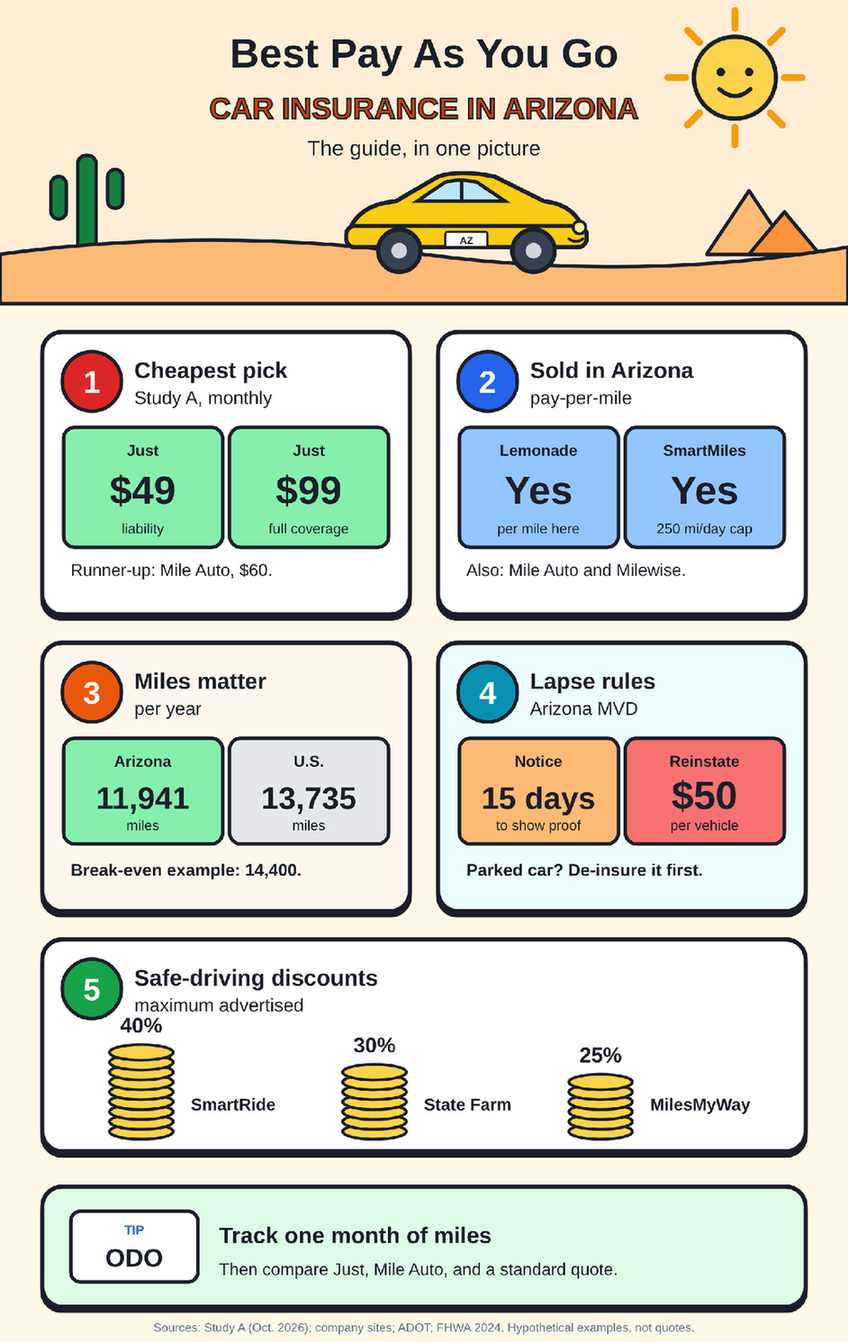
This illustrated summary pulls together the main points of this guide.
Frequently asked questions
What is the best pay as you go car insurance in Arizona?
Just Pay-Per-Mile is our top pick for most low-mileage drivers because it posted the lowest Arizona pay-as-you-go prices in Study A. Mile Auto is best if you want no app or device, Lemonade suits app-first drivers and Tesla owners, and Nationwide SmartMiles is the strongest big-name option.
What is the cheapest pay as you go car insurance company in Arizona?
Just Pay-Per-Mile. In Study A, updated October 21 to 28, 2026, it averaged $49 a month for liability and $99 for full coverage, lower than every other pay-as-you-go company in the data. Mile Auto was second, at $60 and $112.
Is pay-per-mile insurance available in Arizona?
Yes. Just Mile Auto, Lemonade Car, Allstate Milewise, Nationwide SmartMiles, and USAA SafePilot Miles all sell pay-per-mile coverage in Arizona. Arizona is one of only three states where Lemonade still prices by the mile.
How many miles make pay-per-mile worth it in Arizona?
In our hypothetical example, pay-per-mile beat a standard policy up to about 14,400 miles a year. Arizona drivers average about 11,941 miles, so many typical drivers, and most retirees, remote workers, and snowbirds, would come out ahead.
Is Metromile available in Arizona?
No. Metromile once operated in Arizona, but Lemonade bought it in 2022 and the brand is gone. Former Metromile customers moved to Lemonade, which still offers pay-per-mile coverage in Arizona.
Can I stop insuring a car I am not driving in Arizona?
Yes, if you de-insure it through AZ MVD Now first. ADOT says a de-insured vehicle will not be suspended for lack of insurance unless it is driven. If you simply let coverage lapse on a registered car, you can get a suspension notice and owe a $50 reinstatement fee.
What happens if I drive without insurance in Arizona?
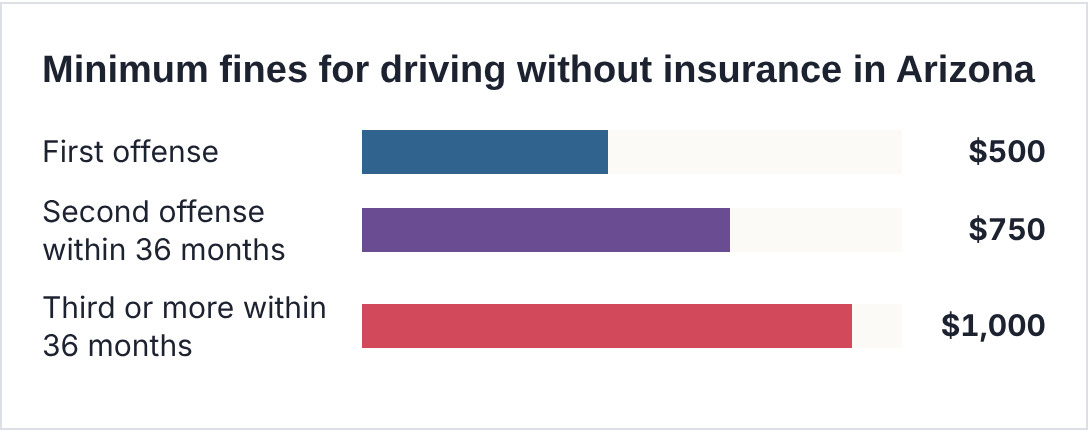
A first offense brings a fine of at least $500 and a three-month license suspension. A second offense within 36 months brings at least $750 and a six-month suspension of your license, registration, and plates, and a third brings at least $1,000 and one year. You will also need an SR-22 for three years.
What is the minimum car insurance in Arizona?
Arizona requires 25/50/15 liability: $25,000 per person and $50,000 per accident for injuries, and $15,000 for property damage. Insurers must offer uninsured and underinsured motorist coverage in writing, though you can decline it.
The final word on the best pay as you go car insurance in Arizona
The best pay as you go car insurance in Arizona starts with Just Pay-Per-Mile, which posted the lowest pay-as-you-go prices in 2026 data, at $49 a month for liability and $99 for full coverage. Mile Auto is a close second for drivers who want no app, Lemonade is a strong choice for app-first drivers and Tesla owners, and Nationwide SmartMiles and Allstate Milewise give you big-name backing.
Arizona's lower-than-average mileage makes pay-per-mile a better bet here than in most states, especially for snowbirds, retirees, and remote workers. Check your real miles, compare at least two pay-per-mile quotes with one standard quote, and choose on total yearly cost, and if a car will sit unused for months, de-insure it properly instead of letting coverage lapse.
NEXT STEP
Record your mileage for one month, then get quotes from Just, Mile Auto, and one standard insurer with the same coverage, and compare the full yearly cost before you switch.
Prices, program availability, discounts, and laws change and vary by driver, vehicle, and ZIP code. The figures in this article are published averages, official rules, and our calculations, not quotes or offers. This article is for information only and is not legal or financial advice. The publisher is not an insurance company or a licensed insurance agency.
The bottom line on the best pay as you go car insurance in Arizona: if you drive under about 12,000 miles a year, start with Just or Mile Auto; if you drive more, let a safe-driving discount do the saving.
Sources
- Insurify, Arizona car insurance, Arizona liability-only, and Arizona average cost (October 21 to 28, 2026); Insurify, Mile Auto (November 13, 2026); Insurify, Just Insure; Insurify, Milewise; Insurify, Arizona rate trends (October 21, 2026).
- Just, App Store listing; Coverager, Just pay-per-mile; FinTech Global, Just in Arizona (2020).
- NerdWallet, Lemonade review (December 23, 2025); Coverager, Lemonade Car launches in Arizona (2023); Lemonade, Arizona car insurance.
- Nationwide, SmartMiles and SmartRide; USAA, SafePilot Miles; American Family, MilesMyWay FAQ; Travelers, IntelliDrive programs (accessed October 29, 2026).
- Repairer Driven News, Allstate Arizona Milewise pilot (February 21, 2020); ValuePenguin, Drivewise review (September 25, 2026).
- Arizona DIFI, minimum coverage; ARS 28-4135 and ARS 28-4149; ADOT, clearing a registration suspension; ADOT, no-insurance FAQ.
- NerdWallet, Cheap car insurance in Arizona (November 2, 2026); ValuePenguin, Cheapest car insurance in Arizona (2026); Experian, Average cost of car insurance in Arizona (October 13, 2026).
- FHWA Highway Statistics 2024, Table VM-2 and Table DL-22; Insurance Information Institute, uninsured motorists.