
Mobile Home Insurance in Michigan: Costs, Companies & Coverage
Mobile home insurance in Michigan requires a different comparison from standard homeowners insurance. Several Michigan insurers offer policies designed for manufactured homes, but published rate studies rarely provide like-for-like quotes for these properties within the state. Foremost, Auto-Owners, Frankenmuth, Fremont and other carriers are worthwhile companies to check, depending on the home’s age, location and installation.
This guide compares ten insurers that may be relevant to Michigan manufactured-home owners, without claiming a statewide cheapest-company ranking that the public data cannot support. It also explains sample prices, Detroit and upstate weather risks, mobile-home park taxes and resident rights, options for seniors, bundling, and how to request comparable quotes.
Use home insurance quote comparison principles to check whether the quoted limits, deductibles and settlement basis match; general homeowners comparison tools may not offer manufactured-home policies in Michigan.
KEY TAKEAWAYS
- One published state table suggests about $802 per year for Michigan mobile homes, but it does not disclose a sufficient rating profile or methodology to treat that figure as a verified statewide average.
- In an out-of-state manufactured-home quote sample, Assurant ($969), American Modern ($1,025) and Foremost ($1,607) had different rates; none of those amounts is a Michigan quote.
- Foremost offers specialty manufactured-home coverage; Michigan-based Auto-Owners, Frankenmuth and Fremont also advertise manufactured- or mobile-home policies. No single insurer is demonstrably cheapest for every Michigan property.
- An occupied mobile home in a licensed park generally carries Michigan’s $3 monthly specific tax. Eligible park residents may also claim a Homestead Property Tax Credit, calculated under special rules.
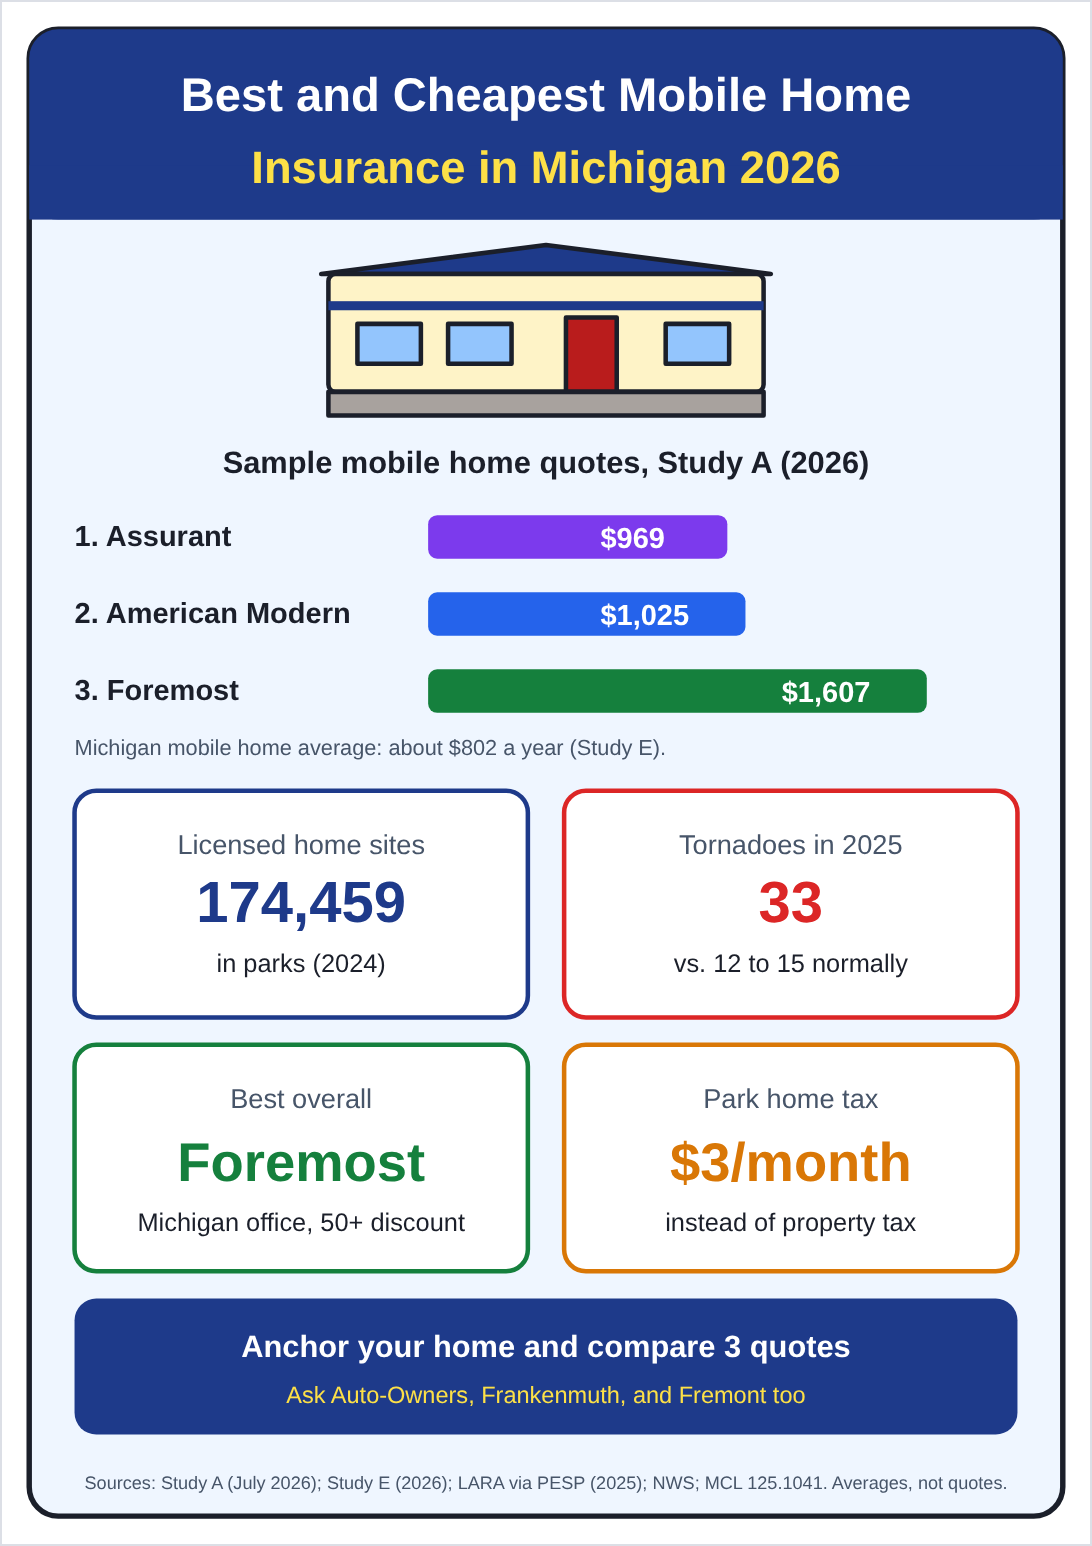
Michigan mobile home insurance at a glance. Company prices are Study A’s 2026 sample quotes, not Michigan quotes.
Image accuracy notice: prices and rankings displayed inside the original illustration refer to non-Michigan samples or editorial choices; they are not verified Michigan manufactured-home premiums.
How much mobile home insurance costs in Michigan
Publicly available Michigan-specific, like-for-like manufactured-home prices are limited. Study E lists roughly $802 annually for Michigan, but does not publish the insured dwelling profile and calculation method needed to validate it as a statewide average. Study A priced a 2016 single-wide in Austin, Indianapolis and Mesa—not in Michigan—with about $51,000 to $63,000 of dwelling coverage. The $969, $1,025 and $1,607 figures below describe that out-of-state sample only.
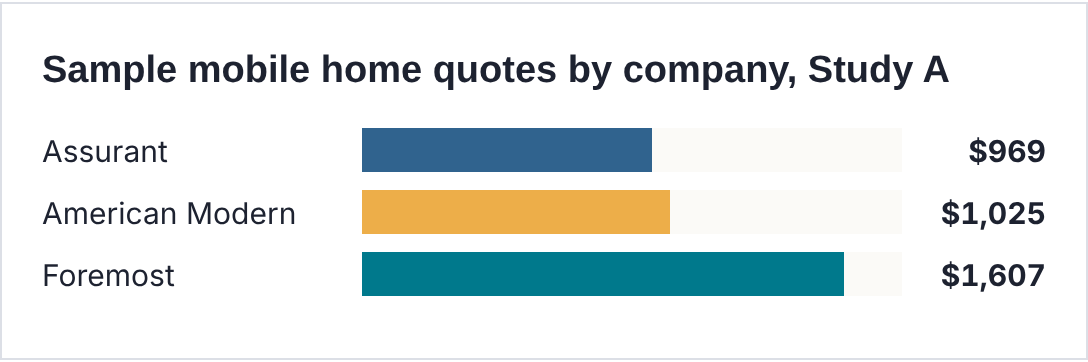
Study A: national mobile home quote study updated July 6, 2026, for a 2016 single-wide in a park in Austin, Indianapolis, and Mesa. No Michigan quotes.
Assurant was the lowest-priced carrier in that particular out-of-state sample; American Modern was $56 higher and Foremost $638 higher. Those differences cannot be projected onto Michigan because location, roof and wind risks, home value, coverages, deductibles and underwriting vary.
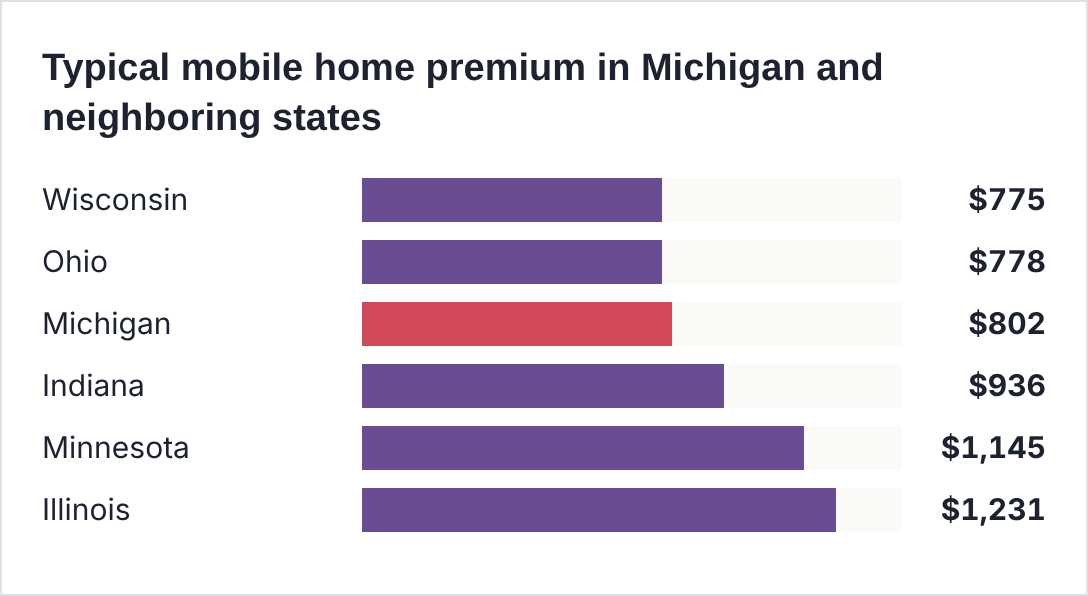
Study E national table (October 18, 2026). Method and coverage amount not published, so treat as rough estimates.
Separately, studies of conventional Michigan homeowners policies report about $1,243 per year for a $100,000 dwelling profile in Study C. A March 2026 standard-home study priced a $200,000 dwelling and reported Auto-Owners at $905, Frankenmuth at $1,155, AAA at $1,190, Fremont at $1,245 and Allstate at $1,285. None of those figures is a quote for a mobile or manufactured home. They cannot establish an insurer’s relative manufactured-home prices.
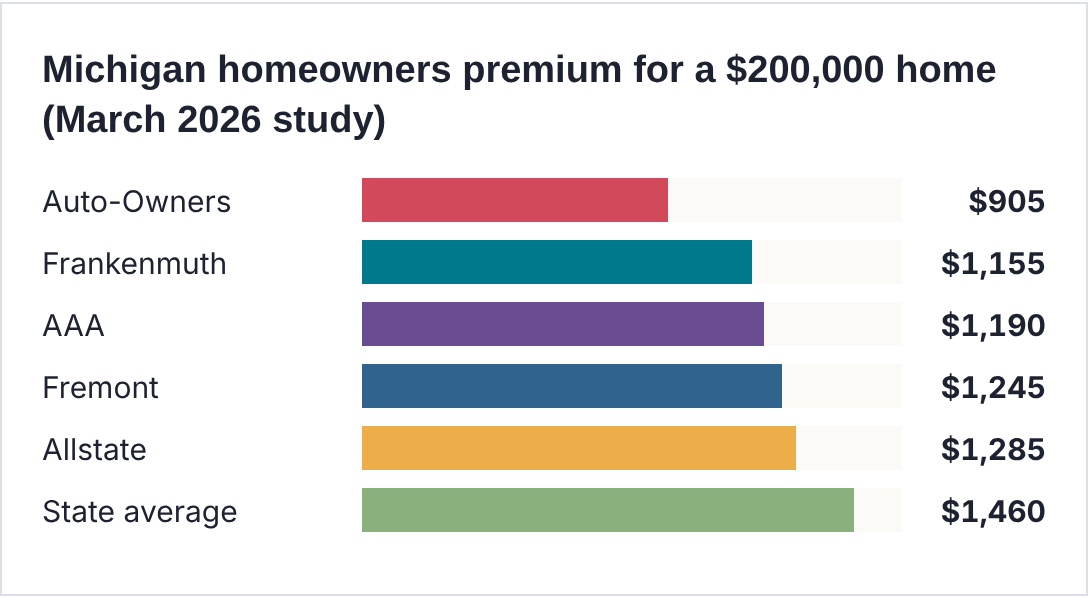
March 2026 national homeowners study, $200,000 dwelling. Standard-home policies, not mobile home policies. Averages, not quotes.
An October 2026 study of standard Michigan houses reported different prices for Farmers, Auto-Owners, Allstate and Westfield. That helps illustrate how insurers vary even for conventional properties, not what they will charge for a manufactured home. Auto-Owners separately advertises mobile-home coverage through independent agents.
Michigan mobile home insurance price evidence
| Source | Yearly cost | Notes |
|---|---|---|
| Study E, Michigan average | $802 | State table; method not published |
| Study A, Assurant | $969 | Sample single-wide, not in Michigan |
| Study A, American Modern | $1,025 | Sample single-wide, not in Michigan |
| Study A, Foremost | $1,607 | Sample single-wide, not in Michigan |
| Study C, $100,000 home | $1,243 | Michigan standard-home average |
| $200,000 home, Auto-Owners | $905 | Michigan, March 2026 study |
| $200,000 home, Farmers | $852 | Michigan, October 2026 study |
Study A (July 6, 2026); Study C (September 2026); Study E (October 18, 2026); March and October 2026 homeowners studies.
What standard Michigan homeowners pay
For context only, conventional Michigan homeowners studies report averages ranging from about $2,195 to $2,545 for their specified dwelling limits, while Study B used a $350,000 home and reported about $2,246. These conventional-house figures are not substitutes for manufactured-home quotes.
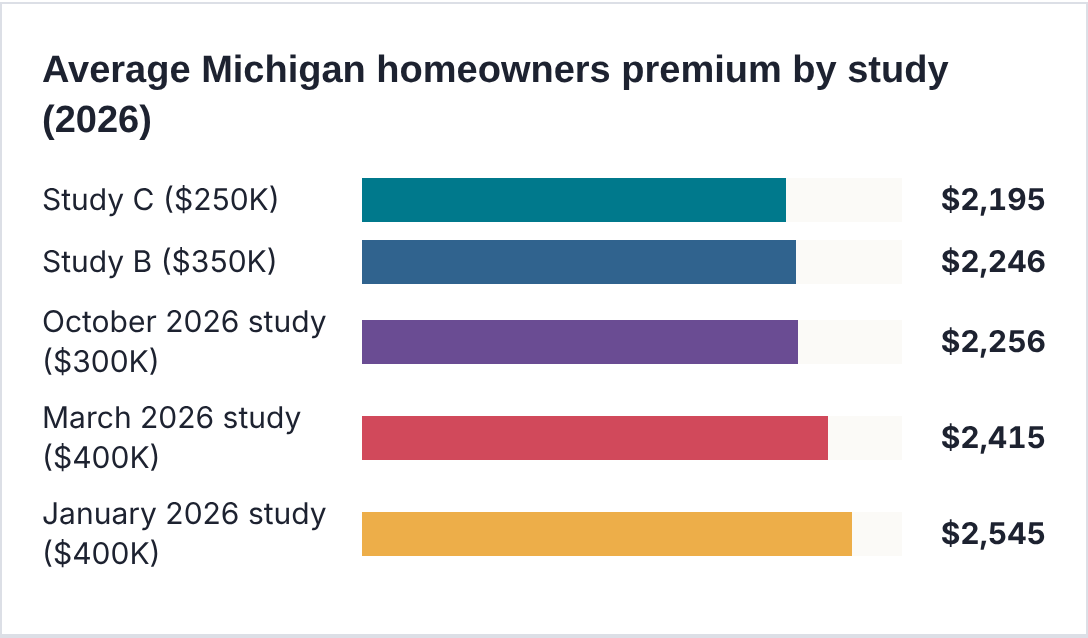
2026 Michigan homeowners studies; dwelling coverage in parentheses. Standard homes, not mobile homes.
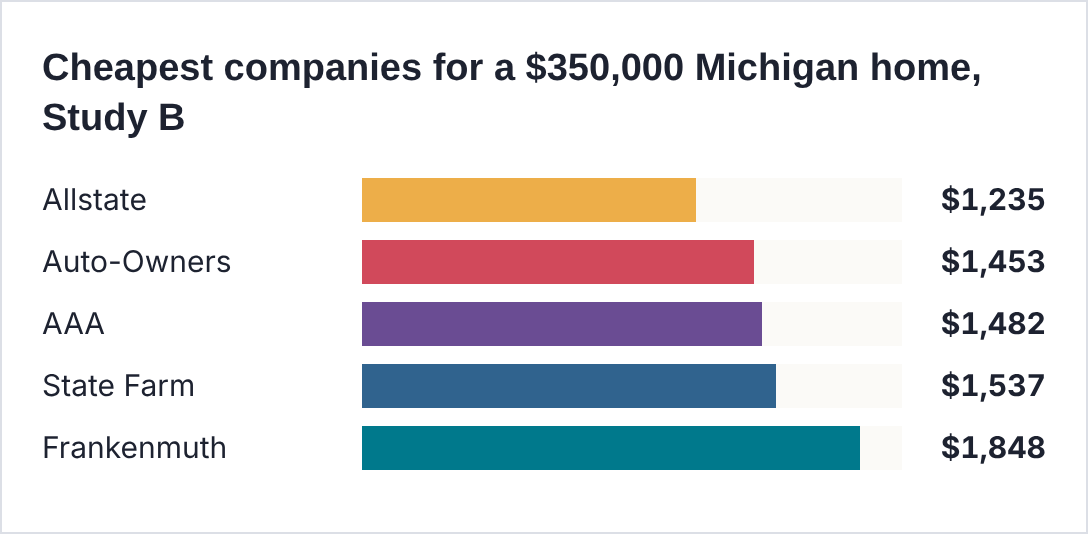
Study B, updated September 25, 2026, $350,000 dwelling. Standard homes, not mobile homes. Averages, not quotes.
Michigan mobile homes by the numbers
Michigan is one of the country’s biggest manufactured housing states. State licensing data from 2024 shows 174,459 manufactured home sites in licensed communities, and Census figures from 2022 show about 195,000 occupied mobile homes, about 5% of owner-occupied homes. The state counts somewhere between 1,032 and about 1,200 licensed communities, depending on the year and source.
Ownership has shifted fast. A 2025 analysis found that private equity firms own 192 Michigan parks with 50,626 sites, or about 29% of the state’s licensed sites, second only to Florida in total parks. That matters for insurance because new owners often raise lot rent and fees, which squeezes the budget left for coverage.
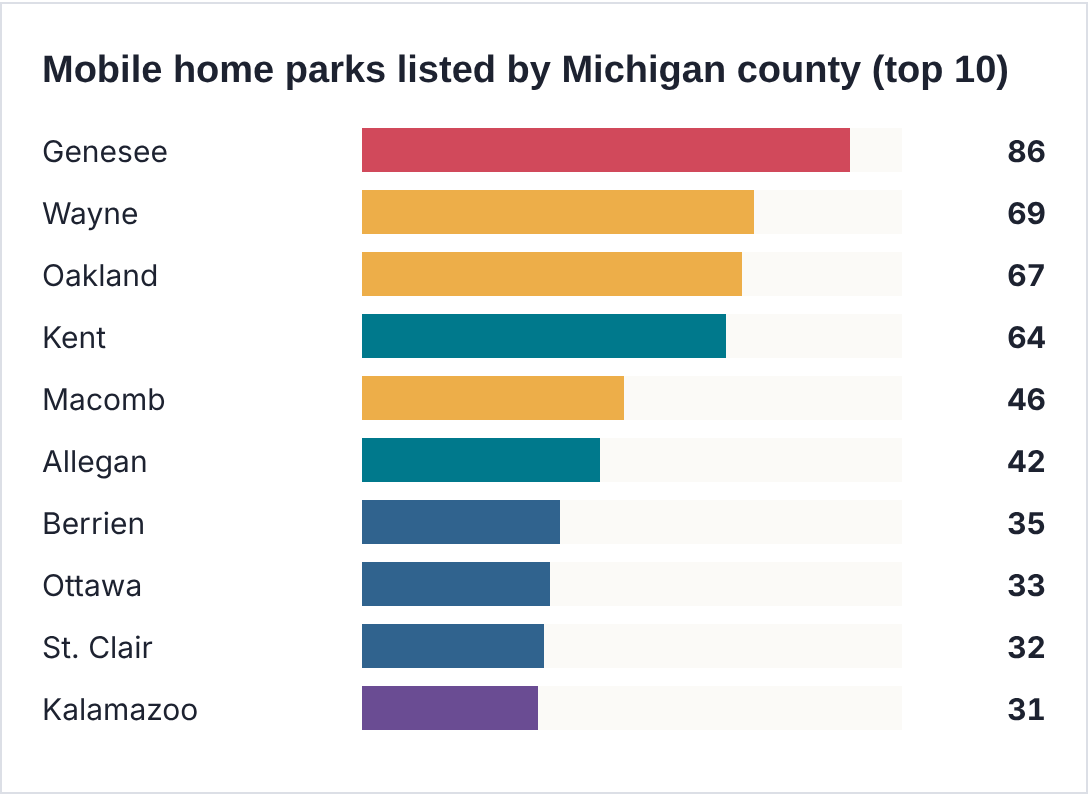
Parks listed on a national listing site, accessed October 31, 2026. Not an official state count.
Michigan manufactured housing at a glance
| Measure | Figure |
|---|---|
| Licensed manufactured home sites (2024) | 174,459 |
| Occupied mobile homes (2022 Census data) | About 195,000 |
| Licensed communities | 1,032 (2024) to about 1,200 (2026) |
| Sites owned by private equity | 50,626 (29%) |
| Average lot rent (2019) | $258 a month |
| Wind zone | Zone I statewide |
LARA data via PESP (July 2025); 2022 ACS data via NAR; Michigan Senate (April 2026); BridgeDetroit (2024); Bridge Michigan (2022); 24 CFR 3280.305.
10 mobile home insurance companies to compare in Michigan
The companies below are comparison candidates, not a price ranking. The first three have out-of-state manufactured-home sample prices. Prices shown for Auto-Owners, Frankenmuth, Fremont and Allstate come from studies of conventional Michigan homes and are not directly comparable. The final three have product or bundling information but no verified manufactured-home quote data in this comparison. Availability, eligibility and exact underwriting company must be checked individually.
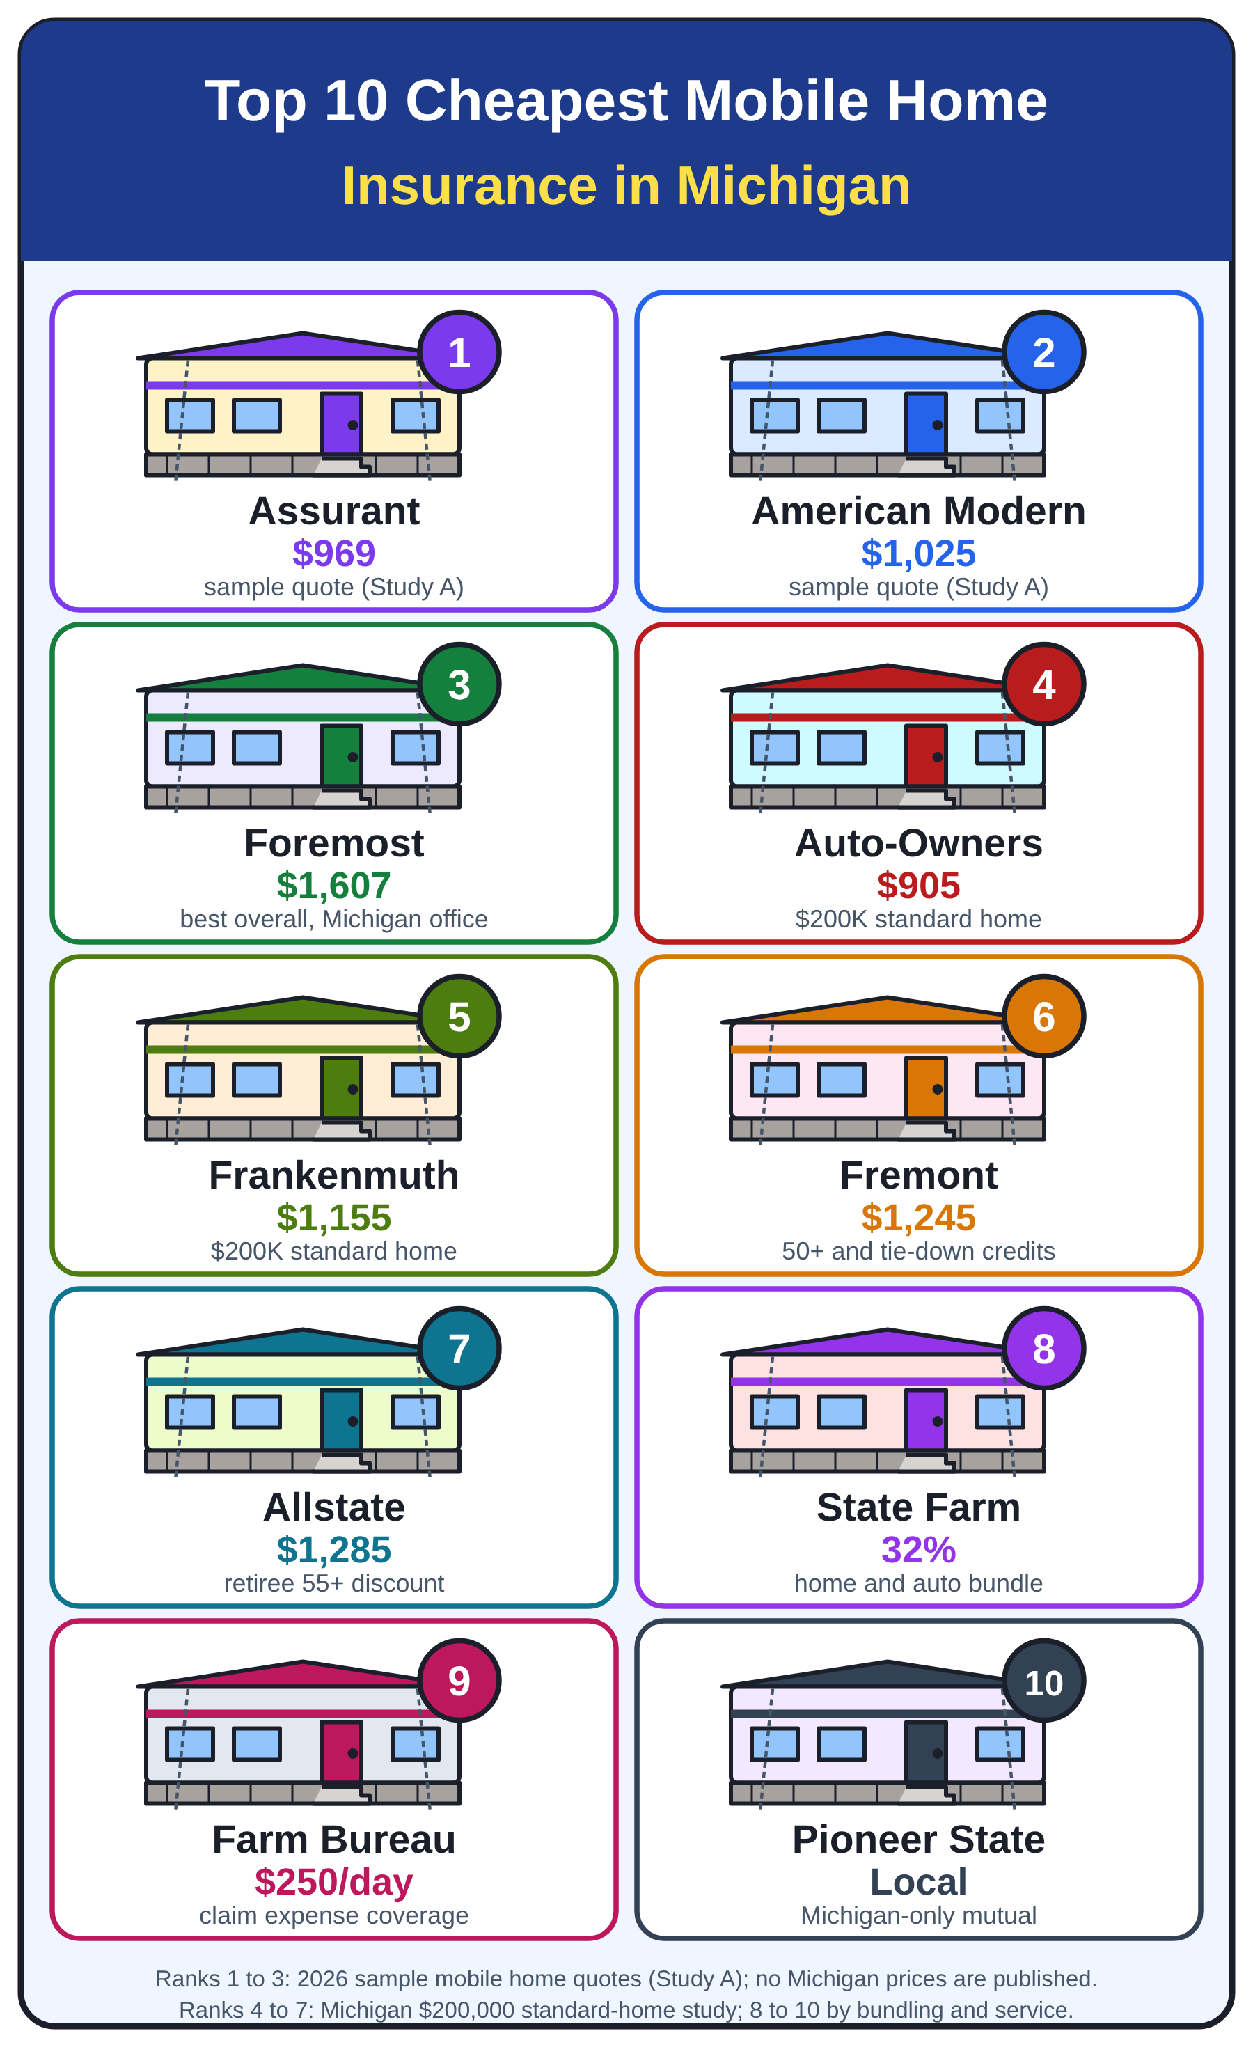
Original illustration of ten company options. Its numbered ordering is not a verified Michigan manufactured-home price ranking, and its prices come from different kinds of studies.
Image accuracy notice: the illustration is retained from the original article. Its numbers are not a valid statewide price ranking; the corrected comparison table below does not rank these insurers by cost.
10 companies to check for Michigan manufactured-home coverage
| Listed option (not a price rank) | Company | Price or evidence | Why it stands out |
|---|---|---|---|
| — | Assurant | $969 (Study A sample) | Lowest price in the out-of-state sample only |
| — | American Modern | $1,025 (Study A sample) | Homes of any age |
| — | Foremost | $1,607 (Study A sample) | Specialty manufactured-home coverage; editorial option |
| — | Auto-Owners | $905 ($200K standard home) | Michigan mobile-home policy available; $905 is conventional-home sample |
| — | Frankenmuth | $1,155 ($200K standard home) | Manufactured home endorsement |
| — | Fremont | $1,245 ($200K standard home) | 50+ and tie-down credits |
| — | Allstate | $1,285 ($200K standard home) | Retiree discount; bundle rate from standard-home study |
| — | State Farm | 32% bundle figure from standard home and auto study | Standard-home study; mobile-home bundle not verified |
| — | Michigan Farm Bureau | 11% bundle figure from standard home and auto study | Ask which claim-expense endorsements are included |
| — | Pioneer State Mutual | 15% bundle figure from standard home and auto study | Michigan-only mutual since 1908 |
Study A (July 6, 2026); March 2026 Michigan homeowners study; Study D (September 30, 2026); company websites.
Assurant: lowest quote in the out-of-state sample
Assurant was least expensive in Study A’s non-Michigan sample, at $969 annually; this does not demonstrate the lowest price in Michigan. Confirm the licensed issuing company and whether a given quote includes replacement cost, water damage and wind/hail coverage. A 2025 national complaint index reported by a secondary review is not a Michigan manufactured-home claims score.
American Modern: low price, broad eligibility
American Modern averaged $1,025 annually in Study A’s out-of-state manufactured-home sample, $56 above Assurant in that sample only. Its specialty product can be considered for older properties, but availability, settlement terms and eligibility depend on the specific policy and underwriting company.
Foremost: established specialty manufactured-home carrier
Foremost has specialized in mobile-home coverage since the 1950s and is part of Farmers Insurance Group. It advertises policies for a broad range of manufactured homes and provides a practical comparison option in Michigan. Its $1,607 Study A amount came from homes outside Michigan. Discounts, settlement valuation and limits vary by actual contract; a national complaint ratio cited by a secondary review is not proof of superior Michigan claim handling.
Auto-Owners: Michigan mobile-home specialist to quote
Lansing-based Auto-Owners publishes mobile-home coverage through independent agents. Its quoted $905 March-study figure and $864 October-study figure, however, are for conventional Michigan houses, not mobile homes. For the automotive side of a possible bundle, the Auto-Owners auto insurance overview (in Spanish) covers its car products, not mobile-home pricing. Ask an agent about actual- versus replacement-cost settlement, water backup, deductibles and coverage for outbuildings before judging value.
Frankenmuth: local agents, flexible coverage
Frankenmuth Insurance’s $1,155 figure in the March study priced a standard Michigan home, not a manufactured home. Frankenmuth independently confirms that its Michigan manufactured-home program can cover dwellings in parks or on private land, with optional contents replacement cost, sewer or drain backup and loss assessment. Confirm the endorsements in your quote.
Fremont: Michigan mobile-home insurer with discount options
Michigan-based Fremont Insurance advertises a dedicated mobile-homeowners product. Its $1,245 figure from the March study instead reflects a conventional house. Ask a Fremont agent which age, tie-down, non-smoker, protective-device and multi-policy credits currently apply in your county; advertised discounts are not guaranteed for every policy.
Allstate: best for retirees
Allstate’s $1,285 March-study and $1,235 Study B figures came from conventional houses. It also advertises manufactured-home coverage, with eligibility and discounts varying by location. The Allstate insurance overview (in Spanish) discusses the insurer more broadly. A quoted auto/home discount from a conventional-home study should not be presented as a Michigan mobile-home bundle discount.
State Farm: biggest bundle discount
State Farm advertises manufactured-home policies for qualifying properties. A reported 32% bundling figure from Study D describes the study’s standard homeowners and auto scenario, not a guaranteed manufactured-home discount. Request bundled and separate quotes at the same limits, and confirm whether your particular dwelling qualifies for replacement-cost coverage.
Michigan Farm Bureau: generous extras
Michigan Farm Bureau advertises mobile-homeowners coverage for eligible members. Some product descriptions mention claim-related expenses and discounts for qualifying properties; ask your agent for the applicable endorsement, daily limits, conditions and any membership fees instead of assuming a $250-per-day benefit applies to every policy.
Pioneer State Mutual: Michigan-only mutual
Pioneer State Mutual is a Michigan insurer that lists mobile-home coverage. Its product information describes optional coverages and possible discounts. Study D’s bundling percentage comes from conventional homeowners policies, so obtain a separate mobile-home-specific quote rather than assuming the same rate reduction.
PRO TIP #1
Many brands, including Progressive, GEICO, and USAA, place mobile home policies with Foremost, American Modern, or Assurant. To get truly different prices, include at least one Michigan insurer, such as Auto-Owners, Frankenmuth, or Fremont, through a local independent agent.
Companies not on our list
AAA was competitively priced for standard Michigan homes in one study, but its manufactured-home eligibility was not established by those prices. Also verify whether any national brand is the issuing company or only a distribution partner for a specialty insurer; the underwriting company is responsible for claims. Availability can change by location and home type.
Can we identify the cheapest mobile home insurer in Michigan?
No published evidence reviewed here identifies a cheapest manufactured-home insurer for Michigan on a like-for-like basis. Assurant was cheapest only in Study A’s out-of-state sample, at $969. Auto-Owners’ $905 quote in the March study applied to a conventional $200,000 Michigan house. Foremost is an editorial starting point for specialist coverage, not an objectively verified statewide winner.
Request at least three Michigan manufactured-home quotes using the same street address, construction year, dimensions, insured dwelling value, roof information, replacement-cost or actual-cash-value basis, liability limit and deductibles. Include a specialist such as Foremost or American Modern and at least one Michigan carrier such as Auto-Owners, Frankenmuth or Fremont if the home is eligible. Compare the actual underlying insurance companies, not merely the websites selling the policies.
Michigan mobile home insurers to consider by need
Michigan manufactured-home insurer options by need
| Need | Best pick | Why |
|---|---|---|
| Lowest price in the out-of-state sample only | Assurant | $969; out-of-state sample |
| Older homes | American Modern | Insures homes of any age |
| Specialist coverage | Foremost | National complaint indicator; confirm discount and policy terms |
| Michigan insurer | Auto-Owners | $905 applies to a standard house |
| Tie-down credit | Fremont | Tie-down and 50+ discounts |
| Retirees 55+ | Allstate | Retiree discount; bundle rate from standard-home study |
| Compare bundled prices | State Farm | 32% in conventional-home study |
| Check contract benefits | Michigan Farm Bureau | Ask which claim-expense endorsements are included |
Our assessment, based on Study A, Study D, a March 2026 Michigan homeowners study, and company information.
Cheapest mobile home insurance for seniors in Michigan
Drivers and homeowners over age 50 can ask Foremost and Fremont whether an age-based manufactured-home discount is currently available; Allstate may offer a discount for eligible retired homeowners over 55. Eligibility, policy form and savings differ by company. None of these credits proves that a carrier is cheapest for seniors in Michigan.
Senior and mature discounts in Michigan
| Company | Starting age | Notes |
|---|---|---|
| Foremost | 50 | Named insured age 50 or older |
| Fremont | 50 | Plus tie-down and non-smoker credits |
| Allstate | 55 | Must be retired |
| Pioneer State Mutual | Not stated | Mature homeowner discount |
| Michigan Farm Bureau | 30 | Mature insured discount; membership required |
Company websites (2026). Discount amounts vary.
Tax treatment is separate from insurance pricing. Occupied homes in licensed Michigan parks generally carry a $3 monthly specific tax. Some residents may qualify for the Homestead Property Tax Credit on eligible lot rent; that credit depends on total household resources, tax year and Michigan Treasury rules, not solely on age.
PRO TIP #2
If you are 50 or older, ask Foremost and Fremont for their senior discounts, and if you are retired and over 55, ask Allstate. Then file the Homestead Property Tax Credit with your Michigan return to get back part of your lot rent.
Detroit mobile home insurance
Detroit is the most expensive place to insure a home in Michigan. Average homeowners premiums in Detroit ran from $2,592 to $6,931 in 2026 studies, roughly double the state average, and Allstate was the cheapest company in Detroit in Study B, at $1,985. Wayne County has 69 mobile home parks on a national listing site, mostly in suburbs such as Romulus, Belleville, Taylor, and Canton, and neighboring Oakland and Macomb counties add 113 more.
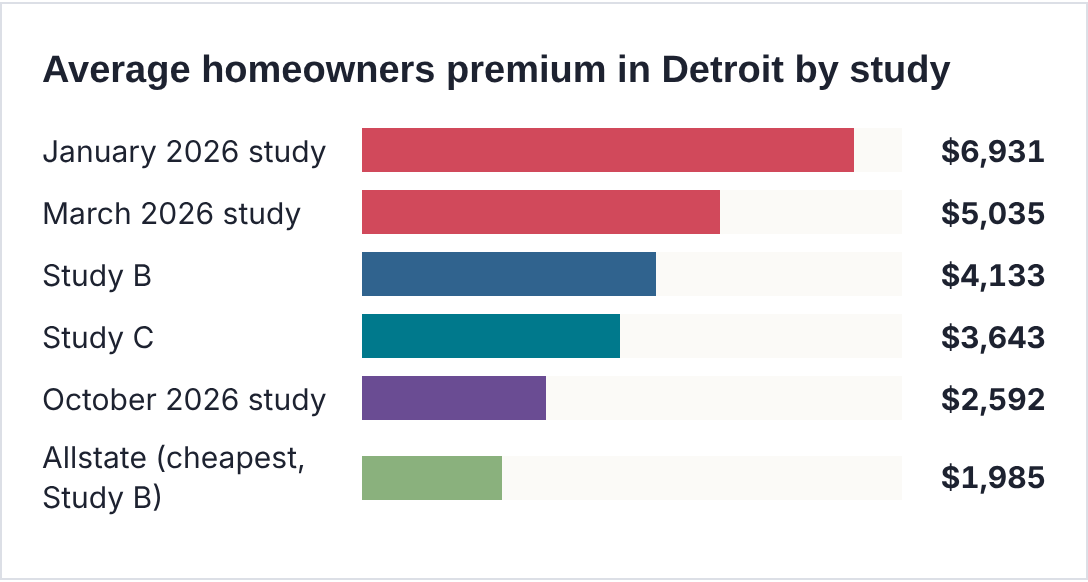
2026 Michigan homeowners studies; coverage amounts vary from $250,000 to $400,000. Standard homes, not mobile homes. Averages, not quotes.
Flooding is Detroit’s biggest risk
Typical mobile-home policies exclude surface flooding, and sewer or drain backup frequently requires separate coverage. Ask about an NFIP or private flood policy even outside a mapped high-risk zone. Flood insurance for qualifying anchored manufactured homes can provide up to $250,000 in building coverage and $100,000 for contents under an NFIP residential policy; a waiting period generally applies, with exceptions.
Detroit-area mobile home insurance checklist
| Risk | What to check |
|---|---|
| Flash flooding | Separate flood policy; 30-day wait |
| Sewer backup | Sewer and drain backup add-on |
| Severe storms | Wind coverage and tie-downs |
| Theft and vandalism | Theft limits and alarm discounts |
| High premiums | Compare at least three insurers |
Our assessment, based on BridgeDetroit, Michigan Advance, and insurer information.
Grand Rapids mobile home insurance
Grand Rapids is one of the cheaper big cities in Michigan, with average homeowners premiums of $1,690 to $2,940 in 2026 studies. Kent County has 64 mobile home parks on a national listing site, and nearby Ottawa and Allegan counties add 75 more. Foremost’s Michigan home office is in nearby Caledonia, and West Michigan has strong local agent networks for Auto-Owners, Frankenmuth, and Fremont.
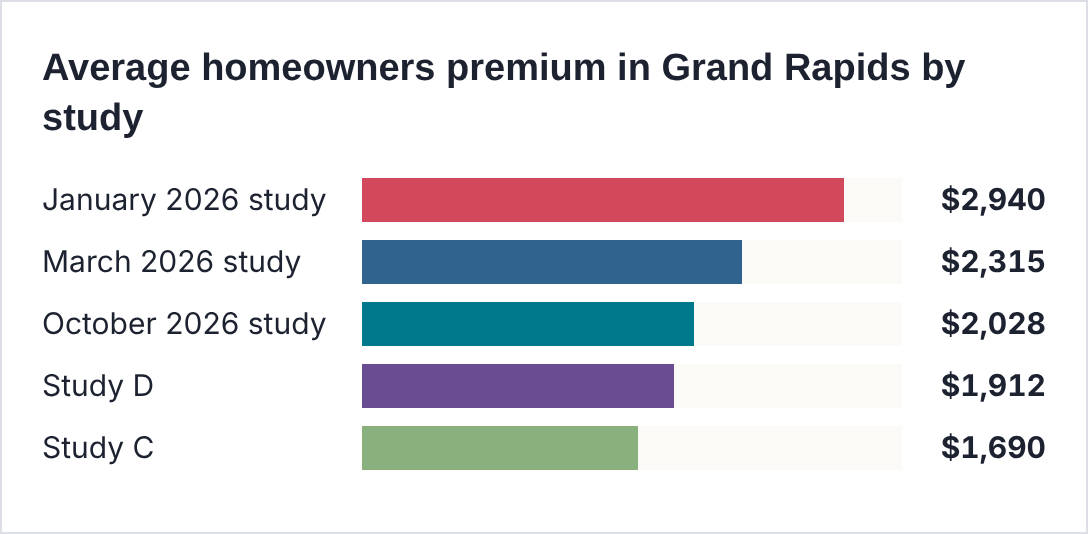
2026 Michigan homeowners studies. Standard homes, not mobile homes. Averages, not quotes.
West Michigan’s main risks are severe storms, tornadoes, and lake-effect snow. Most of the area, including Kent County, is in HUD’s south roof-load zone, rated for 20 pounds per square foot, so clear heavy snow from the roof when it is safe and make sure your policy covers roof collapse and frozen pipes.
Lansing mobile home insurance
Lansing homeowners paid average premiums of $1,675 to $2,929 in 2026 studies, close to the state average. Lansing is also home to Auto-Owners, Michigan’s cheapest insurer in the March 2026 study, and to the state agencies that license parks and handle insurance complaints.
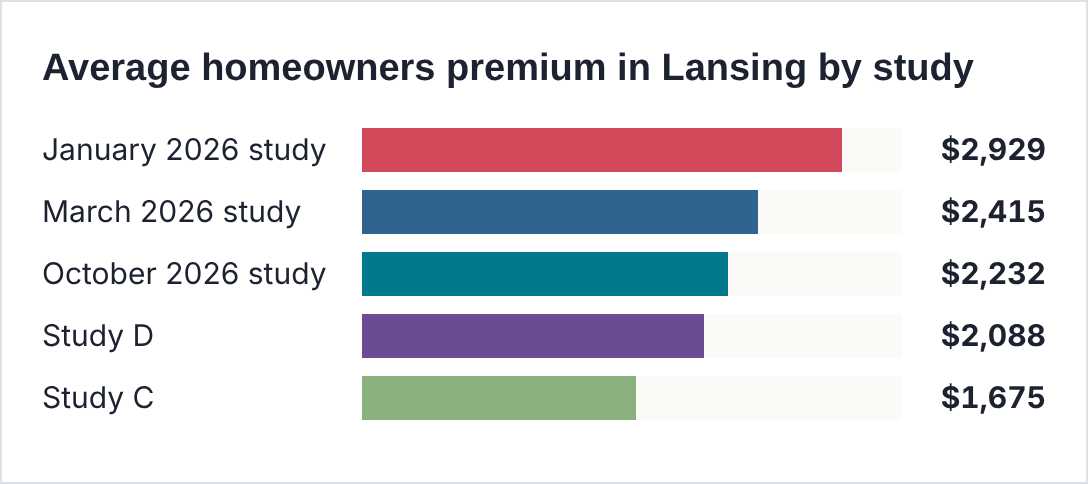
2026 Michigan homeowners studies. Standard homes, not mobile homes. Averages, not quotes.
In 2025, residents of Kristana Estates in DeWitt Township, just north of Lansing, were given four days to move out, and their water was shut off the day after the deadline until a judge ordered it restored. Cases like this one helped drive the 2026 park reform bills described later in this guide.
Flint and Genesee County mobile home insurance
Genesee County has more mobile home parks than any other Michigan county on a national listing site, with 86. Flint is also one of the state’s most expensive places to insure a home, with average premiums of $2,508 to $5,333 in 2026 studies.
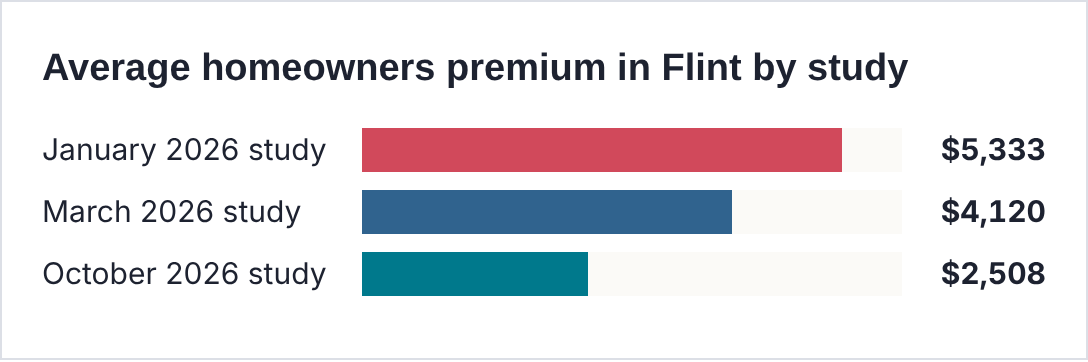
2026 Michigan homeowners studies. Standard homes, not mobile homes. Averages, not quotes.
Lot rent is a big issue in the area. At South Valley Estates in Swartz Creek, lot rent rose from about $300 a month in 2018 to $432 in 2022, a 44% jump (our calculation), and at Swartz Creek Estates, rent and new fees raised resident costs by about 40% after a 2018 sale. When housing costs rise, keep your insurance in place, and shop for a cheaper policy instead of letting coverage lapse.
Kalamazoo and Portage mobile home insurance
Kalamazoo homeowners paid average premiums of $2,420 to $3,023 in 2026 studies, and Kalamazoo County has 31 mobile home parks on a national listing site. The area is best known among mobile home owners for one storm. On May 7, 2024, an EF2 tornado with winds of 135 mph, just 1 mph short of EF3, cut an 11-mile path through Portage and Pavilion Township.
The tornado hit Pavilion Estates mobile home park hardest. Early reports counted about 176 homes damaged and 15 to 17 destroyed in the park, and county officials counted 24 mobile homes destroyed near Portage. Remarkably, no one died, and most injuries were minor, but a year later the county was still rebuilding.
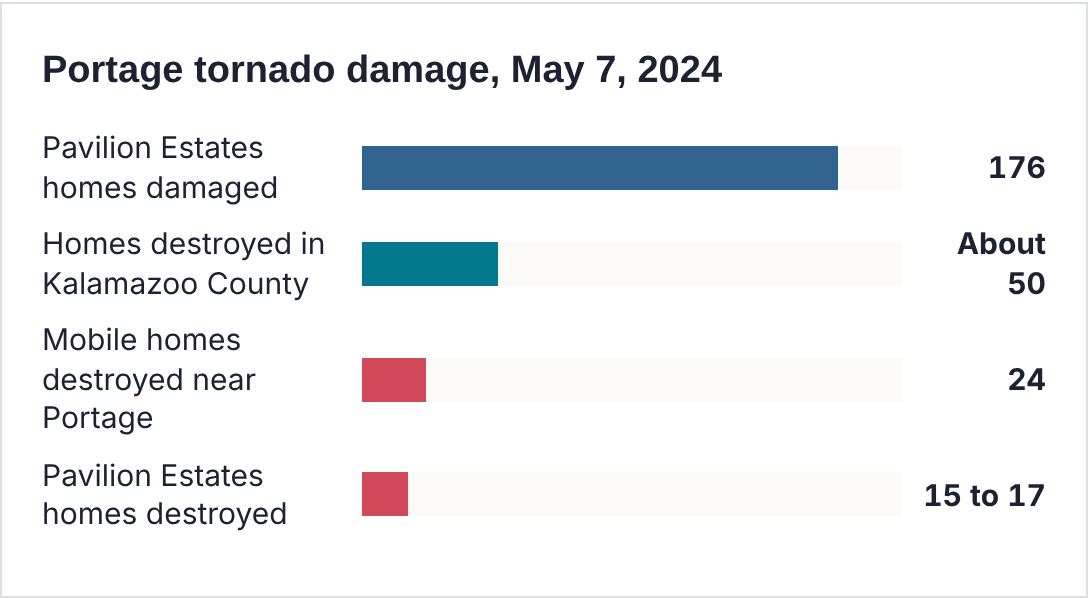
Fox 2 Detroit (May 8, 2024); Michigan Public (May 14, 2024). Early counts; later figures differ.
Portage showed why insurance details matter. Owners with replacement cost coverage, enough loss of use coverage for months in a rental, and debris removal coverage recovered faster than those with bare-bones policies. Check all three before the next storm.
Northern Michigan and Upper Peninsula mobile home insurance
Northern Michigan is cheaper to insure in normal years, and Traverse City had the lowest average homeowners premium of any Michigan city in Study B, at $1,591. But the north faces heavier snow, ice storms, and some of the state’s deadliest mobile home tornadoes.
The Gaylord tornado
On May 20, 2022, an EF3 tornado with winds of about 140 mph tore through Gaylord. It crossed the Nottingham Forest mobile home park in about three minutes, killing two residents in their 70s, injuring more than 40 people, and leaving the park about 95% destroyed, according to the Otsego County fire chief.
The 2025 ice storm
From March 28 to 30, 2025, an ice storm coated 13 northern counties, including Otsego, Cheboygan, Emmet, Alpena, and Presque Isle, causing long power outages and record damage to power lines and trees. A federal disaster declaration covered public repairs, but FEMA denied aid to individual homeowners, even on appeal. That left owners to rely on their own insurance for fallen trees, roof damage, and frozen pipes.
Heavier snow loads
Snow is the north’s constant risk. Keweenaw County recorded about 301 inches of snow in the 2024-25 season. Under HUD rules, 34 Michigan counties, including all 15 Upper Peninsula counties and the northern Lower Peninsula, are in the middle roof-load zone, so homes there must be built for 30 pounds per square foot. The rest of the state is in the south zone, rated for 20.
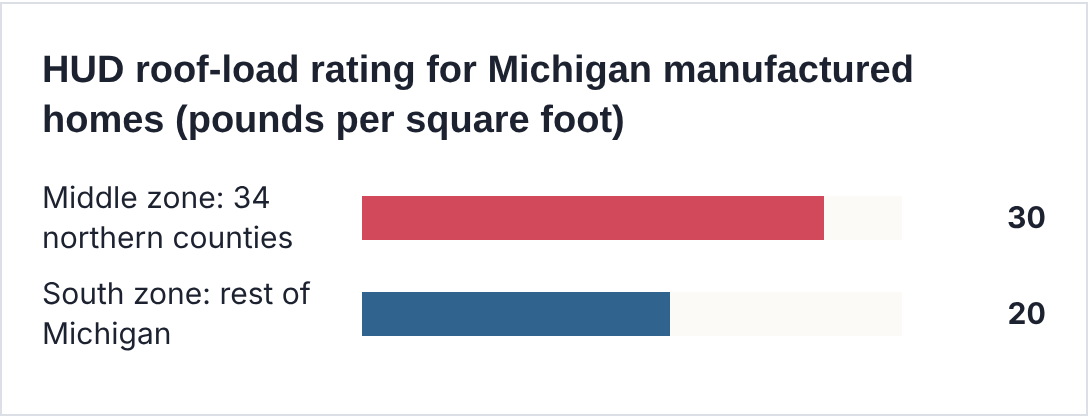
24 CFR 3280.305. No Michigan county is in the north (40 psf) zone. All of Michigan is Wind Zone I.
Northern Michigan mobile home insurance checklist
| Risk | What to check |
|---|---|
| Heavy snow | Roof collapse coverage; 30 psf roof rating |
| Ice storms and fallen trees | Tree removal and other structures coverage |
| Frozen pipes | Water damage coverage; heat tape and skirting |
| Power outages | Food spoilage coverage |
| Tornadoes | Wind coverage; tie-downs; shelter plan |
Our assessment, based on NWS, Michigan State Police, and HUD roof-load rules.
PRO TIP #3
If you buy a home built for southern Michigan and move it north of the 20 psf line, check its data plate. A home rated for 20 pounds per square foot may not meet the 30 psf rule in a middle-zone county, and an insurer may question a roof claim after heavy snow.
Tornadoes and mobile homes in Michigan
Michigan has experienced several damaging tornado years. Published counts and preliminary tallies can differ as weather-service surveys are finalized. A 2025 news summary reported 33 tornadoes, and a July 2026 report counted at least 23 by that date. Those partial counts are historical context, not a final statewide 2026 annual total. The more important insurance questions concern wind coverage, anchoring requirements and a safe shelter plan.
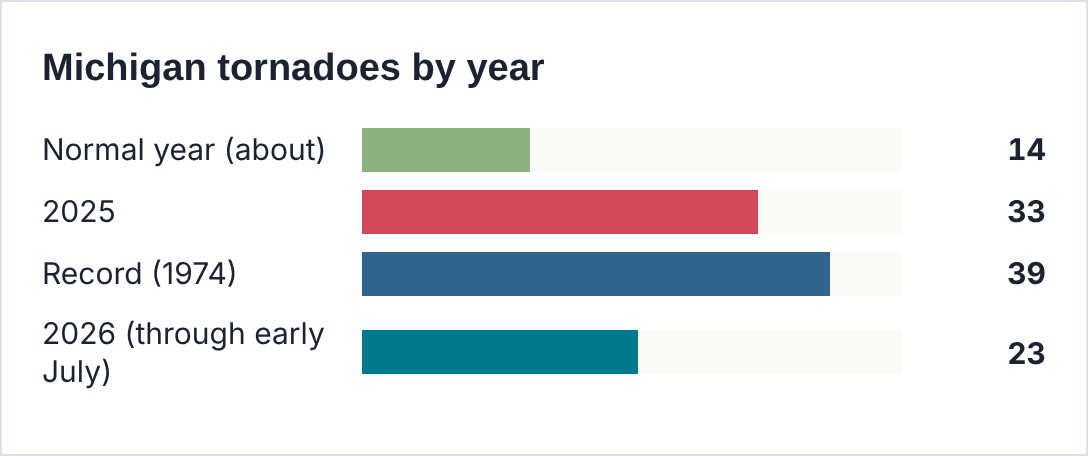
National Weather Service figures as reported by WILX (2025), WWMT (December 31, 2025), and WGRD (July 2, 2026). 2026 count is partial.
Mobile homes are especially vulnerable to tornadoes. The National Weather Service advises residents to identify a sturdy shelter in advance and leave a manufactured home when a tornado warning threatens; anchoring is important but does not make a mobile home a safe tornado shelter. A deadly March 6, 2026 tornado struck near Union City and damaged mobile homes, reinforcing the need for a shelter plan as well as insurance.
Michigan saw this again on March 6, 2026, when an EF3 tornado with 160 mph winds hit Union City in Branch County. It threw a mobile home about 100 yards, killing the person inside, and the same storm system killed four people across southern Michigan.
Recent Michigan tornadoes that hit mobile homes
| Date | Where | What happened |
|---|---|---|
| May 20, 2022 | Gaylord | EF3; 2 deaths in a mobile home park; park 95% destroyed |
| May 7, 2024 | Portage | EF2, 135 mph; about 176 park homes damaged |
| March 6, 2026 | Union City | EF3, 160 mph; mobile home thrown 100 yards, 1 death |
| April 2026 | Lower Michigan | 9 tornadoes plus flooding; disaster aid in 27 counties |
National Weather Service; NPR; 9&10 News; Fox 2 Detroit; WWMT; Office of the Governor.
Floods and the April 2026 disaster
Flooding causes more property damage than any other natural disaster in Michigan, and in April 2026 heavy rain, melting snow, and nine tornadoes hit 43 counties. The Cheboygan Dam was at risk of overtopping, and a federal disaster declaration in July brought aid for homeowners in 27 counties, including Kalamazoo, Saginaw, Washtenaw, and Grand Traverse. The state insurance department reminded residents that most home policies do not cover flood damage.
Federal flood insurance covers manufactured homes for up to $250,000 on the home and $100,000 on contents, but the home must be anchored, and new policies usually take 30 days to start. About 194 of Michigan’s 1,573 communities do not take part in the federal flood program, so check that yours does. Lakeshore owners should also know that bluff erosion and high Great Lakes water levels in 2020 damaged homes along Lake Michigan.
Michigan flood insurance basics for mobile homes
| Item | Details |
|---|---|
| Home coverage | Up to $250,000 |
| Contents coverage | Up to $100,000 |
| Requirement | Home must be anchored to ground anchors |
| Waiting period | Usually 30 days |
| Communities not in the program | 194 of 1,573 |
FEMA manufactured home fact sheet (August 2025); FEMA FloodSmart; FEMA data via a November 2024 analysis.
Michigan mobile home taxes and tax credits
Michigan generally charges an occupied mobile home in a licensed park a $3 monthly specific tax under MCL 125.1041 instead of ad valorem property taxes on the home. Other structures can have separate taxation. A home outside a licensed park may be treated as real property for property-tax purposes; confirm ownership and classification with the local assessor.
Eligible park residents may calculate the Homestead Property Tax Credit by counting $3 for each month lived in the park (up to $36), subtracting that amount from eligible annual rent, and using 23% of the remaining rent as the share treated as property tax. This calculation is not the refundable credit itself: income, residency, property-tax share and annual limits determine the actual credit. The $1,900 maximum and $71,500 resource threshold below refer to tax year 2025, not confirmed 2026 figures. See Michigan Treasury’s official instructions.
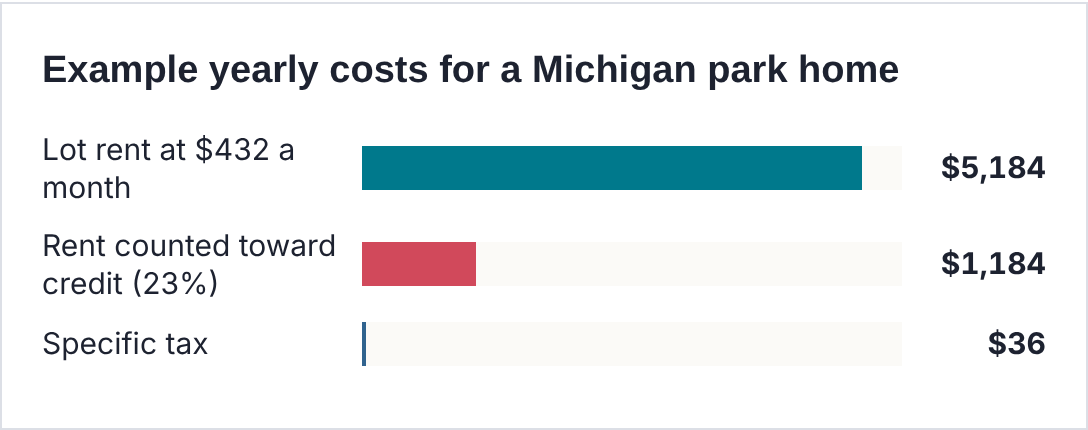
Our calculation: (5,184 minus 36) times 23% is about $1,184 counted toward the credit, plus the $36 tax. Lot rent example from Bridge Michigan (2022). Actual credit depends on income.
Michigan mobile home tax rules
| Item | Rule |
|---|---|
| Home in a licensed park | $3 a month specific tax (MCL 125.1041) |
| Home outside a park | Taxed as real property |
| Homestead credit, park residents | $36 tax plus 23% of remaining rent |
| Maximum credit (2025) | $1,900 |
| Income limit (2025) | $71,500 total household resources |
| Title | Secretary of State; $90 plus 6% use tax |
Michigan Department of Treasury; 2025 MI-1040CR instructions; Michigan Secretary of State.
Michigan park residents’ rights and the 2026 reform bills
Michigan regulates manufactured-housing communities through the Department of Licensing and Regulatory Affairs (LARA), which receives complaints about regulated park conditions. Lot-rent disagreements and contractual issues may require separate assistance. As of November 18, 2026, the legislative history for Senate Bills 934–939 shows Senate passage on May 19 and referral to the Michigan House; those proposals should not be treated as enacted tenant protections.
The Senate Bills 934–939 package, introduced in April 2026, proposes changes relating to community regulation, lease terms, closures, eviction protections and resident ownership. The Michigan Legislature lists Senate passage on May 19, 2026, followed by House referral. We found no subsequent enactment in that official history as of this review. The text of a proposal may change before it becomes law.
Michigan Senate Bills 934 to 939 (2026)
| Bill | Main change | Status |
|---|---|---|
| SB 934 | Licensing reform; public park and owner database | Passed Senate |
| SB 935 | One-year leases; 12-month closure notice; utility caps | Passed Senate 32-2 |
| SB 936 | Just-cause eviction; options for the home | Passed Senate |
| SB 937 | Resident right to negotiate on park sales | Passed Senate |
| SB 938 | 15% tax credit for selling to residents | Passed Senate |
| SB 939 | Resident ownership revolving fund | Passed Senate |
Michigan Legislature, SB 934–939 bill histories, reviewed November 18, 2026; status shown as House referral after Senate passage.
Michigan laws every mobile home owner should know
- We found no Michigan law requiring mobile home insurance, but lenders do, and many parks require it as a condition of residency.
- Every home must be installed by the manufacturer’s instructions with an anchoring system, and footings must reach 42 inches below grade unless a soil study allows less.
- Homes may not be placed in a designated floodway.
- Installers, dealers, and communities must be licensed by the state.
- Mobile homes are titled through the Secretary of State.
- All of Michigan is in HUD Wind Zone I.
The Michigan Basic Property Insurance Association
The Michigan Basic Property Insurance Association (MBPIA) offers a last-resort route for certain property risks through licensed agents when ordinary coverage is unavailable. Its general consumer materials do not establish that every movable or older manufactured home qualifies. Ask an agent to confirm eligibility, covered perils, deductibles and whether the resulting policy meets any lender or park requirement.
Why Michigan home insurance costs are rising
Michigan home insurance prices have climbed quickly. One study found the state’s average premium rose 41% from 2023 to 2025, from $2,072 to $2,924, the second-biggest increase in the country after Louisiana. Another analysis put Michigan’s total increase at 29.9% from 2023 to 2026. Statewide homeowners premiums reached $4.28 billion in 2024, 11th in the nation.
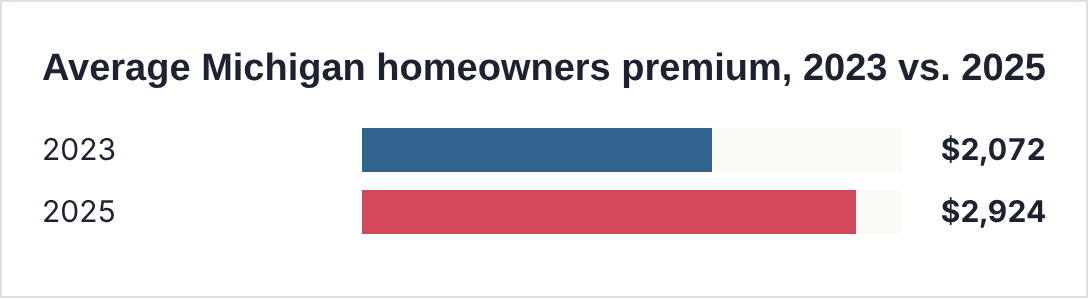
Study D, State of Home Insurance (February 9, 2026).
Mobile home insurance vs. homeowners insurance in Michigan
How Michigan mobile home and homeowners policies compare
| Feature | Mobile home policy | Homeowners policy |
|---|---|---|
| Typical yearly cost | About $802 (Study E) | About $2,195 to $2,545 on average |
| Main insurers | Foremost, American Modern, Assurant, Auto-Owners | Allstate, Auto-Owners, AAA, State Farm |
| Tax | $3 a month in a licensed park | Property tax |
| Biggest risk factor | Anchoring and tie-downs | Roof age and construction |
| Flood coverage | Separate policy | Separate policy |
Study B; Study C; Study E; 2026 homeowners studies; MCL 125.1041.
What Michigan mobile home insurance covers
Main coverage parts of a Michigan mobile home policy
| Coverage | What it pays for |
|---|---|
| Dwelling | Repairs or replacement of the home |
| Other structures | Carports, decks, sheds, and skirting |
| Personal property | Furniture, clothes, and belongings |
| Loss of use | Living costs after a covered loss |
| Personal liability | Injuries or damage you cause to others |
| Not usually covered | Flood, earthquake, and sewer backup unless added |
When comparing forms, distinguish dwelling, belongings, liability and loss-of-use protection from the limitations and exclusions written into the manufactured-home contract. The linked overview explains general home coverage; the final mobile-home policy wording controls.
Company policy descriptions; coverage varies by insurer.
How to check an insurer’s service record
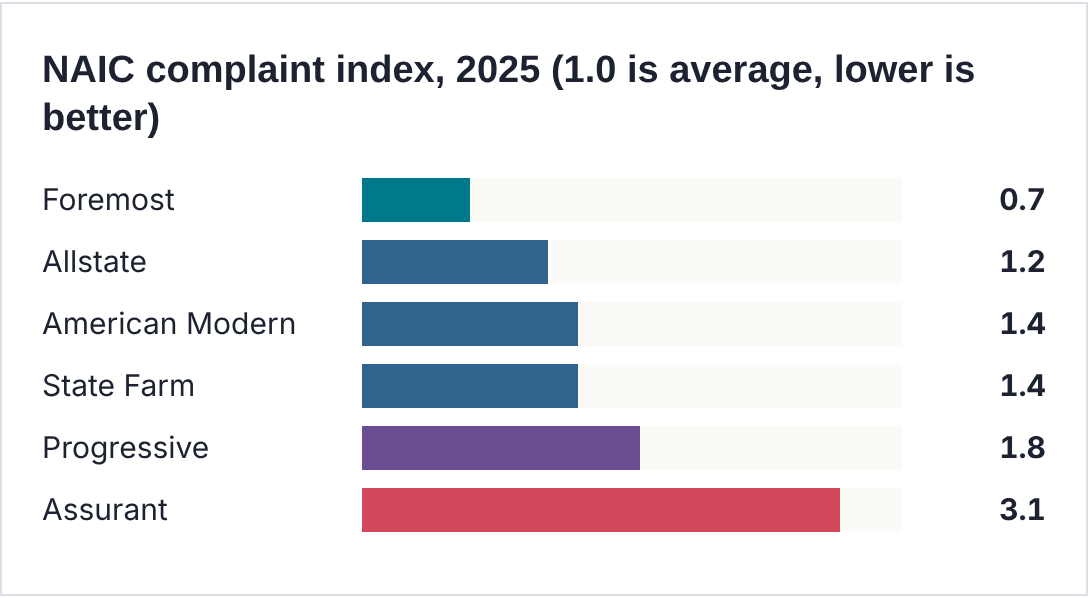
Regulator complaint ratios should be checked by the issuing legal insurer and reporting year; a corporate brand or national mobile-home comparison cannot replace that verification. The importance of insurer customer support is another consideration when evaluating how promptly and clearly a company handles a loss, but it is not a numerical Michigan claims ranking. Michigan DIFS publishes issuer-level complaint ratios.
NAIC complaint index for 2025, as reported in a national mobile home review updated September 15, 2026. Michigan insurers such as Auto-Owners were not included.
Bundling mobile home and auto insurance in Michigan
Bundling a manufactured-home policy with car insurance can help, but published discounts for conventional homeowners are not proof of manufactured-home savings because car insurance is expensive here. A September 2026 analysis of policies people actually bought found Michigan drivers paid about $3,836 a year for full coverage. Study D found Michigan home and auto bundles saved an average of 19%, or $356, but savings varied widely by company. If you need a low initial car-insurance bill, compare Michigan auto insurance with a lower first payment alongside your combined home-and-auto premium; a smaller first payment is not necessarily a cheaper annual total. Consider adjusting the auto-policy limits and deductibles separately from the manufactured-home protection to make the two sides of a bundle comparable.
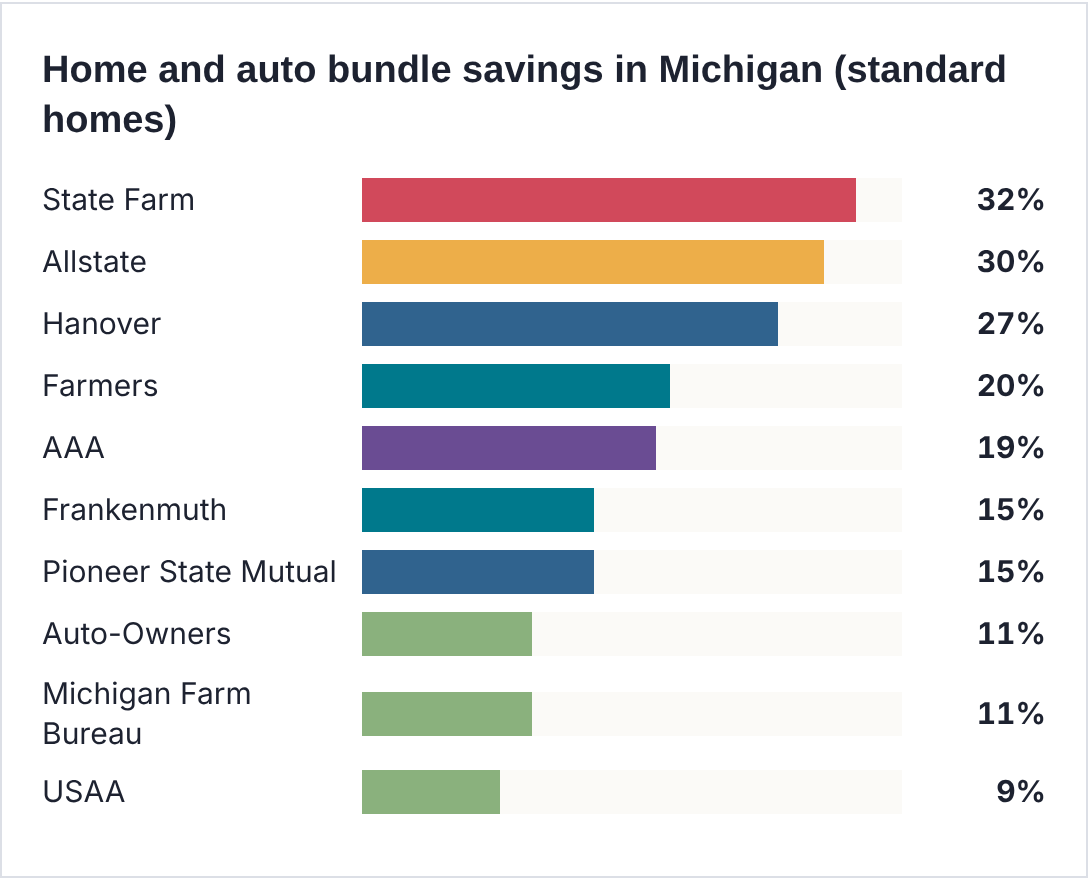
Study D: Michigan homeowners study updated September 30, 2026. Figures are for standard homes, not mobile homes.
The size of a conventional homeowners-and-auto bundle discount does not predict a mobile-home bundle result. An 11% discount on a competitive base price might beat a 32% discount on a higher base price; compare final annual totals for the policies you can actually buy, including the coverage differences.
Mobile home insurance discounts in Michigan
Discounts to ask for in Michigan
| Discount | Who offers it |
|---|---|
| Age 50+ or retired 55+ | Foremost, Fremont (50+); Allstate (retired, 55+) |
| Tie-downs | Fremont |
| Newer home | Foremost, State Farm, Michigan Farm Bureau, Pioneer |
| Approved park | Foremost |
| Protective devices and alarms | Auto-Owners, Fremont, State Farm, Farm Bureau |
| Paid in full or good payment history | Auto-Owners |
| Non-smoker | Fremont (5%) |
| Multi-policy | Most insurers |
Company websites (2026). Discount amounts vary.
Tips to save money on mobile home insurance in Michigan
- Get at least three quotes, starting with Assurant, American Modern, and Foremost.
- Add Auto-Owners, Frankenmuth, and Fremont through a local independent agent.
- Make sure your quotes come from different underlying insurers.
- Ask for senior, tie-down, newer-home, park, and alarm discounts.
- Compare final premiums and how a higher insurance deductible changes out-of-pocket costs, not only the advertised bundle percentage.
- Claim the Homestead Property Tax Credit if you rent a lot.
- Buy flood insurance at least 30 days before spring melt.
- Shop again every year, since Michigan rates have risen fast.
What to do after a tornado, ice storm, or flood
- Get to safety, then call your insurer or agent as soon as you can.
- Take photos and video of all damage before cleaning up.
- Make temporary repairs and keep the receipts.
- Be wary of door-to-door contractors after a storm.
- If you have a problem, call the Michigan Department of Insurance and Financial Services at 877-999-6442.
Michigan mobile home insurance at a glance
This illustrated summary pulls together the main points of this guide.
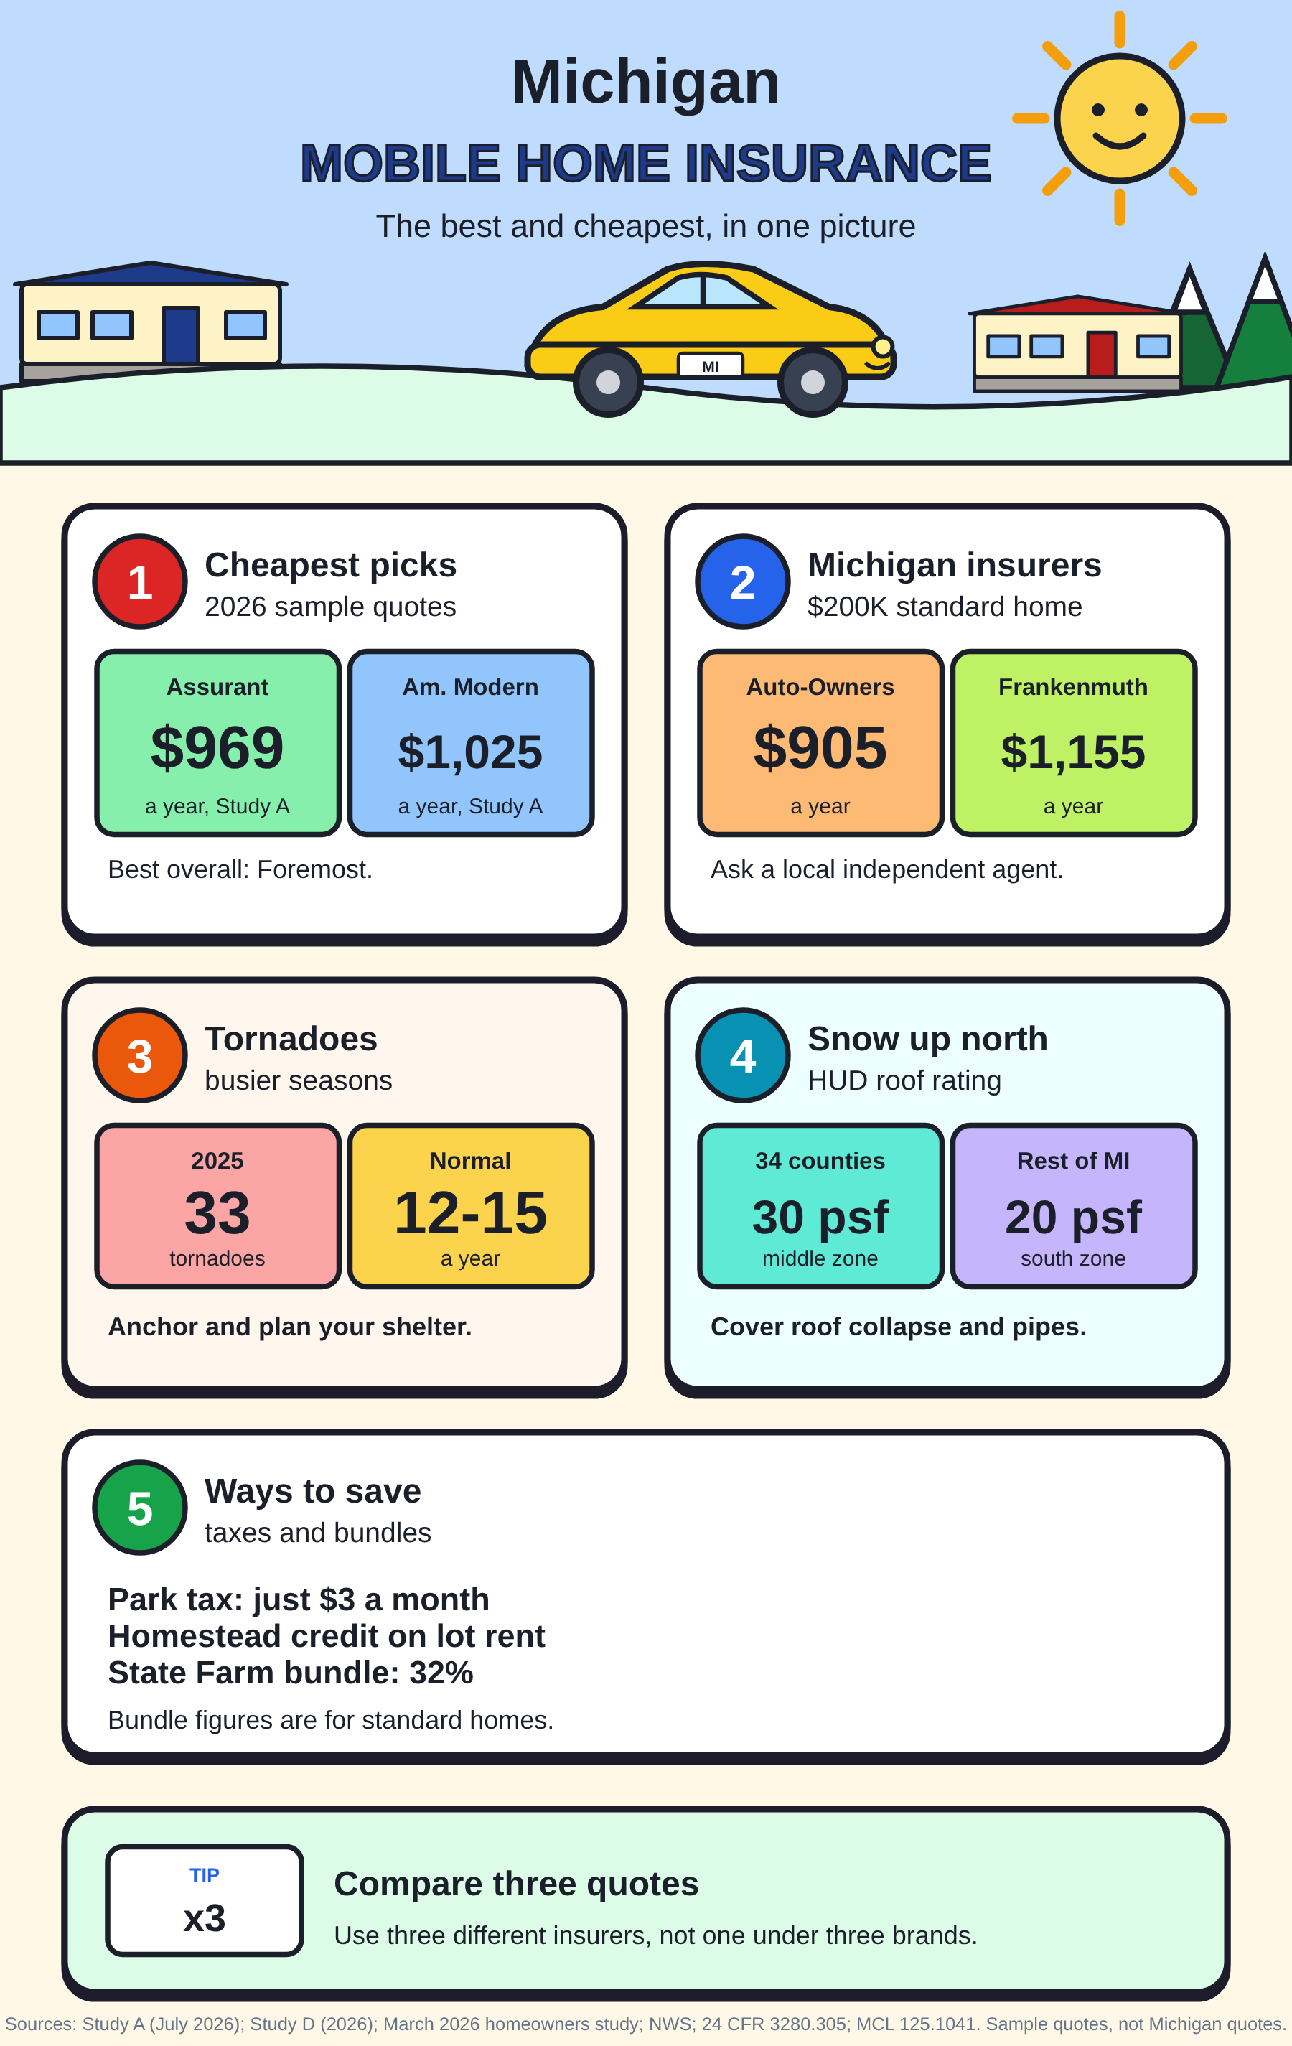
Michigan mobile home insurance at a glance. Sources: Study A; Study D; March 2026 homeowners study; NWS; MCL 125.1041.
Image accuracy notice: original infographic figures mix out-of-state manufactured-home quotes and conventional-home study prices. Those figures cannot establish Michigan mobile-home premiums.
Frequently asked questions about Michigan mobile home insurance
How much is mobile home insurance in Michigan?
Study E lists about $802 a year, but does not explain the dwelling profile or method well enough to verify this as a statewide average. Your actual manufactured-home quote depends on the property, address, coverage, age and condition.
Who has the cheapest mobile home insurance in Michigan?
No verified like-for-like Michigan manufactured-home ranking is available from the cited studies. Assurant’s $969 figure was from an out-of-state sample. Request quotes from Michigan-eligible specialty and local insurers for the same dwelling and coverage limits before deciding which is cheapest for your property.
What is the best mobile home insurance company in Michigan?
Foremost is an established specialty option worth quoting, but the national complaint index alone does not establish the best claims experience in Michigan. Auto-Owners, Frankenmuth and Fremont are also useful Michigan-specific candidates.
What is the best mobile home insurance for seniors in Michigan?
Foremost and Fremont offer discounts at age 50, and Allstate offers one for retired owners over 55. Park residents can also claim the Homestead Property Tax Credit on part of their rent.
Do mobile homes pay property tax in Michigan?
Homes in licensed parks pay a $3 monthly specific tax instead. Homes outside licensed parks are taxed as real property.
Does mobile home insurance cover tornado and ice storm damage in Michigan?
Many manufactured-home policies cover certain wind and storm damage, but the covered perils, snow or ice losses, exclusions, anchoring conditions and deductibles differ. Check the actual policy. Flood insurance generally requires a separate contract.
Is mobile home insurance required in Michigan?
We found no state law requiring it, but lenders do, and many parks require it as a condition of residency.
The final word on Michigan mobile home insurance
No insurer can be called Michigan’s overall cheapest manufactured-home carrier from these data. Assurant and American Modern posted lower prices in one out-of-state sample, and Foremost offers a longstanding specialty product. Michigan companies such as Auto-Owners, Frankenmuth, Fremont, Michigan Farm Bureau and Pioneer State Mutual provide additional alternatives to investigate. The standard-home prices cited elsewhere on this page are not mobile-home premiums.
For a usable comparison, request manufactured-home quotes for the same property, comparing replacement-cost terms, exclusions and deductibles as well as the final premium, coverage limits, valuation basis, deductibles and add-ons; compare the underlying carriers, not just agents or storefronts. Check tornado shelter access, snow-load suitability, roof condition, wind coverage and flood exclusions. Review the park tax and Homestead Property Tax Credit separately from insurance discounts.
Sources
- Study A: ValuePenguin, mobile home insurance (July 6, 2026).
- Study B: ValuePenguin, cheap homeowners insurance in Michigan (September 25, 2026).
- Study C: MoneyGeek, average cost of home insurance in Michigan and best cheap homeowners insurance in Michigan (September 15, 2026).
- Study D: Insurance.com, Michigan homeowners insurance (September 30, 2026), and State of Home Insurance (February 9, 2026).
- Study E: Insuranceopedia, mobile home insurance by state (October 18, 2026).
- NerdWallet, Michigan homeowners insurance (March 4, 2026); Insurify, Michigan homeowners insurance (October 21, 2026); LendingTree, Michigan homeowners insurance; and LendingTree, best mobile home insurance companies (September 15, 2026).
- Foremost, about; Foremost, mobile home insurance; Auto-Owners, mobile home; Frankenmuth Insurance; Fremont Insurance, mobile homeowners; Michigan Farm Bureau, mobile homeowners; Pioneer State Mutual, mobile home; and State Farm, manufactured homes.
- NerdWallet, mobile home insurance (May 2025); Policygenius, mobile home insurance in Michigan; Policygenius, Assurant review; NerdWallet, American Family review; NerdWallet, Kin review; and NerdWallet, Nationwide review.
- Experian, average car insurance cost in Michigan (October 13, 2026); NAIC, Michigan key facts (2025); and Newsweek, rising home insurance costs (October 20, 2026).
- PESP, Michigan manufactured homes (July 2025); Michigan Advance, private equity parks (July 2025); NAR, Michigan profile; BridgeDetroit, mobile home residents (March 2024); Bridge Michigan, lot rent (July 2022); and MHVillage, Michigan parks by county.
- Fox 2 Detroit, Portage tornado (May 2024); Michigan Public, Kalamazoo County damage (May 2024); WMUK, one year later (May 2025); NPR, Gaylord tornado (May 2022); and 9&10 News, Nottingham Forest (May 2022).
- National Weather Service, March 6, 2026 tornadoes; WWMT, Union City tornado (March 2026); WILX, Michigan tornadoes (May 2025); WWMT, 2025 weather (December 2025); WGRD, 2026 tornadoes (July 2026); National Weather Service, mobile home safety; and National Weather Service, 2024 tornado deaths.
- Michigan State Police, ice storm appeal (October 2025); Office of the Governor, 2026 disaster declaration (July 2026); DIFS, flooding tips (April 2026); BridgeDetroit, 2021 floods (June 2022); and Mining Gazette, Keweenaw snow (April 2025).
- FEMA, manufactured homes flood coverage (August 2025); Michigan flood program participation (November 2024); and CBS News, Great Lakes water levels (February 2020).
- 24 CFR 3280.305; Mich. Admin. Code R 125.1602; LARA, Mobile Home Section; and Michigan Secretary of State, mobile homes.
- Michigan Treasury, trailer park and mobile homes bulletin; Michigan Treasury, homestead credit for renters; and 2025 MI-1040CR instructions.
- Michigan Senate Democrats, manufactured housing bills (April 2026); MichiganVotes, SB 935; PESP, 2026 bills (May 2026); and WNEM, mobile home law changes (May 2026).
- DIFS, Michigan Basic Property Insurance Association guide.
- Michigan Treasury, tax treatment of mobile homes (reviewed November 18, 2026).
- Michigan Treasury, Homestead Property Tax Credit for mobile-home park residents (reviewed November 18, 2026).
- Michigan Legislature, Senate Bill 935 and related 2026 package (reviewed November 18, 2026).
- Michigan DIFS, 2025 homeowners complaint ratios by issuing insurance company (reviewed November 18, 2026).
- Michigan DIFS, purchasing home insurance and MBPIA (reviewed November 18, 2026).
- Frankenmuth Insurance, Michigan manufactured-home coverage (reviewed November 18, 2026).
- Fremont Insurance, mobile-homeowners coverage (reviewed November 18, 2026).
- Michigan Secretary of State, mobile-home titles and use tax (reviewed November 18, 2026).
Disclaimer
This website provides independent reviews and comparisons. It is not affiliated with, endorsed by, sponsored by, or connected to Assurant, American Modern, Foremost, Farmers, Auto-Owners, Frankenmuth Insurance, Fremont Insurance, Allstate, State Farm, Michigan Farm Bureau, Pioneer State Mutual, AAA, The Hanover, USAA, Progressive, GEICO, Westfield, American Family, Kin, Nationwide, the Michigan Basic Property Insurance Association, or any of their affiliates.
All company names, brand names, trademarks, and logos are the property of their respective owners and are used here only to identify the companies being reviewed. Their use does not imply any affiliation or endorsement.
The information on this page is provided for general informational and educational purposes only. It is not insurance, legal, tax, or financial advice, and it is not an offer, quote, or solicitation to buy or sell insurance. We are not an insurance company, insurance agency, or licensed insurance producer, and we cannot bind coverage, change a policy, or handle claims.
Prices, discounts, ratings, and company details are drawn from public sources and third-party studies that use specific home profiles, and they can change at any time. They are estimates and averages, not guarantees of what you will pay. Coverage, eligibility, and discounts vary by location, home, and owner, and are subject to each insurer’s underwriting rules and policy terms.
While we make reasonable efforts to keep this guide accurate and current, we make no representations or warranties, express or implied, about its completeness, accuracy, or reliability. Opinions here are our own. Always confirm details directly with the insurer, read your policy documents, and consult the Michigan Department of Insurance and Financial Services or a licensed professional before making a decision. Your use of this information is at your own risk, and we are not liable for any loss or damage arising from reliance on it.