
Hawaii Mobile Home Insurance: Costs, Hurricane & Lava Coverage
Shopping for Hawaii mobile home insurance requires more than choosing the lowest advertised home premium. Manufactured-home coverage is a small, specialized market in Hawaii, and a conventional homeowners quote may not apply to a HUD-code manufactured home. Hurricane wind, flood, tsunami, wildfire, earthquake and volcanic risks also require careful examination of policy terms.
This guide examines published insurance costs and potential markets, explains why a verified Hawaii-specific cheapest-company ranking is not available, and covers hurricane deductibles, Wind Zone III installation, lava-zone coverage, flood protection, county tax relief and practical quote comparisons. Company eligibility and availability must be confirmed for the actual home, island and address.
KEY TAKEAWAYS
- One third-party state table lists about $502 a year for a Hawaii mobile home, but it does not disclose enough underwriting detail to treat that as a verified statewide average or a quote.
- Foremost explicitly excludes Hawaii from its mobile-home program. American Modern has an authorized Hawaii insurer, but manufactured-home availability and pricing for your location must be confirmed.
- Hawaii is in HUD Wind Zone III for manufactured homes. A valid data plate, site anchoring and the actual hurricane and wind exclusions are critical.
- Compare hurricane deductibles and the combined price of home, hurricane and flood insurance; standard-home sample premiums may omit important catastrophe protection.
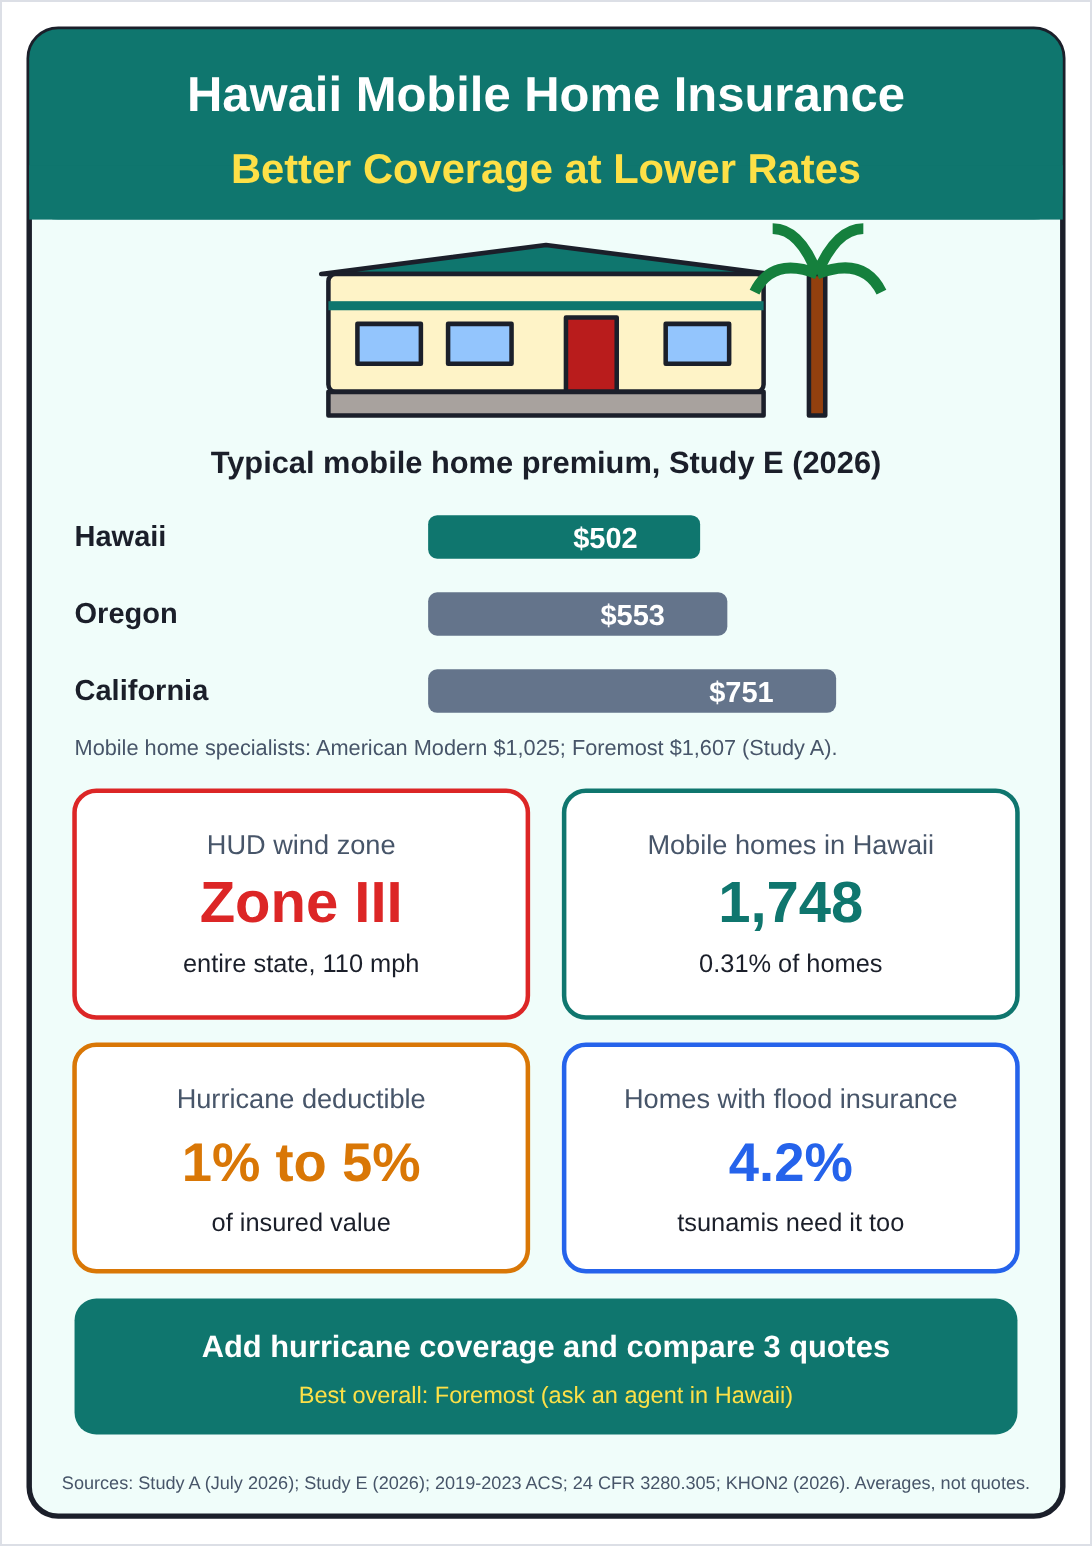
Image accuracy notice: This original graphic contains rankings or sample amounts that are not validated Hawaii manufactured-home prices. Foremost mobile-home coverage is not available in Hawaii. Rely on the corrected text and tables, not figures embedded in this image.
Hawaii mobile home insurance at a glance. Company prices are Study A’s 2026 sample quotes, not Hawaii quotes.
How much mobile home insurance costs in Hawaii
No sourced like-for-like comparison establishes the cheapest manufactured-home insurer in Hawaii. Study E’s October 2026 state table lists approximately $502 a year, but the published table does not establish the dwelling profile, perils or hurricane treatment. Treat that amount as a rough estimate, not an obtainable quote, and compare written home insurance policies with the same coverage limits and deductibles before choosing a policy.
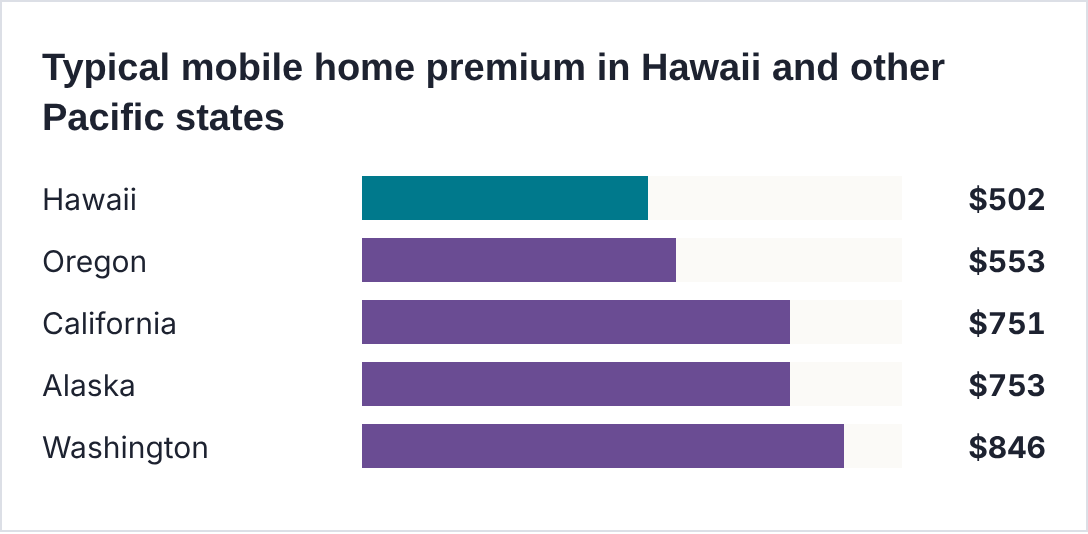
Study E national table (October 18, 2026). Method and coverage amount not published, so treat as rough estimates.
Study A, updated July 6, 2026, tested a 2016 single-wide manufactured home in three mainland cities—not in Hawaii. Its quoted $969 for Assurant, $1,025 for American Modern and $1,607 for Foremost are useful only as out-of-state examples. Assurant does not advertise availability in Hawaii, and Foremost’s official mobile-home quote page explicitly excludes Hawaii. None of those three amounts identifies Hawaii’s cheapest option.
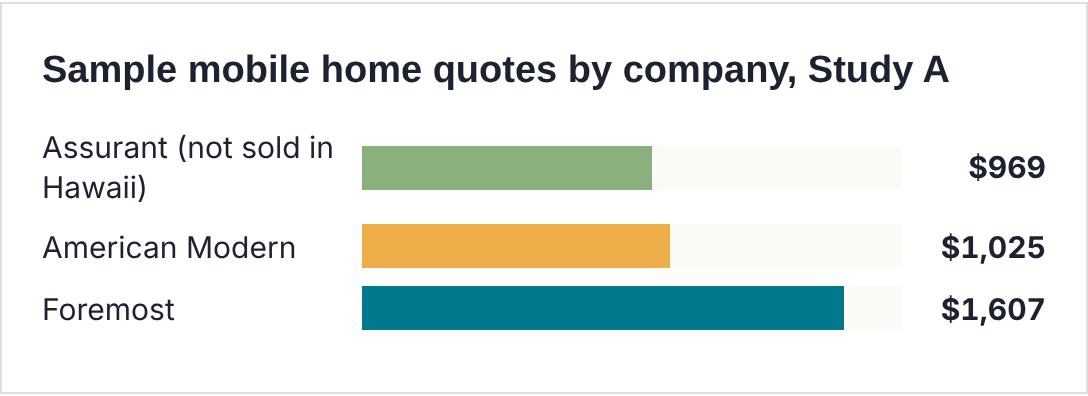
Study A: national mobile home quote study updated July 6, 2026, for a 2016 single-wide in a park in Austin, Indianapolis, and Mesa. No Hawaii quotes.
Study C lists premiums of $200 for DB Insurance and $223 for State Farm for a $100,000 conventional home. These are not mobile-home insurance quotes, and they cannot show what a Wind Zone III manufactured-home policy—or separate hurricane coverage—will cost. Eligibility must be checked with each insurer.
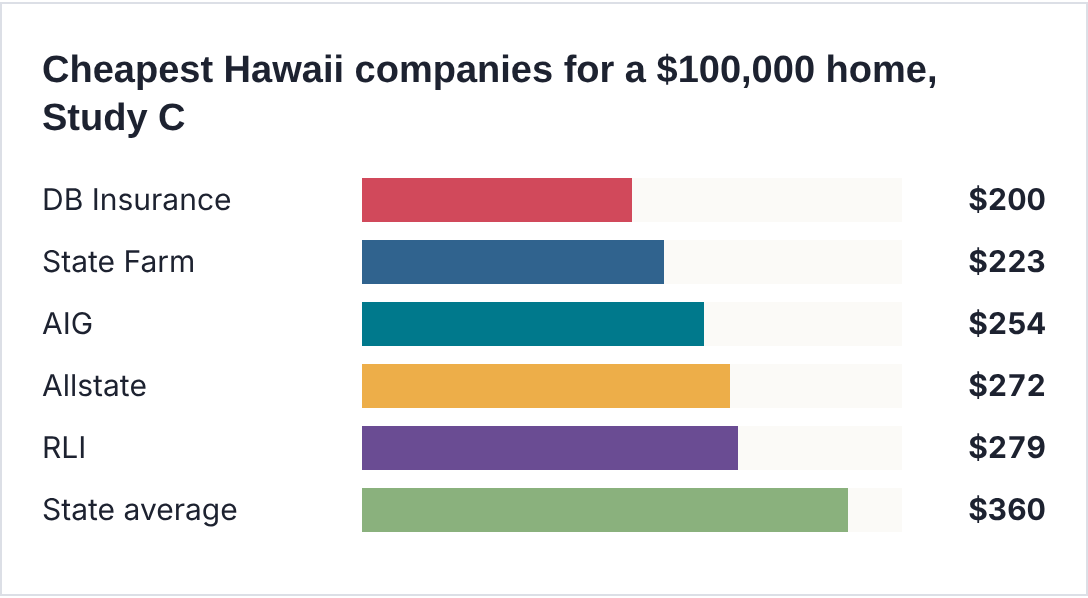
Study C, updated October 1, 2026, $100,000 dwelling. Standard-home policies, not mobile home policies; hurricane coverage usually extra.
Hawaii premiums for a $200,000 home, by company (Study D)
| Company | Yearly cost |
| DB Insurance | $381 |
| Universal Insurance | $393 |
| AIG | $431 |
| Allstate | $525 |
| Island Insurance | $611 |
| RLI | $675 |
| Tokio Marine | $692 |
| State Farm | $754 |
Study D, updated September 30, 2026, $200,000 dwelling with a 2% hurricane deductible where it applies. Standard homes, not mobile homes.
What standard Hawaii homeowners pay
Several 2026 studies report relatively low average premiums for conventional homes in Hawaii. Their averages vary with dwelling limits, policy forms and modeled risks: Study B lists $501 for a $200,000 conventional home; Study D lists $738 for a $300,000 home. These figures should not be transferred to manufactured homes or interpreted as the total cost of hurricane and flood protection.
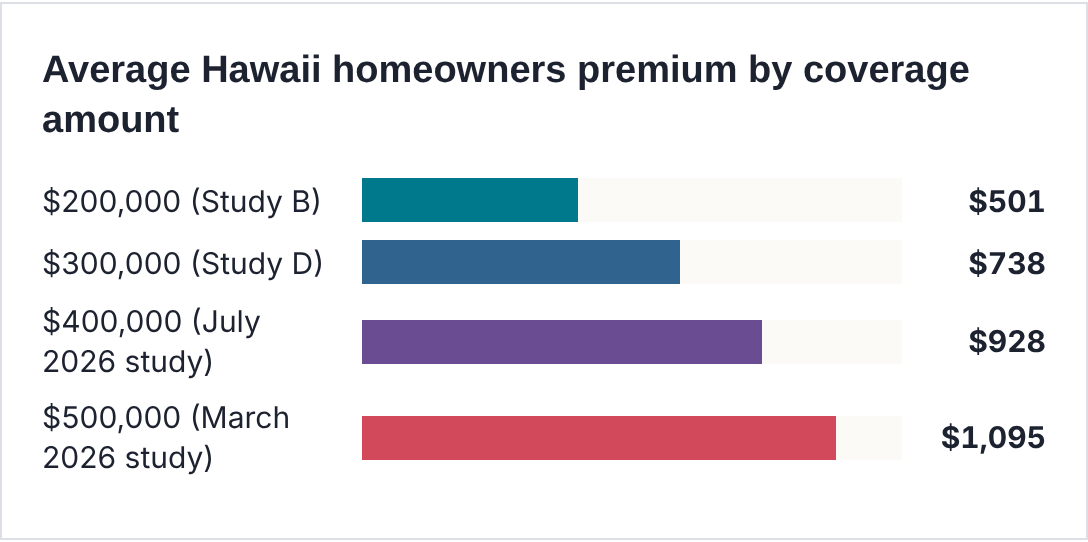
2026 Hawaii homeowners studies. Standard homes, not mobile homes. Averages, not quotes.
One conventional-home study found little difference between its modeled Oahu and neighbor-island premiums. That result does not establish equal pricing for manufactured homes: construction, Wind Zone III compliance, wildfire exposure, volcano hazard, flood zone and hurricane underwriting can materially change eligibility and cost.
Hawaii homeowners averages by island and city
| Area | July 2026 study ($400K) | Study B ($350K) |
| Honolulu and the rest of Oahu | $925 | $799 (Honolulu) |
| Kailua (Oahu) | $928 | $801 |
| Hilo (Hawaii Island) | $931 | $803 |
| Kahului and Kihei (Maui) | $931 | Not listed |
| Lihue (Kauai) | $931 | Not listed |
July 2026 Hawaii homeowners study; Study B (September 25, 2026). Standard homes, not mobile homes.
Hawaii mobile homes by the numbers
Hawaii has a very small manufactured-home stock relative to other states. The State of Hawaii Data Book’s 2019–2023 ACS table reports 1,748 mobile homes in the statewide housing inventory. This count is not the number of currently insurable HUD-code homes or a measure of available private insurance capacity.
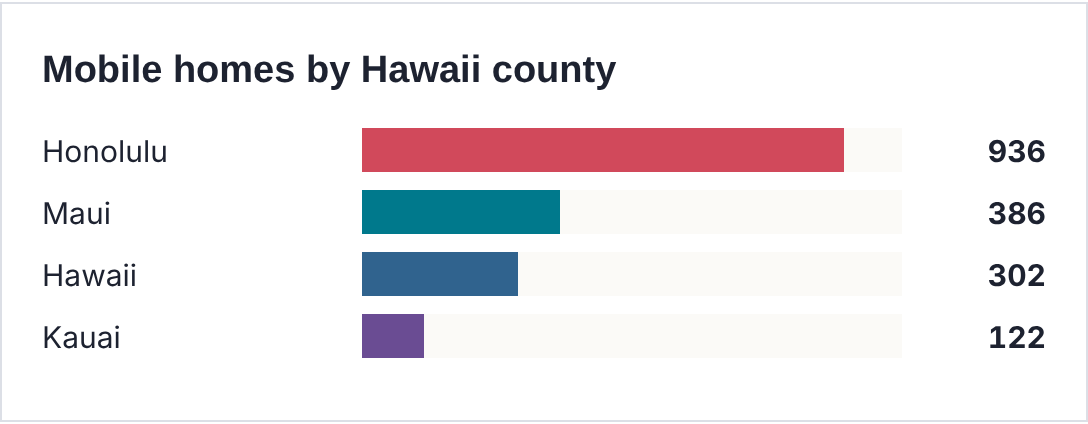
2019-2023 American Community Survey, via the State of Hawaii Data Book 2024.
High housing costs have renewed interest in factory-built housing. However, the temporary prefabricated FEMA units installed after the 2023 Lahaina wildfire should not be assumed to have the same classification, installation requirements or insurance market as a privately owned HUD-code manufactured home. Verify the home’s legal classification before requesting coverage.
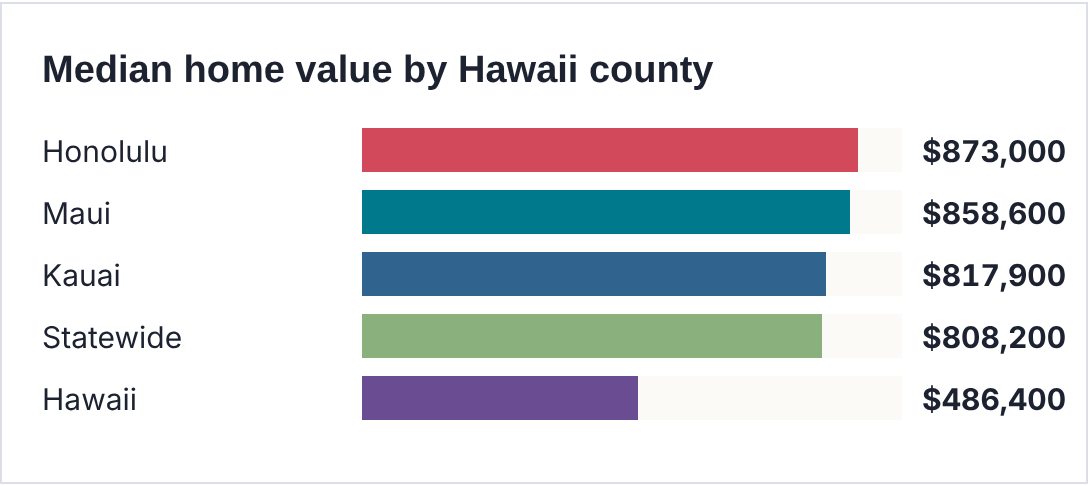
2019-2023 American Community Survey, via the State of Hawaii Data Book 2024.
Insurance companies and coverage channels to check in Hawaii
The table identifies potential insurance contacts and coverage channels, not a price ranking. Foremost’s mobile-home program is not available in Hawaii. American Modern’s property-and-casualty entity appears among Hawaii-authorized insurers, but that fact alone does not verify that its manufactured-home product is offered at a particular address. Conventional-home insurers and specialized hurricane providers may have different eligibility rules; obtain written confirmation of the issuing company, policy form, covered perils and hurricane provisions.
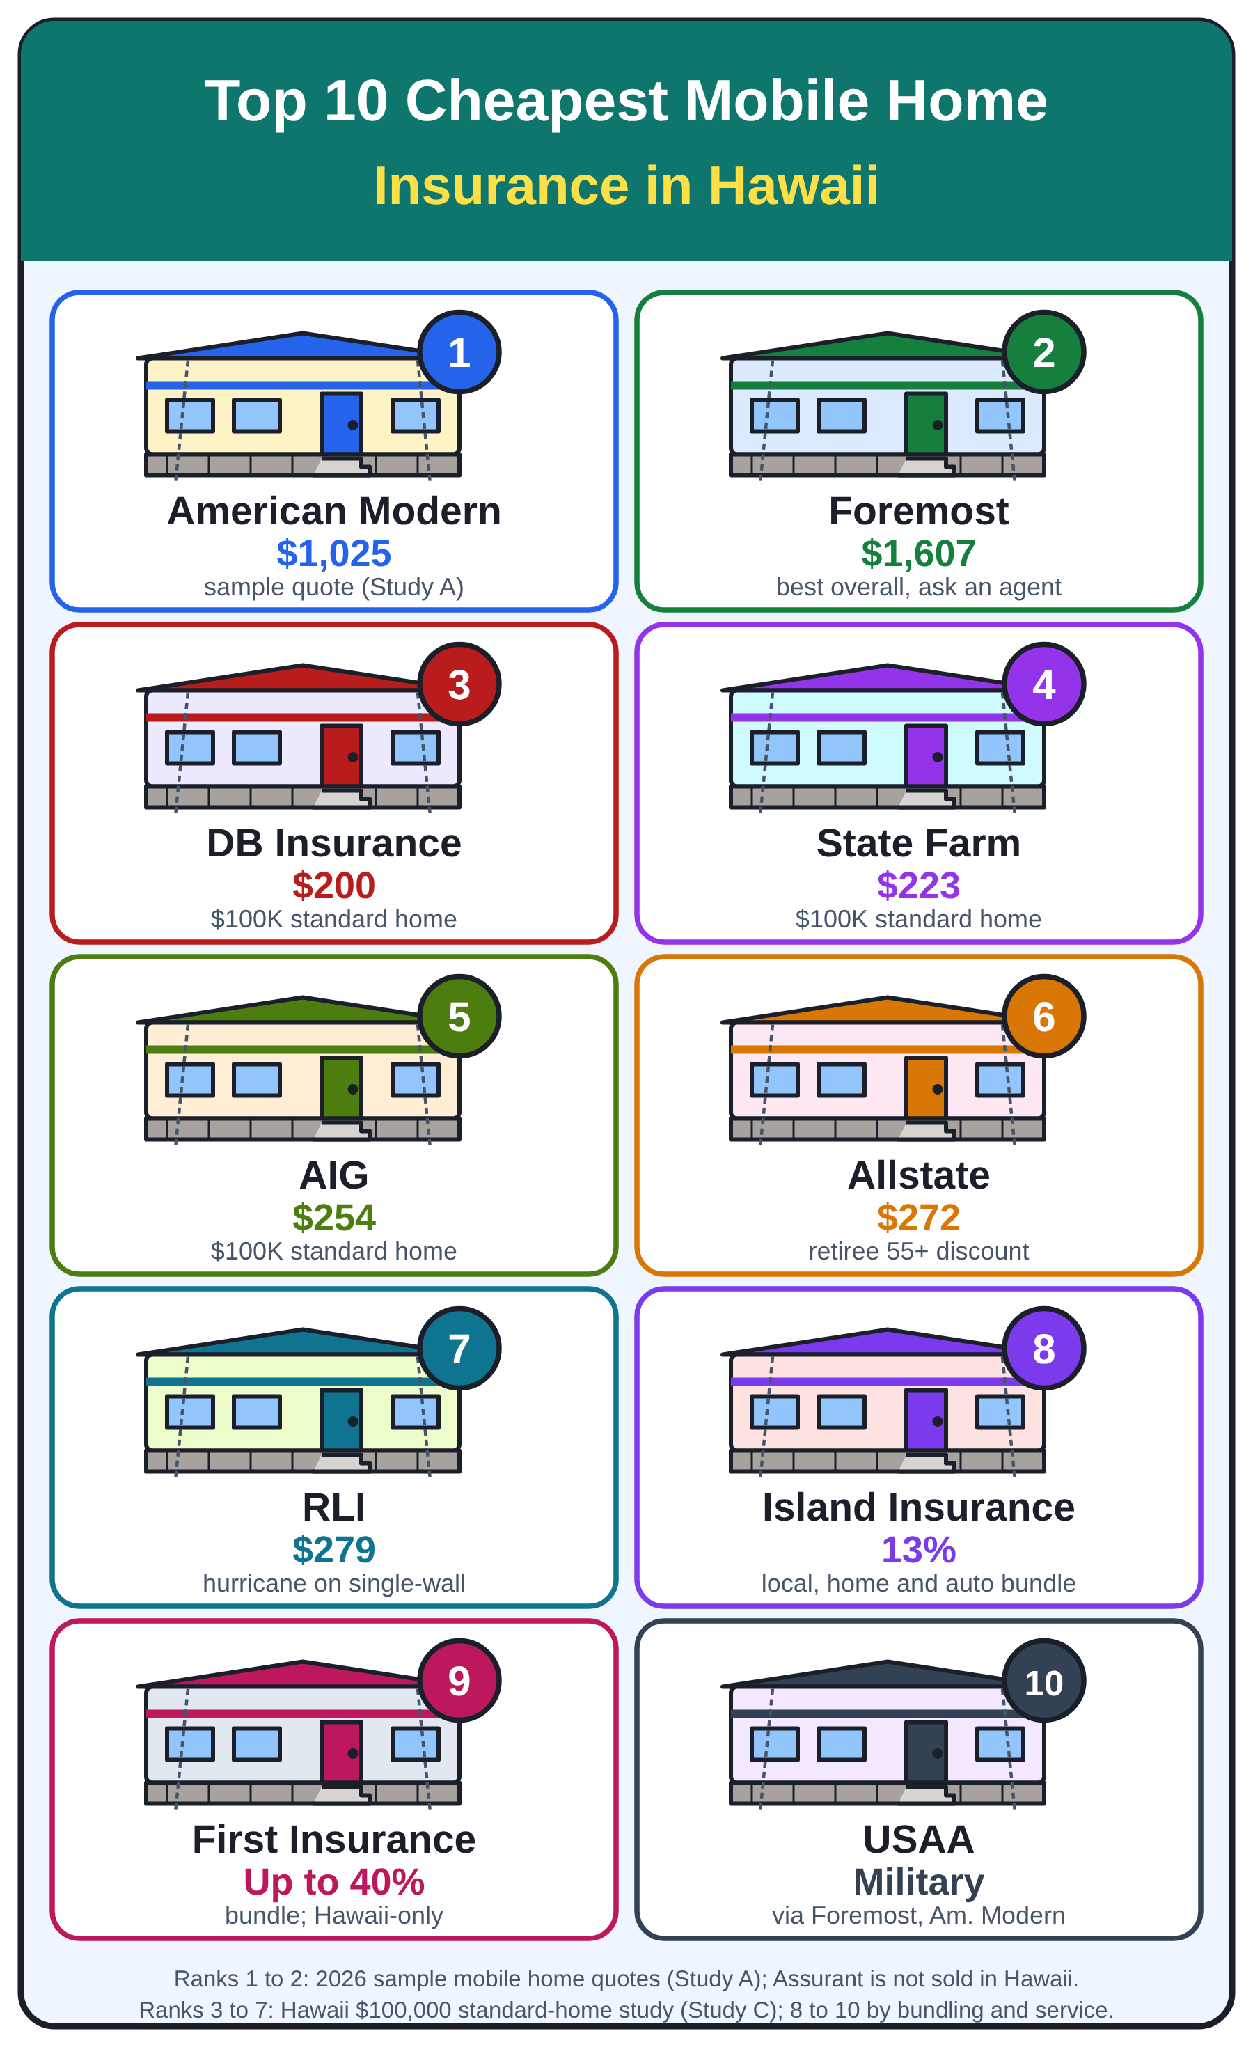
Image accuracy notice: This original graphic contains rankings or sample amounts that are not validated Hawaii manufactured-home prices. Foremost mobile-home coverage is not available in Hawaii. Rely on the corrected text and tables, not figures embedded in this image.
Original illustration retained for reference only: its numbered ranking and prices are NOT verified Hawaii manufactured-home rates, and Foremost is excluded from the Hawaii mobile-home program.
Hawaii manufactured-home insurance: contacts and eligibility checks
| Company or channel | What the published evidence actually shows | What to verify before treating it as an option |
|---|---|---|
| American Modern | Hawaii-authorized P&C entity; national manufactured-home specialist | Whether it accepts this manufactured home, island and Wind Zone III installation |
| Foremost | Official mobile-home quote program excludes Hawaii | Not a currently available Hawaii mobile-home choice in the advertised program |
| DB Insurance | Low conventional-home premium in Study C | Whether any manufactured-home policy is offered; hurricane exclusion |
| State Farm | Offers manufactured-home products in some states | Hawaii availability, construction eligibility and hurricane terms |
| Allstate | Conventional-home and specialty offerings | Hawaii manufactured-home underwriting and separate hurricane coverage |
| RLI | Hawaii homeowners and selected hurricane markets | Whether the specific manufactured structure qualifies |
| Island Insurance | Hawaii homeowners and auto markets | Mobile-home eligibility and combined policy costs |
| First Insurance Company of Hawaii | Hawaii home insurance and parametric hurricane product | Home eligibility; parametric payout is not conventional loss indemnity |
| USAA | Membership-based distribution; partners vary by state | Actual underwriting carrier and availability for a Hawaii mobile home |
| HPIA through a licensed agent | Basic property insurance for eligible hard-to-insure properties | Manufactured-home eligibility, specific limits and exclusions |
Company product pages, Foremost Hawaii exclusion, HPIA and Hawaii Insurance Division sources. Study A’s mainland sample and Study C’s conventional-home figures are not Hawaii manufactured-home quotes.
American Modern: confirm Hawaii manufactured-home eligibility
American Modern specializes in manufactured-home insurance nationally, and its group includes a property-and-casualty insurer authorized in Hawaii. Study A’s $1,025 quote was for a mainland home, not a Hawaii residence. Authorization is not proof that this product is open for new business on every island. Ask a Hawaii-licensed producer for a written eligibility check and quote under the correct policy form.
Foremost: Hawaii mobile-home program unavailable
Foremost has a long national history in mobile-home coverage, but its own mobile-home quote program states that it is available in every state except Hawaii. Its AARP manufactured-home program also excludes Hawaii. Foremost should not be recommended as a Hawaii mobile-home insurer on the evidence available; its $1,607 mainland sample premium is not a Hawaii offer.
DB Insurance: conventional-home quotes are not mobile-home quotes
DB Insurance appears with low premiums in studies of conventional houses: Study C quotes $200 for a $100,000 traditional dwelling. This does not demonstrate a manufactured-home product, and hurricane coverage can be separately underwritten or excluded. Confirm written mobile-home eligibility and total insured peril costs rather than using the $200 figure as a benchmark.
State Farm: ask about Hawaii manufactured-home underwriting
State Farm has a manufactured-home product nationally and wrote a substantial share of conventional Hawaii homeowners insurance in past market data. Study C’s $223 figure is for a $100,000 conventional home, not a manufactured home. Ask a local agent whether the specific Wind Zone III home is eligible and obtain the declaration-page hurricane deductible or any separate hurricane policy requirement.
AIG and Allstate: confirm product-specific eligibility
AIG’s $254 and Allstate’s $272 Study C premiums concern conventional houses. Neither figure establishes a manufactured-home offer, and a national complaint index does not measure the handling of Hawaii manufactured-home claims. If considering the vehicle part of a bundle, compare Allstate auto insurance options (Spanish-language review) separately from the property’s actual underwriting decision.
RLI: single-wall hurricane insurance is not proof of mobile-home eligibility
RLI’s study price concerns conventional homeowners insurance. Its Hawaii business includes insurance for certain single-wall homes, but single-wall construction is not the same classification as a HUD-code manufactured home. Confirm eligibility for the exact construction and whether wind and hurricane insurance are covered by the same policy or a separate contract.
Island Insurance, First Insurance and USAA: separate product checks
Island Insurance and First Insurance operate in Hawaii’s property market, but their home-auto discounts and event-triggered hurricane products do not establish manufactured-home eligibility. A FirstTrack-style parametric payout is triggered by stated weather criteria and does not replace conventional property-damage indemnity. Military households may separately evaluate USAA auto insurance membership rules (Spanish-language review); membership does not guarantee that a Hawaii manufactured home qualifies for coverage.
PRO TIP #1
Before comparing premiums, ask whether the quoted policy covers a HUD-code manufactured home in Hawaii, what it pays for hurricane wind, and whether a separate hurricane policy is required. A low conventional-home quote that excludes the peril or cannot insure your structure is not a cheaper manufactured-home policy.
Companies not on our list
Foremost explicitly excludes Hawaii from its advertised manufactured-home insurance program, and Progressive’s mobile-home insurance availability page also excludes Hawaii. Assurant’s national mobile-home program is not advertised for Hawaii. Do not assume that nationwide distribution, a parent company’s Hawaii license, or an auto insurer’s presence means it can underwrite a particular manufactured home. Confirm any DTRIC nonrenewal or market-exit status directly with the carrier before relying on older policy listings.
Is there a cheapest mobile home insurer in Hawaii?
No verified, like-for-like Hawaii manufactured-home premium ranking is available from the cited studies. American Modern is worth asking about because its group is authorized in Hawaii and writes manufactured homes elsewhere, but its acceptance of a specific Hawaii home is not established here. DB Insurance’s $200 conventional-house price is not a mobile-home rate. Compare written manufactured-home quotes and separate hurricane and flood costs before choosing a carrier.
Potential Hawaii insurance options by need
What to check for different Hawaii insurance needs
| Need | Where to start | Critical limitation |
|---|---|---|
| Specific manufactured-home coverage | Hawaii-licensed independent property agent; ask about American Modern | Authorization does not guarantee the product is available for that home |
| Hurricane wind | Ask for a hurricane endorsement or separate wind/hurricane market | Compare wind triggers and percentage deductibles |
| Single-wall conventional structures | Ask about RLI and other single-wall programs | A single-wall homeowners product may not cover a manufactured home |
| Hard-to-insure property | Ask about HPIA through a licensed agent | Eligibility and coverage limits must be confirmed |
| Event-based hurricane cash payment | Ask about FirstTrack parametric terms | Payout is event-based and may not equal actual property damage |
| Flood and tsunami | Obtain NFIP or suitable private flood quote | Anchoring, floodplain rules and waiting periods apply |
| Seniors and retirees | Ask each actual quoting insurer about age/retiree discounts | Discount does not prove property is eligible for a policy |
Editorial comparison of coverage channels, not a company ranking. Verify manufactured-home eligibility, policy language and premiums with a Hawaii-licensed insurance producer.
Mobile home insurance and tax considerations for Hawaii seniors
Do not assume a 50+ Foremost discount is available for a Hawaii manufactured home: Foremost excludes Hawaii from its mobile-home program. Allstate may have retiree benefits on eligible products, but the home must first qualify for an actual Hawaii policy. Separately, county real-property tax exemptions are tax benefits, not insurance premium discounts; ask the county whether your residence is assessed as qualifying real property.
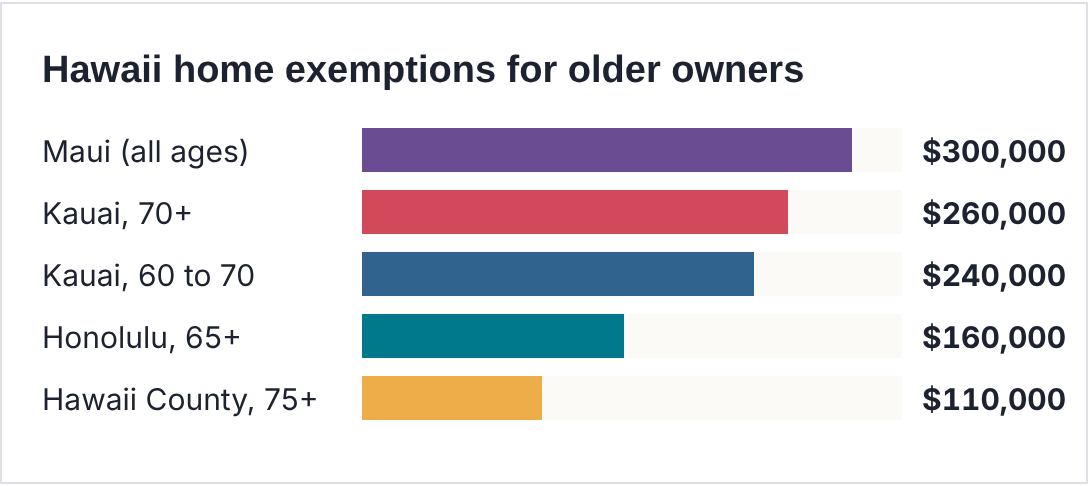
City and County of Honolulu (December 2025); Kauai County (January 2026); Hawaii County and Maui from AARP Foundation, not verified with the counties.
Senior help in Hawaii
| Program | Who qualifies | Benefit |
| Foremost mobile-home program | Not available in Hawaii | Do not assume its 50+ insurance discount applies |
| Allstate discount | Retired owners over 55 | Lower premium |
| Honolulu home exemption | 65 by June 30 | $160,000 (rising to $180,000 in 2027) |
| Kauai home exemption | Ages 60 to 70; 70+ | $240,000; $260,000 |
| Maui Circuit Breaker credit | Income up to $126,000 | Up to $8,200 |
County documents and AARP Foundation. File exemptions by September 30 in Honolulu and Kauai.
PRO TIP #2
Ask the county tax office whether your home is assessed as qualifying real property and whether you meet the primary-residence, ownership, age and filing-date rules. Honolulu’s published exemption is $160,000 for an eligible owner aged 65 or older for tax year 2026 and is scheduled to become $180,000 effective July 1, 2027. These amounts reduce taxable value, not the insurance bill.
Hurricane coverage: the key to better coverage in Hawaii
Hurricane coverage can be the decisive difference between two Hawaii home insurance offers. Depending on the policy, hurricane wind may be excluded, added by endorsement or placed in a separate contract. Before choosing a percentage deductible, examine how an insurance deductible affects a covered claim and confirm which insured value and storm trigger apply. A 2% deductible on a $100,000 insured home is $2,000 of out-of-pocket responsibility for a covered hurricane loss.
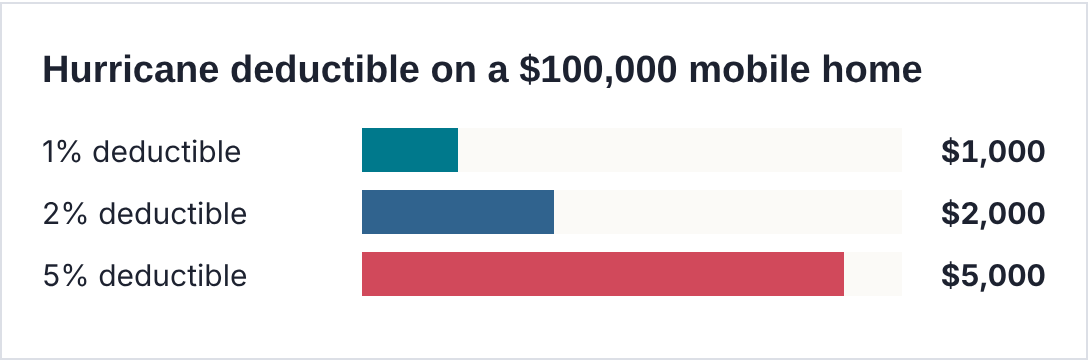
Our calculation. Hurricane deductibles usually run 1% to 5% of insured value (2026 industry guidance).
Hawaii falls in HUD Wind Zone III for manufactured-home construction. When buying or moving a HUD-code home, check its data plate and ensure its design zone and installation, foundation and anchoring meet applicable standards. The regulatory design criteria are not a guarantee that any home will survive a particular storm. Hurricane Iniki’s damage in 1992 demonstrates why wind design, anchoring and adequate insurance limits all matter.
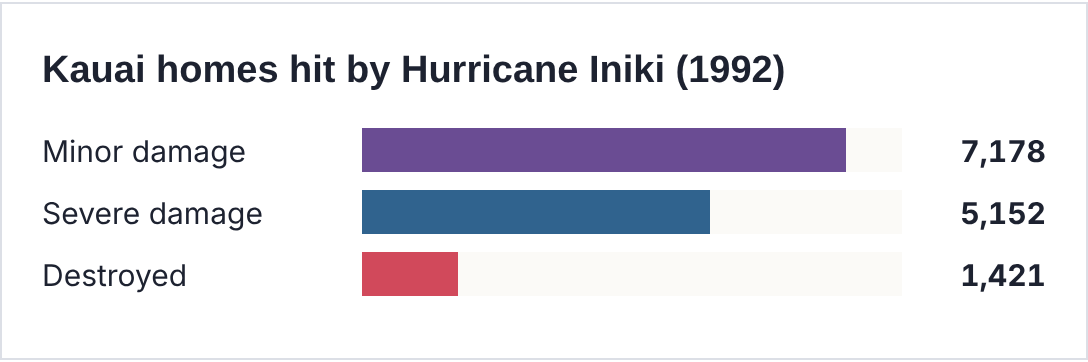
Hurricane Iniki records. Total damage about 3.1 billion in 1992 dollars.
Hawaii’s hurricane market has tightened for certain construction types, including older single-wall homes. A single-wall conventional-house product is not automatically valid for a HUD-code manufactured home. The state reactivated the Hawaii Hurricane Relief Fund for eligible condominium and townhouse association master policies, not individual manufactured-home owners or mobile-home parks. Wind and flood exclusions also matter when choosing homeowners insurance in hurricane-prone Florida, but the Florida-specific rules in that comparison do not apply to Hawaii.
Hawaii hurricane coverage options
| Option | What it means for a Hawaii manufactured-home owner |
|---|---|
| Base manufactured-home policy | Confirm whether hurricane wind is included or excluded |
| Hurricane endorsement | Available only if the issuing insurer accepts the home and offers the endorsement |
| Separate hurricane or wind policy | Confirm the building type, limits, triggers and deductible |
| Single-wall specialty coverage | May apply to some conventional construction; manufactured-home eligibility unverified |
| FirstTrack-style parametric cover | Pays under event triggers, not a reimbursement of all property damage |
| Hawaii Hurricane Relief Fund | Association master policies only under current program; not individual mobile-home policies |
Hawaii Insurance Division; Hawaii Public Radio (July 2025); company information; DCCA (January 2026).
Wildfire risk after Lahaina
The August 8, 2023, Lahaina fire was the deadliest U.S. wildfire in more than a century. It killed 102 people, damaged or destroyed 2,207 structures, 86% of them homes, and displaced about 12,000 people. Winds strengthened by Hurricane Dora, passing far to the south, drove the flames, with gusts up to 67 mph.
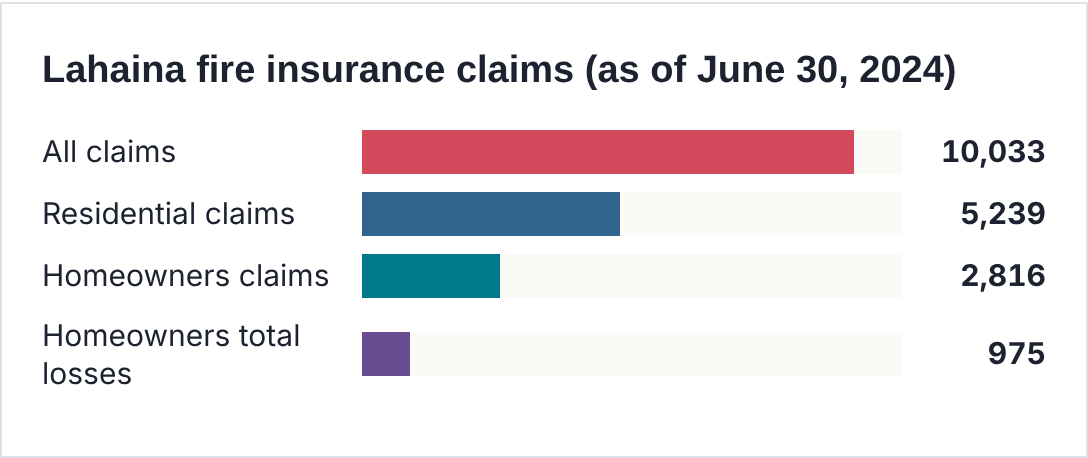
Hawaii Insurance Division data, reported by the Hawaii Tribune-Herald (July 30, 2024). Estimated losses topped 3.29 billion.
The Lahaina wildfire demonstrates why replacement cost, debris removal and additional living expenses limits matter. Even where fire is a covered peril, payment is subject to limits, exclusions and the valuation method in the policy. The widely reported wildfire settlement is a separate legal process; it is not a guaranteed insurance benefit for manufactured-home owners. Keep a current replacement-cost estimate that includes delivery and site preparation in Hawaii.
Lava zones and the Hawaii Property Insurance Association
On Hawaii Island, USGS lava-flow hazard Zones 1 and 2 create special underwriting challenges. The Hawaii Property Insurance Association (HPIA) exists to provide basic property coverage for eligible risks that are difficult to insure privately. The association is not a guaranteed insurer of every manufactured home: a Hawaii-licensed property agent must determine whether the construction, occupancy and location meet its guidelines.
HPIA’s published consumer website currently lists basic property forms with coverage limits ranging from $50,000 to $450,000. Earlier reports and proposed program expansions have quoted other amounts, but those should not be applied to today’s manufactured-home policy without a current written HPIA confirmation. Check dwelling valuation, exclusions, volcanic-loss wording and separate hurricane and flood coverage.
Hawaii Property Insurance Association basics
| Item | Verified or qualified information |
|---|---|
| Established | 1991, to serve hard-to-insure properties including lava-exposed areas |
| Primary history | Lava Zones 1 and 2 on Hawaii Island; eligibility may extend to other approved areas |
| Published property limits | HPIA website lists $50,000–$450,000 across its basic forms; confirm current form |
| Product types | Dwelling, homeowners, renters and unit owners |
| Manufactured-home acceptance | Not confirmed for all risks; ask an HPIA-authorized Hawaii property agent |
Civil Beat (October 2024); Star-Advertiser via the Garden Island (April 2026); Insurance Business (2025).
Floods, tsunamis, and earthquakes
Flooding can threaten homes across Hawaii, including away from mapped high-risk areas. One 2026 public report estimated that only a small share of properties had federal flood insurance, but the figure should not be read as a manufactured-home-specific coverage rate. Review current FEMA flood maps and the home’s site elevation and anchoring rather than relying only on statewide percentages.
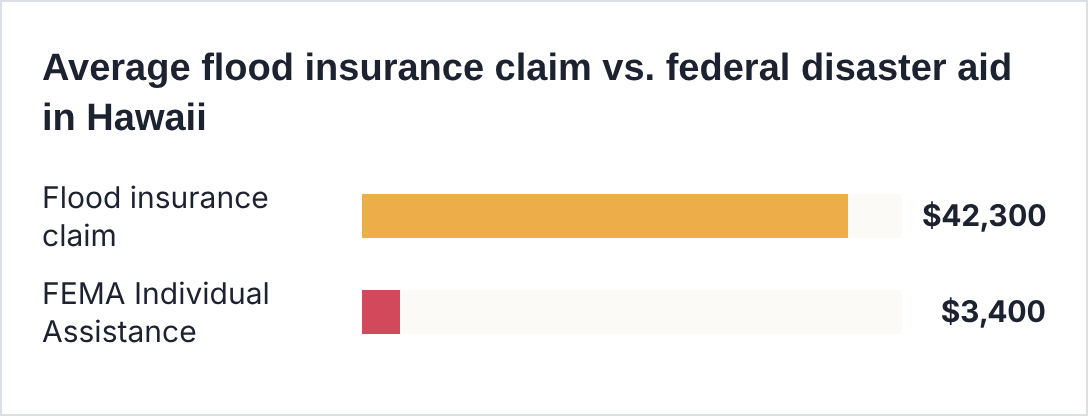
FEMA data reported by KHON2 (March 12, 2026), 10-year averages.
The National Flood Insurance Program can cover an eligible manufactured home subject to anchoring, floodplain and policy conditions. Standard residential limits are up to $250,000 for the building and $100,000 for contents; tsunami inundation can qualify as flood damage under the policy wording. Many new NFIP contracts have a 30-day waiting period, subject to exceptions. A separate discussion of wind and flood coverage choices for Florida homeowners illustrates why separating perils matters, although Hawaii policy terms must be checked independently.
Coverage for other Hawaii natural risks
| Risk | Covered by standard policy? | Where to get it |
| Hurricane | Usually not | Endorsement or separate policy |
| Wildfire | Yes | Standard policy |
| Lava | Some damage covered; limits apply | Standard policy or HPIA |
| Flood and tsunami | No | Federal flood insurance |
| Earthquake | No | Optional add-on |
FEMA; Hawaii Insurance Division; a July 2026 Hawaii homeowners study.
PRO TIP #3
Request flood insurance well ahead of hurricane season, when possible, because many new NFIP policies are subject to a 30-day waiting period. Do not assume that a flood policy begins immediately or that it covers earthquake shaking. Ask about the policy’s actual effective date and anchoring requirements.
Hawaii mobile home insurance by island
Main risks and coverage needs by island
| Island | Main risk | What to check |
| Oahu | Flooding and new flood maps | Flood insurance; hurricane deductible |
| Maui | Wildfire and Kona storm flooding | Fire limits; brush clearing; flood insurance |
| Hawaii Island | Lava, earthquakes, and floods | Lava zone; HPIA; earthquake add-on |
| Kauai | Hurricanes, as in Iniki | Hurricane coverage; Wind Zone III anchoring |
Our assessment, based on FEMA, USGS, and Hawaii Insurance Division information.
Why Hawaii home insurance costs are rising
Hawaii’s conventional homeowners insurance market has seen substantial approved increases and tighter underwriting in recent years. Company-specific rate filings and statewide written-premium totals do not establish how much manufactured-home insurance premiums increased. Track the total price of the actual manufactured-home, hurricane and flood policies at renewal rather than comparing unrelated statewide house averages.
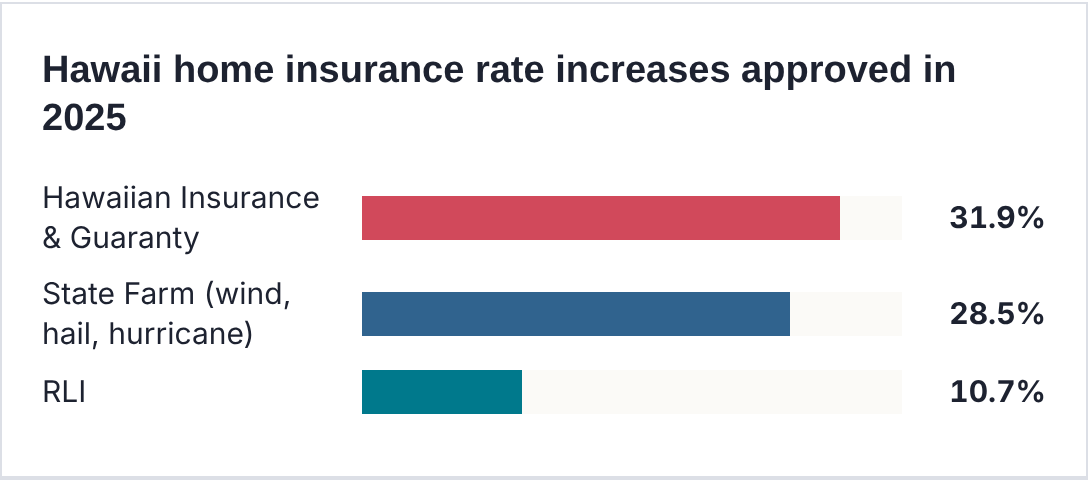
Insurance Business (January 22, 2026). State Farm maximum: 48.4%.
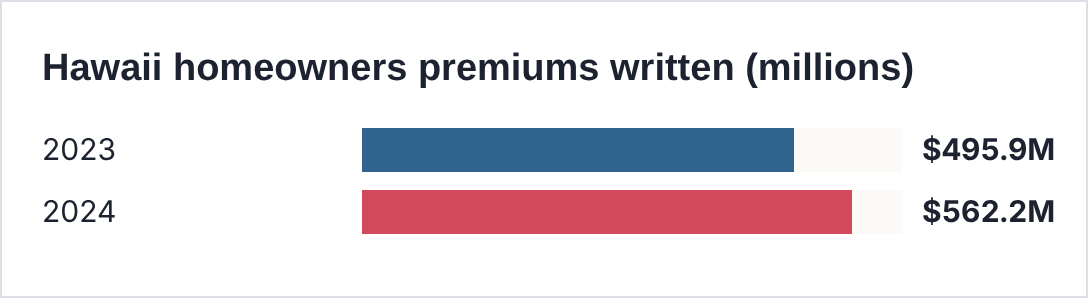
2025 Annual Report of the Hawaii Insurance Commissioner.
Hawaii legislation broadened tools available to address difficult property-insurance markets. The revived Hurricane Relief Fund currently focuses on eligible condominium and townhouse association master policies, rather than an individual manufactured-home policy. HPIA has distinct eligibility and underwriting rules; verify both programs directly rather than treating them as interchangeable.
What Hawaii mobile home insurance covers
Main coverage parts of a Hawaii mobile home policy
| Coverage | What it pays for |
| Dwelling | Repairs or replacement of the home |
| Other structures | Carports, lanais, sheds, and skirting |
| Personal property | Furniture, clothes, and belongings |
| Loss of use | Living costs after a covered loss |
| Personal liability | Injuries or damage you cause to others |
| Not usually covered | Hurricane wind may require a separate policy; flood, tsunami inundation and earthquake typically need separate coverage |
Company policy descriptions; coverage varies by insurer.
How to check an insurer’s service record
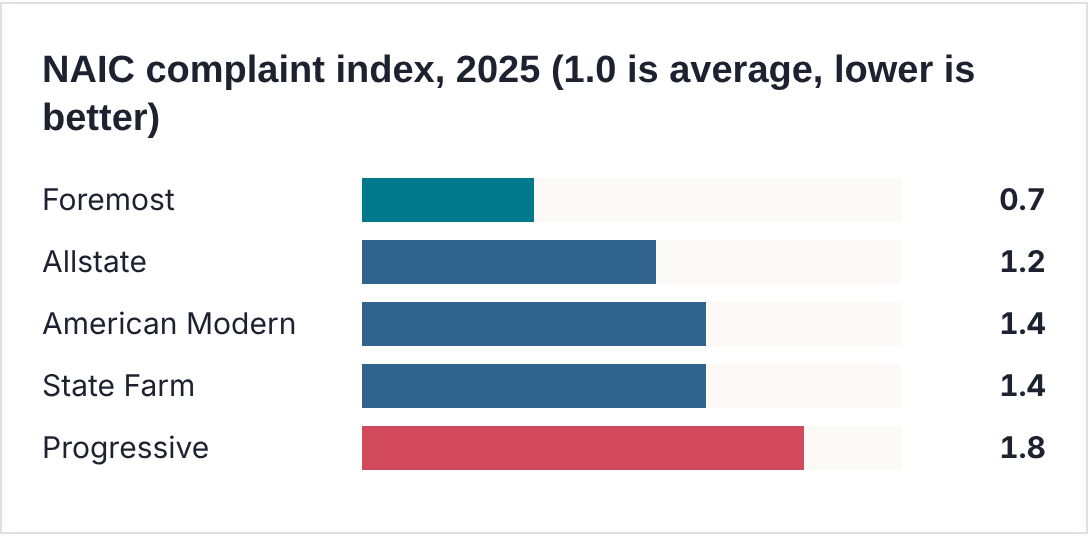
NAIC complaint index for 2025, as reported in a national mobile home review updated September 15, 2026. Hawaii insurers such as DB, Island, and First Insurance were not included.
Bundling mobile home and auto insurance in Hawaii
The cited home-auto bundle savings come from conventional-house policies, not Hawaii manufactured-home quotes. A carrier might discount auto coverage while declining to insure the manufactured home. Before counting on a combined premium, check multi-policy discounts on the auto insurance side and obtain written confirmation that the property qualifies.
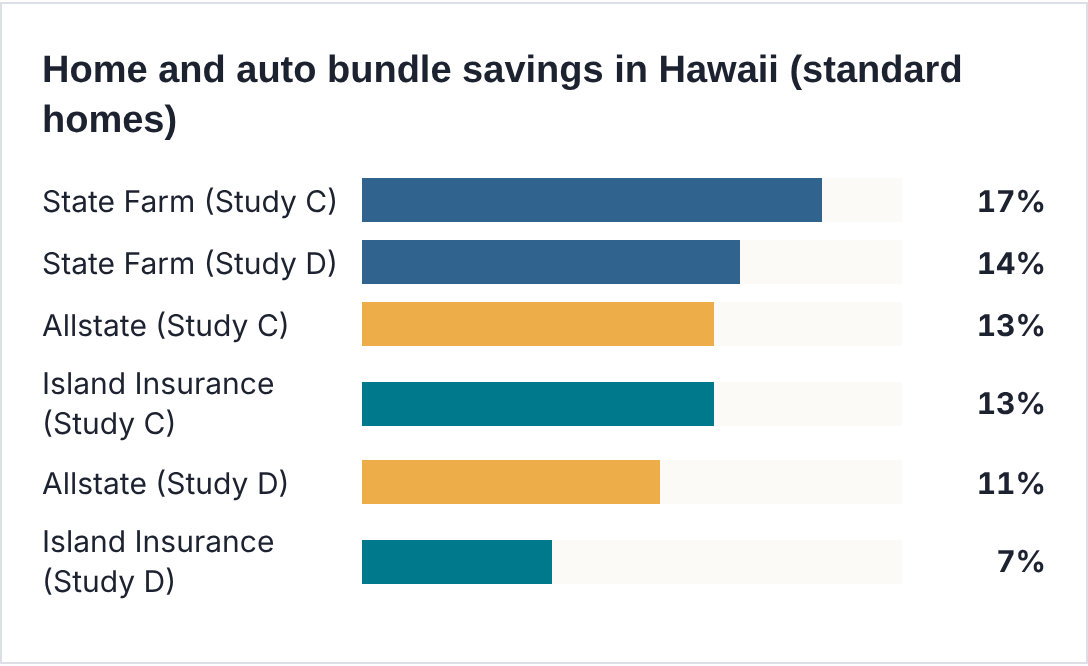
Study C (September 17, 2026); Study D (April 22, 2026). Standard homes, not mobile homes.
Mobile home insurance discounts in Hawaii
Discounts to ask for in Hawaii
| Discount | Who offers it |
| Age 50+ or retired 55+ | Foremost (50+); Allstate (retired, over 55) |
| Newer home | Foremost, State Farm |
| Claims-free | American Modern, Allstate |
| Paid in full | American Modern |
| Loyalty at renewal | First Insurance (up to 11%) |
| Multi-policy | Most insurers |
Company websites and reviews (2023 to 2026). Discount amounts vary.
How much coverage you need
Begin with the replacement cost of a comparable HUD-code manufactured home meeting Hawaii wind and installation requirements. Include delivery, labor, site preparation, anchoring, debris removal and applicable code upgrades where insured, but exclude land value. Then compare dwelling, personal property, liability and additional living expenses coverage to ensure the limits could support a lengthy relocation and repairs.
Tips for better coverage at lower rates in Hawaii
- Compare at least three quotes, including American Modern, Foremost, and a local insurer.
- Ask whether each quote includes hurricane coverage, and compare the full cost.
- Choose a hurricane deductible you could pay, usually 1% to 5%.
- Confirm your home meets Wind Zone III anchoring rules.
- Buy flood insurance, which also covers tsunamis, at least 30 days ahead.
- Ask for senior, claims-free, and multi-policy discounts.
- File for your county’s home exemption if your home is real property.
- Shop again every year, since rates are rising.
What to do after a storm, fire, or flood
- Get to safety, then call your insurer or agent as soon as you can.
- Take photos and video of all damage before cleaning up.
- Make temporary repairs and keep the receipts.
- If you have a problem, call the Hawaii Insurance Division at (808) 586-2790.
Hawaii mobile home insurance at a glance
This illustrated summary pulls together the main points of this guide.
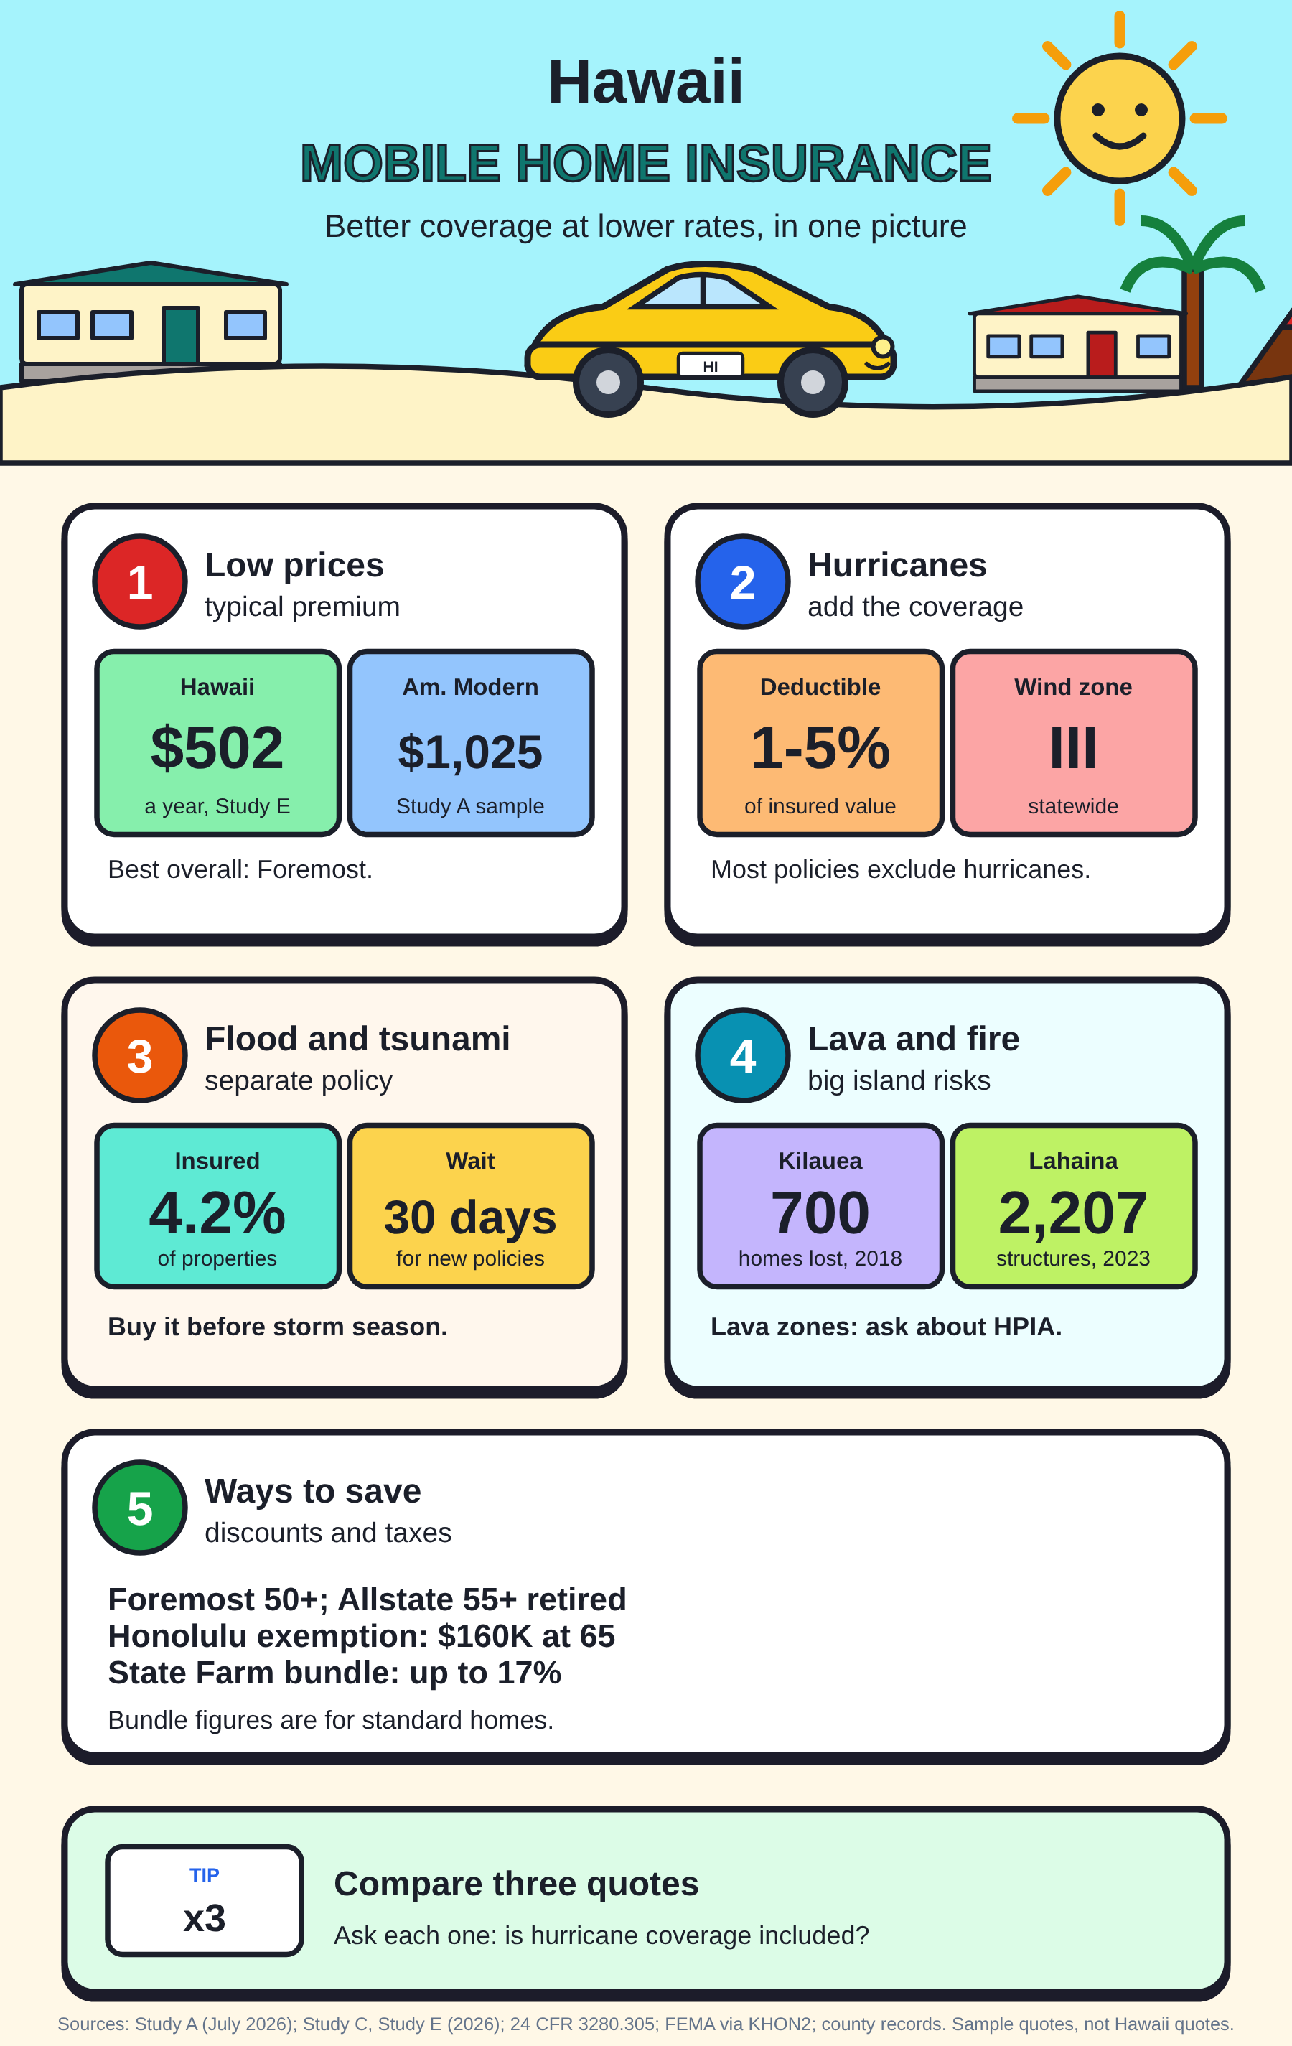
Image accuracy notice: This original graphic contains rankings or sample amounts that are not validated Hawaii manufactured-home prices. Foremost mobile-home coverage is not available in Hawaii. Rely on the corrected text and tables, not figures embedded in this image.
Hawaii mobile home insurance at a glance. Sources: Study A; Study E; 24 CFR 3280.305; FEMA; county records.
Frequently asked questions about Hawaii mobile home insurance
How much is mobile home insurance in Hawaii?
A third-party state table gives about $502 a year, but it does not publish enough details to confirm a representative Hawaii manufactured-home premium. Request a quote for your home’s location, age, wind certification, insured value and hurricane coverage.
Who has the cheapest mobile home insurance in Hawaii?
There is no verified cheapest manufactured-home insurer for Hawaii in the cited studies. American Modern’s mainland sample was $1,025, while DB Insurance’s $200 figure was for a conventional house. Neither is a confirmed Hawaii manufactured-home quote.
What is the best mobile home insurance company in Hawaii?
A single best company cannot be substantiated without comparable Hawaii manufactured-home quotes and confirmation of eligibility. Foremost’s advertised mobile-home program excludes Hawaii. Start with a licensed local property agent and request offers from insurers that confirm acceptance of your actual home.
Does mobile home insurance cover hurricanes in Hawaii?
Hurricane wind may be included, excluded or insured separately, depending on the company and policy form. Confirm the written hurricane terms and deductible before binding coverage.
Is Assurant available in Hawaii?
Assurant does not advertise its standard mobile-home program for Hawaii in the national availability information reviewed. Confirm any nonstandard or affiliated program directly with a licensed Hawaii agent rather than assuming national brand availability.
Does flood insurance cover tsunamis in Hawaii?
Eligible direct physical flood damage caused by tsunami water can be covered under an NFIP policy, subject to flood definitions, deductibles and other conditions. A 30-day waiting period commonly applies to new NFIP policies, with exceptions.
The final word on Hawaii mobile home insurance
Hawaii manufactured-home insurance cannot be ranked reliably from the published conventional-home averages and mainland sample quotes used in this article. Foremost’s mobile-home program excludes Hawaii, and other national or local insurers must confirm eligibility for the particular manufactured home. Work with a Hawaii-licensed property producer, obtain comparable written offers and check the full cost of hurricane and flood protection.
Before buying, verify HUD Wind Zone III and anchoring requirements, compare insured values and deductibles, request hurricane and flood terms in writing, and assess available government or private last-resort property options only after confirming eligibility. A policy that cannot cover your home or a major local peril is not a useful low-price comparison.
Sources
- Foremost official manufactured-home availability (excludes Hawaii)
- Foremost/AARP availability disclaimer
- Hawaii Property Insurance Association — published coverage limits
- Hawaii Hurricane Relief Fund — association master-policy eligibility
- Hawaii Insurance Division — hurricane preparedness and coverage
- 24 CFR 3280.305 — manufactured housing Wind Zone III
- Hawaii independent agency advertising mobile-home insurance
- Hawaii county home exemption rules (Honolulu)
- Study A: ValuePenguin, mobile home insurance (July 6, 2026).
- Study B: ValuePenguin, cheap homeowners insurance in Hawaii (September 25, 2026).
- Study C: MoneyGeek, cheap homeowners insurance in Hawaii (October 1, 2026), and best home and auto bundle in Hawaii (September 17, 2026).
- Study D: Insurance.com, cheap homeowners insurance in Hawaii (September 30, 2026), and cheapest home and auto bundle in Hawaii (April 22, 2026).
- Study E: Insuranceopedia, mobile home insurance by state (October 18, 2026).
- NerdWallet, Hawaii homeowners insurance (March 16, 2026); LendingTree, Hawaii homeowners insurance (July 16, 2026); and LendingTree, best mobile home insurance companies (September 15, 2026).
- Foremost, about; AARP, Foremost mobile home program; Policygenius, American Modern review; Policygenius, Assurant review; Policygenius, First Insurance review; RLI, Hawaii homeowners; State Farm, manufactured homes; USAA, mobile home; and Finder, Allstate review.
- Hawaii Public Radio, non-renewals (July 2025); Hawaii News Now, DTRIC (October 2025); Insurance Business, rate increases (January 2026); S&P Global, State Farm market share (2023); and 2025 Annual Report of the Insurance Commissioner.
- State of Hawaii Data Book 2024, Table 21.17; DBEDT, 2019 state rankings; UH News, Hawaii Housing Factbook (May 2026); Maui Now, Kilohana temporary homes (February 2025); and HB 1719 status.
- 24 CFR 3280.305; Hurricane Iniki; Hawaii Life, home insurance changes (July 2026); Hawaii Insurance Division, hurricane FAQ; DCCA, Hurricane Relief Fund; and DCCA, Act 296 (July 2025).
- ABC News, Lahaina fire; Maui Now, structures damaged (August 2023); Hawaii Tribune-Herald, fire claims (July 2024); Hawaii News Now, settlement payments (April 2026); and Lead Stories, Hurricane Dora winds (August 2023).
- 2018 lower Puna eruption; Civil Beat, lava zone insurance (October 2024); Garden Island, Hurricane Relief Fund and HPIA (April 2026); and Insurance Business, Act 296 (July 2025).
- KHON2, flood insurance (March 2026); Guy Carpenter, March 2026 floods; DisasterAware, Kona lows (March 2026); FEMA, tsunamis and flood insurance; Marine Technology News, 2025 tsunami; 2006 Kiholo Bay earthquake; and Insurance Journal, earthquake coverage (2006).
- Honolulu, home exemption (December 2025); Kauai County, real property taxes (January 2026); AARP Foundation, Hawaii property taxes; Locations Hawaii, 2027 exemptions; and Hawaii Insurance Division, contact.
Disclaimer
This website provides independent reviews and comparisons. It is not affiliated with, endorsed by, sponsored by, or connected to American Modern, Foremost, Farmers, DB Insurance, State Farm, AIG, Allstate, RLI, Island Insurance, First Insurance Company of Hawaii, USAA, Assurant, Universal Insurance, Tokio Marine, Hawaiian Insurance & Guaranty, DTRIC, the Hawaii Property Insurance Association, the Hawaii Hurricane Relief Fund, or any of their affiliates.
All company names, brand names, trademarks, and logos are the property of their respective owners and are used here only to identify the companies being reviewed. Their use does not imply any affiliation or endorsement.
The information on this page is provided for general informational and educational purposes only. It is not insurance, legal, tax, or financial advice, and it is not an offer, quote, or solicitation to buy or sell insurance. We are not an insurance company, insurance agency, or licensed insurance producer, and we cannot bind coverage, change a policy, or handle claims.
Prices, discounts, ratings, and company details are drawn from public sources and third-party studies that use specific home profiles, and they can change at any time. They are estimates and averages, not guarantees of what you will pay. Coverage, eligibility, and discounts vary by location, home, and owner, and are subject to each insurer’s underwriting rules and policy terms.
While we make reasonable efforts to keep this guide accurate and current, we make no representations or warranties, express or implied, about its completeness, accuracy, or reliability. Opinions here are our own. Always confirm details directly with the insurer, read your policy documents, and consult the Hawaii Insurance Division or a licensed professional before making a decision. Your use of this information is at your own risk, and we are not liable for any loss or damage arising from reliance on it.