
Buy Now Pay Later Car Insurance: How It Really Works
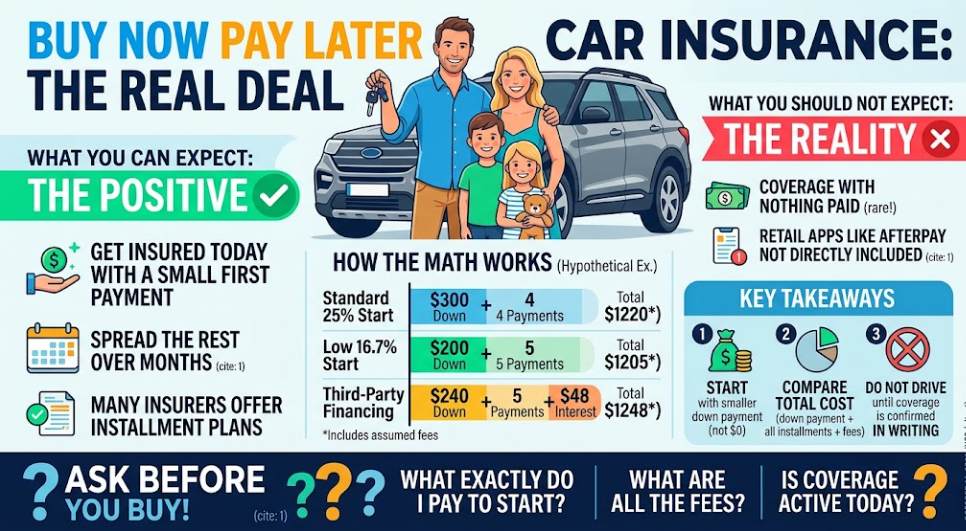
Most people searching for buy now pay later car insurance want one thing: to get insured today with a small first payment and spread the rest of the cost over the coming months. The good news is that many insurers make this possible through installment plans, where you pay part of the premium to start and the remainder in scheduled payments.
What you should not expect is coverage with nothing paid at all. Insurers generally collect a first payment before a policy takes effect, and retail "buy now, pay later" apps such as Klarna or Afterpay are not built into most auto insurers' checkouts. This guide explains the real options, what each one costs, and exactly what to ask before you buy.
KEY TAKEAWAYS
- What the term usually means: starting a policy with a smaller first payment and paying the rest in installments, not getting coverage for free.
- What to verify: the exact amount due before coverage begins, plus the total of all payments, fees included.
- Safest next step: compare several quotes with identical coverage, and do not drive until the insurer confirms your policy's effective date in writing.
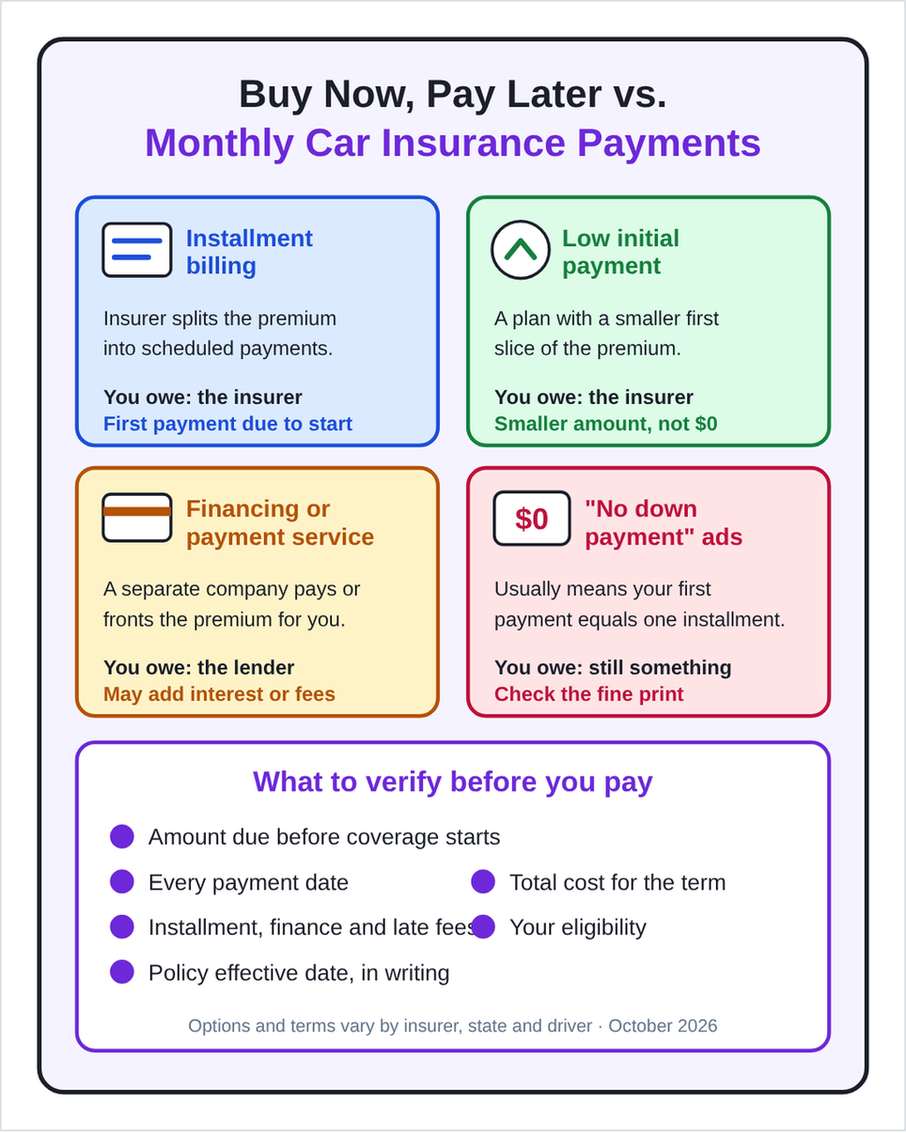
The four arrangements people usually mean by "buy now, pay later" car insurance, and the six details to confirm before paying for any of them.
What is buy now pay later car insurance?
Buy now pay later car insurance is not a formal type of policy. It is a phrase people use for any arrangement that lets them start coverage without paying the full premium upfront. The premium is the total price of your policy for its term, usually six or twelve months.
The phrase gets used loosely. An insurer may use it to describe monthly billing, a lender may use it for premium financing, and an ad may use it to suggest coverage with no money down. Those are very different deals, so it pays to know which one you are looking at.
Five arrangements people call "buy now, pay later"
| Arrangement | What it generally means | What to verify | Is nothing due before coverage starts? |
|---|---|---|---|
| Standard installment billing | The insurer divides your premium into scheduled payments | Number of payments, due dates and per-installment fees | No. A first installment is normally due on the effective date |
| Low initial payment | A plan whose first payment is a smaller share of the premium | The exact dollar amount due to start and how it changes later payments | No. It is smaller, not zero |
| Deferred payment | A payment is postponed to a later date under specific terms | Who offers it, when it comes due, and what happens if it is missed | Only if the written terms say so; confirm before relying on it |
| Third-party financing or payment service | A separate company pays or fronts the premium, and you repay it | The provider, interest rate, fees, repayment schedule, and credit check | Not necessarily. Lenders often require their own down payment |
| No-down-payment claim | Marketing language that usually means the first payment equals one installment | Whether any amount is due today, and how much | Rarely. Ask for the amount due in writing |
General descriptions. Availability and terms depend on the insurer, the state, the driver, and any separate payment provider.
Can you get car insurance now and pay later?
Yes, in the sense that most drivers can start a policy with a partial payment and pay the rest over time. What varies is how small that first payment can be. Some insurers publish their plans; most expect you to ask.
GEICO, for example, publishes plans for new policies that start with 25% of the premium on a five-payment schedule, or 20% on the same schedule with automatic payments. Progressive Direct‘s installment plans filed in Massachusetts show down payments from 16.7% to 30%, depending on the plan and the company’s risk criteria. Dairyland, an insurer focused on drivers with varied records, advertises “flexible payment plans” and “low down payments” without publishing amounts.
Retail buy-now-pay-later apps are different. One insurance agency's 2026 guide says no major U.S. auto insurer has a direct partnership with Afterpay, and that workarounds using one-time virtual cards cannot support recurring payments. Klarna's own merchant rules list insurance as a "restricted" business, meaning it is allowed only after extra review.
Questions to ask before you agree to any plan
- What exact amount must I pay before the policy becomes effective?
- Is that amount a down payment, first installment, deposit, fee, or financed amount?
- When is the next payment due, and how many payments are there?
- Are there installment, processing, finance, or late fees?
- Does the insurer or any separate payment provider run a credit check?
- What happens if a payment is late or declined?
- Who services the payment plan: the insurer or another company?
- Will you confirm the policy's effective date in writing?
How to find car insurance with a low initial payment
The aim is the smallest first payment you can afford today, on a policy whose total you can also afford. Follow these steps in order.
- 1. Get quotes from at least three insurers.
- 2. Request identical coverage on every quote. Use the same liability limits, deductibles, drivers, and policy term so the prices are comparable.
- 3. Ask which payment plan needs the least money to start. The first plan you are shown may not be the one with the smallest first payment.
- 4. Check the installment schedule and fees. Write down every due date and any charge added to each payment.
- 5. Compare the total policy cost. Add the first payment, every later installment, and every fee.
- 6. Confirm the effective date before you pay. Make sure coverage starts no later than the day you need to drive, and no later than the day an old policy ends.
Insurers and payment options: what can actually be verified?
Few companies publish their first-payment rules, so this comparison is short on purpose. We list only terms published on official pages, with insurers and payment services kept separate.
Insurance companies: verified payment terms
| Insurer | Arrangement verified | Initial payment documented | Fees documented | Limits | Source and date |
|---|---|---|---|---|---|
| GEICO | Pay in full or 2 to 6 installments | 25% on 5-pay plan for new policies; 20% with Auto Pay | Installment fee may apply; EFT fee drops from up to $5 to $1 in most states | Some plans not available in all states | GEICO payment plans page, accessed Oct. 14, 2026 |
| Progressive Direct | 5 or 6 installments | 16.7% to 30%, depending on plan and risk criteria | $5 or $8 per installment ($1 or $4 with EFT); $25 late fee; $25 returned-payment fee | Filed for Massachusetts; other states may differ | Mass.gov installment plan filing, accessed Oct. 14, 2026 |
| Dairyland | "Flexible payment plans" and "low down payments" | Not publicly confirmed | Not published; pay in full or quarterly may lower cost | Terms vary by state and policy | Dairyland auto page, accessed Oct. 14, 2026 |
Payment services: what their own terms say about insurance
| Provider | Type of company | What it says about insurance | What this means for you | Source and date |
|---|---|---|---|---|
| Klarna | Buy-now-pay-later payment service, not an insurer | Lists insurance as a "restricted" business that may need extra review before approval | You can use it only if your insurer is approved to accept it; ask first | Klarna merchant policy, accessed Oct. 14, 2026 |
We found no official insurer page confirming a direct partnership with a retail BNPL app for auto premiums. Absence of a published page does not prove no such arrangement exists anywhere; ask your insurer.
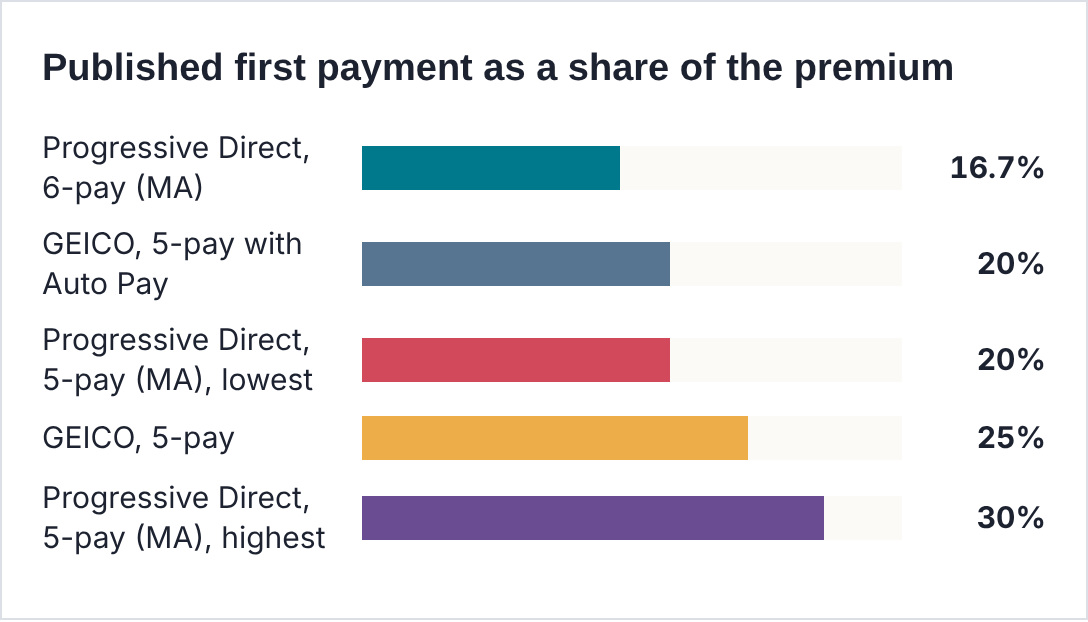
Percent of the total premium due at the start. GEICO: published plans for new policies, accessed October 14, 2026. Progressive Direct: Massachusetts installment plan filing, accessed October 14, 2026; the 5-pay percentage depends on company risk criteria. Not a price comparison.
What does car insurance cost, and what will you pay upfront?
Nationally, full coverage averages about $208 a month and minimum liability about $76, according to a rate analysis updated October 1, 2026. Your price depends on your state, ZIP code, record, age, vehicle, coverage, and, in most states, credit-based insurance score.
National average car insurance cost, 2026
| Coverage | Average monthly cost | Average yearly cost | What it covers |
|---|---|---|---|
| Minimum liability | $76 | $908 | Injuries and property damage you cause to others, at your state's legal minimum |
| Full coverage | $208 | $2,495 | Liability plus collision and comprehensive coverage for your own car |
National averages from a rate analysis updated October 1, 2026. The source does not publish its driver profile for these figures. A national average is not your state's average and is not a quote.
Five money terms that are easy to mix up
- Total premium: the full price of the policy for its term.
- Amount required to start: what you pay before the insurer makes the policy effective.
- Installments: the later scheduled payments.
- Fees or finance charges: extra costs for paying over time, paying late or borrowing.
- Deductible: what you pay out of pocket on a covered claim. It is not part of your first premium payment.
Is buy now pay later insurance more expensive?
Not automatically. Insurer installment plans may add only a few dollars, while borrowing with interest can add more. The only fair test is the total you pay over the same term.
The hypothetical example below uses a $1,200 six-month premium. It applies GEICO's published 25% first payment, Progressive Direct's published 16.7% six-pay plan with its $1 electronic transfer fee, and an invented financing deal at 20% APR with 20% down. None of these totals is a real offer.
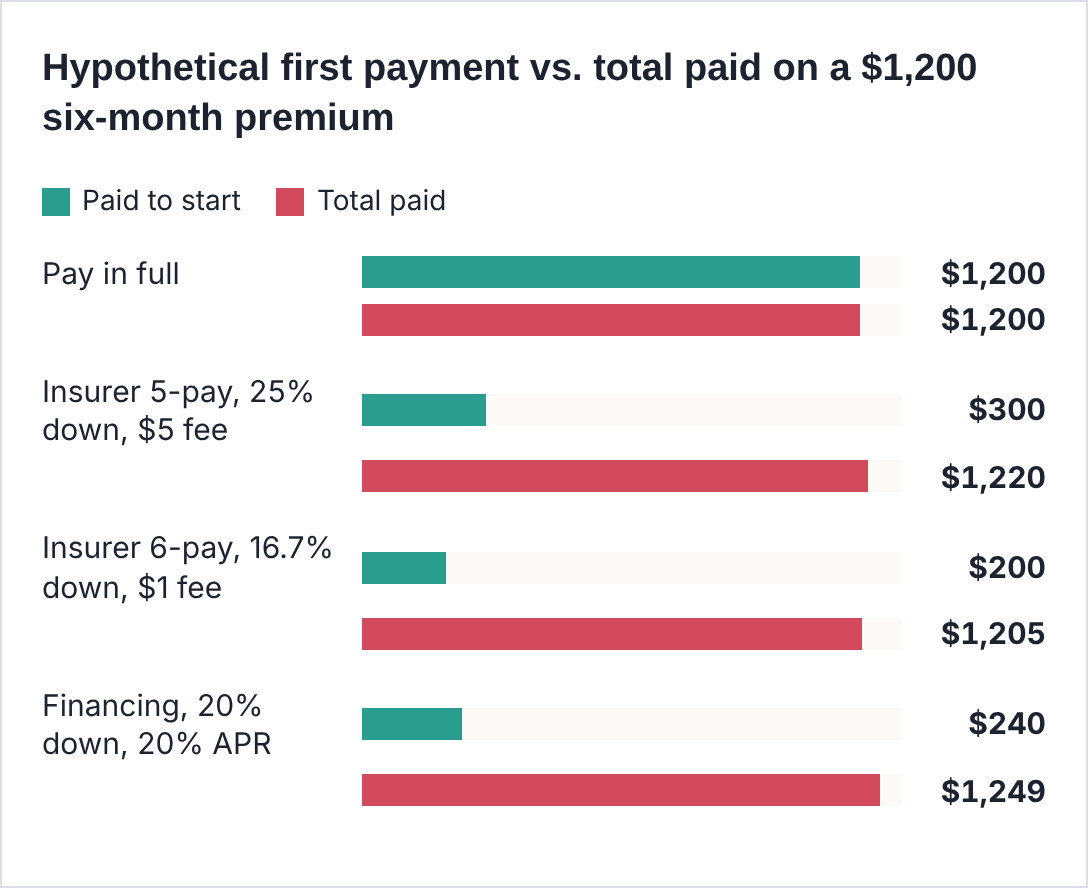
Hypothetical example calculated by us. First-payment percentages for the insurer plans come from GEICO and Progressive Direct (Massachusetts) published terms; the premium, fee assumptions and financing terms are invented for illustration and are not real offers.
Hypothetical comparison of four ways to pay a $1,200 premium
| Option | Paid to start | Later payments | Fees or interest | Total paid |
|---|---|---|---|---|
| Pay in full | $1,200 | None | $0 | $1,200 |
| Insurer 5-pay plan, 25% down | $300 | 4 × $225 | $20 (4 × $5, assumed) | $1,220 |
| Insurer 6-pay plan, 16.7% down | $200 | 5 × $200 | $5 (5 × $1 EFT, assumed) | $1,205 |
| Third-party financing, 20% down | $240 | 5 × $201.71 | $48.53 interest (20% APR, assumed) | $1,248.53 |
All figures are hypothetical and rounded to the cent; we calculated them. The financing row assumes $960 borrowed at 20% APR over five monthly payments.
Here the six-pay plan has the smallest start and nearly the lowest total, but that will not always hold. A lower first payment does not guarantee a lower total.
Practical options if you cannot afford a large first payment
A small start is often possible, but the exact amount depends on the insurer, your state, your record, your coverage, and the payment terms. These steps give you the best chance of finding one.
Where to start when cash is tight
| Option | How it helps | What to check first |
|---|---|---|
| Ask for the minimum amount to activate a policy | Reveals plans with a smaller first payment than the default quote | That the amount is written on the quote, not just said on a call |
| Compare quotes with identical coverage | Shows real price differences instead of coverage differences | Same limits, deductibles, drivers and term |
| Ask about every billing schedule | Plans with more payments usually start smaller | Fees per payment and the total cost of each plan |
| Ask about discounts | A lower premium lowers every payment, including the first | Proof you may need, such as grades or a course certificate |
| Review deductibles and optional coverage | Can lower the premium on an older, paid-off car | Do not drop legally required coverage or coverage your lender requires |
| Quote a different vehicle before buying it | Some models cost much less to insure | Get actual quotes rather than relying on averages |
| Talk to the insurer before using outside financing | Insurer plans often cost less than borrowing | Interest rate, fees, and late-payment rules of any lender |
Vehicle choice can matter more than people expect. In the October 2026 analysis, a Subaru Crosstrek averaged $211 a month for full coverage, and a Tesla Model 3 averaged $358. If you are about to buy a car, quote it first.
If you consider a premium finance company or a payment service, read the full repayment terms first: the interest rate, every fee, what happens after a late payment, and whether payments are reported to credit bureaus. The Federal Trade Commission warns that some buy-now-pay-later plans charge high late fees and that some report missed payments to the credit bureaus.
State insurance rules and keeping coverage active
Minimum coverage requirements are set by each state, so check yours. Most states require liability insurance at set minimums. For example, California requires 30/60/15, Georgia 25/50/25, Texas 30/60/25, and Massachusetts 25/50/30, meaning thousands of dollars per person injured, per accident, and for property damage. Some states require additional coverages.
"Full coverage" is a common phrase, not one standard policy. It usually means liability plus collision and comprehensive coverage for your own car. If you finance or lease, your lender will usually require it.
Driving without required insurance can bring fines, registration or license suspension and personal responsibility for crash damage, with penalties that vary by state. Missing an installment can also end your policy. In California and Georgia, for instance, state law lets an insurer cancel for nonpayment with as little as 10 days' notice. This is general information, not legal advice.
PRO TIP #1: COMPARE THE AMOUNT DUE TODAY WITH THE TOTAL COST
Make a four-line note for every quote: amount due today, number of payments, fee per payment, and total of all payments. Then divide the total by the number of months in the term. That single "true monthly cost" lets you compare a quote with a $200 start against one with a $300 start fairly. Insurers present plans differently, and this is the only way to line them up.
What can change the first payment?
Your first payment is usually a percentage of the premium, so anything that changes the premium changes the first payment. The percentage itself is set by each insurer's billing rules.
General principles
- Premium size. Your record, location, vehicle, and coverage set the price that the first payment is drawn from.
- Policy term. A six-month policy has a smaller premium to divide than a twelve-month policy.
- Payment schedule. More installments usually mean a smaller share due upfront.
Company-specific practices
- Billing rules. GEICO and Progressive Direct publish different percentages for similar plans.
- Risk criteria. Progressive Direct's Massachusetts filing says its fee and down payment depend on company risk criteria.
- Eligibility. Some plans are only for new policies, only for renewals or not offered in every state.
Discounts and other ways to manage the premium
The National Association of Insurance Commissioners recommends asking about discounts for multiple cars, driver education, good students under 25, mature drivers, safety equipment, anti-theft devices, and bundling auto with home insurance. Each insurer decides which it offers and how much they are worth.
Discounts and cost-management strategies
| Discount or strategy | Who might qualify | What to ask or verify | Limitation |
|---|---|---|---|
| Multi-policy (bundling) | Drivers who also buy home or renters insurance | The combined price of both policies | Can raise your total if the second policy is expensive |
| Multi-vehicle | Households insuring two or more cars | Whether all cars must be on one policy | Not useful for single-car households |
| Good student | Young drivers with qualifying grades | Grade requirement and proof | Age limits apply; the NAIC cites drivers under 25 |
| Driver education or mature driver | New drivers or older drivers who complete a course | Which courses count | The NAIC cites mature-driver status for ages 50 to 65 |
| Pay in full or fewer payments | Drivers who can pay more upfront | How much it saves compared with installments | Needs more cash today |
| Higher deductible | Drivers with savings for a claim | That you could pay the deductible tomorrow | Raises out-of-pocket cost after a claim |
Discount names, amounts, and eligibility vary by insurer and state; we do not list percentages. Always give complete and correct information. Misstating your address, mileage, driving history, vehicle use or household drivers can lead to a denied claim or a canceled policy.
Common mistakes to avoid
Assuming "pay later" means $0 today. Ask for the dollar amount due before coverage starts, in writing.
Confusing monthly billing with financing. Ask who you will owe: the insurer or a separate lender.
Comparing quotes with different coverage. Match limits, deductibles, drivers, and term before comparing prices.
Looking only at the first payment. Add every installment and fee to find the total.
Ignoring fees. Ask about installment, processing, finance, late and returned-payment fees.
Assuming a payment service guarantees insurance. Approval by a lender or app does not mean an insurer has accepted you.
Treating a quote as coverage. A quote is a price estimate. You are covered only once the insurer issues the policy.
Choosing a deductible you could not pay. Pick an amount you could cover after a claim.
Skipping the cancellation rules. Ask how much notice you will get if a payment is missed and how to reinstate.
PRO TIP #2: CONFIRM COVERAGE BEFORE DRIVING
Before you drive, get your policy number, insurance ID card and declarations page showing the effective date and time. If you only have a payment receipt, a lender approval or a quote screen, call the insurer and ask them to confirm the policy is in force.
Frequently asked questions
What is buy now pay later car insurance?
It is a common phrase, not a policy type. People use it for any way of starting coverage without paying the full premium upfront, most often an insurer's installment plan. It can also refer to premium financing from a separate lender or to "no down payment" marketing, which usually still requires a first payment.
Can I get car insurance now and pay later?
Usually, you can pay part now and the rest later. Many insurers offer installment plans that start with a partial payment. GEICO publishes plans for new policies starting at 25%, or 20% with automatic payments. What you generally cannot do is start a policy with nothing paid, so ask each insurer for the amount due.
Can I get car insurance with no money upfront?
It is uncommon. Most insurers require a first payment before the policy takes effect. "No down payment" offers typically mean your first payment equals one regular installment. If a company says nothing is due today, ask for that in writing and confirm when the first charge will be made.
Is monthly car insurance the same as buy now pay later?
Not exactly. Monthly billing is an insurer splitting your premium into scheduled payments, and you owe the insurer. Retail buy-now-pay-later and premium financing involve a separate company that pays or fronts the money, and you owe that company, often under its own fees, rules, and possibly interest.
Does buy now pay later car insurance require a credit check?
It depends on who is involved. Many insurers use credit-based insurance scores in pricing where state law allows. A separate financing or payment provider may run its own credit check; the FTC notes some buy-now-pay-later providers do. Ask each company whether it checks credit and how.
Are there extra fees for paying later?
Often, yes. Insurers may add a fee to each installment. Progressive Direct's Massachusetts filing lists $5 or $8 per installment, or $1 or $4 with electronic transfers, plus a $25 late fee. Lenders may also charge interest. Ask for every fee before you choose a plan.
How can I get car insurance with a low first payment?
Ask each insurer which plan requires the least money to start, choose a schedule with more installments, and enroll in automatic payments if that lowers the first payment. Lowering your premium through discounts or a higher deductible also shrinks the first payment. Compare at least three quotes with identical coverage.
Does paying later mean my insurance is active immediately?
No. Coverage starts on the effective date the insurer sets once it issues the policy, which may be the same day or later. A payment to a financing company or app does not by itself make you insured. Wait for your policy number and ID card before driving.
The Final Word On Buy Now Pay Later Car Insurance
If you cannot afford a large first payment, you still have real options. Many insurers let you start with a partial payment and spread the rest over the policy term. Ask each insurer for its lowest-start plan and weigh it against the total of all payments, fees included.
Prices and payment arrangements vary by insurer, state, driver, and eligibility. Figures in this article are averages, published terms or hypothetical examples, not quotes. This article is for information only and is not financial or legal advice. The publisher is not an insurance company, agency or lender.
The bottom line on buy now pay later car insurance: a smaller first payment is widely possible, a free start is not, and the best choice is the plan whose first payment and total cost both fit your budget.
Sources
- GEICO, Auto Payment Methods and Plans (accessed October 14, 2026).
- Mass.gov, Progressive Direct Insurance Company Installment Payment Plans (accessed October 14, 2026).
- Dairyland, Auto Insurance (accessed October 14, 2026).
- Klarna, Prohibited and Restricted Businesses (accessed October 14, 2026).
- Federal Trade Commission, Want to buy now but pay later? Read this first (updated May 2024).
- NAIC, Tips for Saving on Your Auto Insurance.
- ValuePenguin, Average Cost of Car Insurance (updated October 1, 2026).
- MoneyGeek, Buy Now Pay Later Car Insurance (updated August 31, 2026).
- Alias Insurance, Can I Pay Car Insurance with Afterpay? (updated March 21, 2026).
- California Insurance Code § 662 and Official Code of Georgia § 33-24-44.