
Cheap Car Insurance in Ohio With No Down Payment
If you want cheap car insurance in Ohio with no down payment, you are shopping in one of the more affordable states in the country. Ohio's averages sit well below the national figures, which means even a full first month of premium can be a modest amount. The challenge is not usually the price; it is finding a plan that starts small and stays affordable for the whole term.
This guide explains how first payments work in Ohio, what state law says about your policy in its first 90 days, what Ohio drivers pay in 2026, five vehicles that are cheap to insure, and how to start coverage for the least money upfront, using strategies from our guide to cheap car insurance with no deposit.
KEY TAKEAWAYS
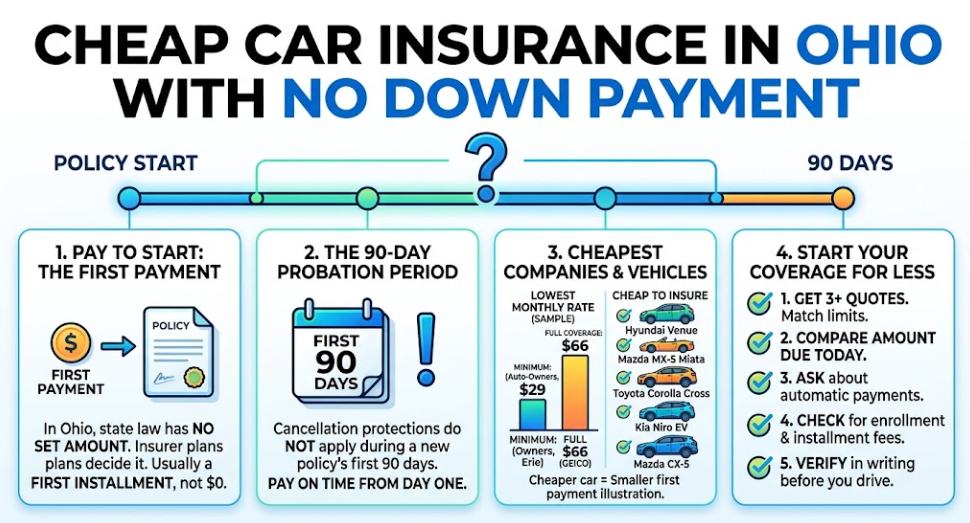
- No Ohio law we found sets a down payment amount. Each insurer's payment plan decides it, and most collect a first installment before coverage starts.
- Ohio is inexpensive. GEICO had the cheapest full coverage at $66 a month in an October 2026 study, and Auto-Owners and Erie had the cheapest minimum coverage at $29.
- The first 90 days matter. Ohio's cancellation protections generally do not apply until a new policy has been in effect for 90 days, so pay on time from day one.
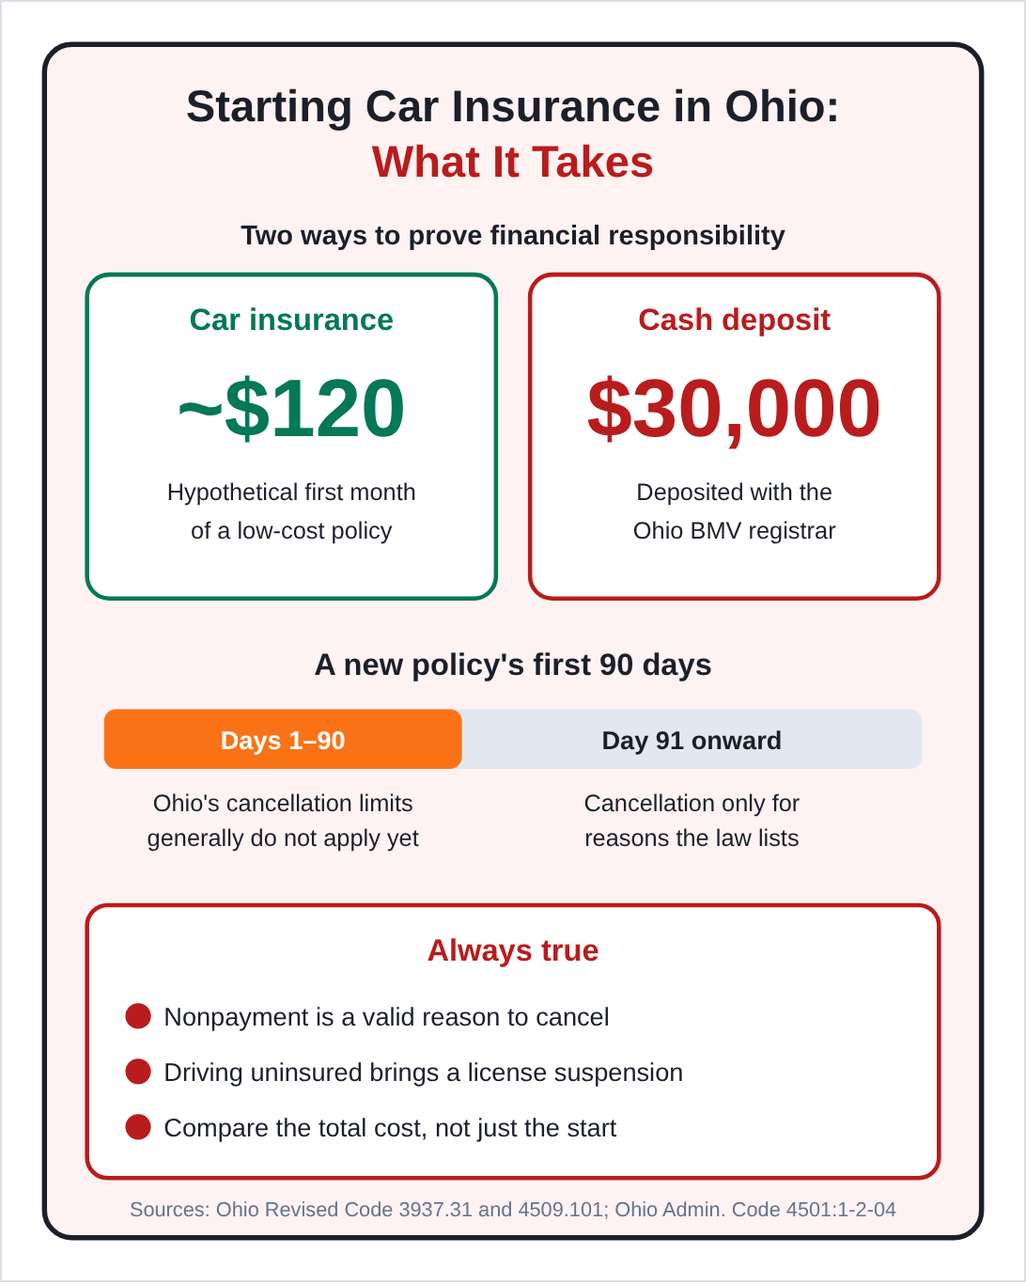
A hypothetical first month of low-cost Ohio car insurance compared with the $30,000 cash deposit Ohio accepts as an alternative proof of financial responsibility, and the 90-day period before Ohio's cancellation limits generally apply. The $120 figure is an illustration, not a quote.
What "no down payment" means for Ohio drivers
Your down payment is the first part of your premium. The premium is what the policy costs for its full term. You pay a portion before coverage begins and the rest in installments.
"No down payment" is a marketing phrase. It usually means your first payment is no bigger than the payments that follow. Insurers may call it a "deposit," "initial payment," or "amount due today." In every case, it is money you pay before the policy starts.
Three figures to compare on every Ohio quote
| Figure | What it means | Why it matters |
|---|---|---|
| Amount due today | What you pay before the policy becomes effective | Decides whether you can start coverage now |
| Each installment | Every later payment, plus any fee | Must fit your budget every month |
| Total for the term | All payments and fees added together | The real price you are comparing |
Ohio car insurance requirements
Ohio requires liability coverage of at least $25,000 per person and $50,000 per accident for injuries, plus $25,000 for property damage, often written as 25/50/25. Ohio does not require personal injury protection or uninsured motorist coverage, though both may be offered.
About 18.5% of Ohio drivers were uninsured in 2023, the 12th-highest rate in the country, according to the Insurance Research Council. That is a strong argument for adding uninsured motorist coverage even when you are trying to keep costs down.
Alternatives to an insurance policy
Ohio law accepts other proof of financial responsibility besides insurance, including a bond and a certificate of deposit of money. Under Ohio Administrative Code 4501:1-2-04, effective July 1, 2024, a driver using the deposit route must place $30,000 in money with the BMV registrar. For almost everyone looking for a low first payment, an insurance policy is the far cheaper route.
Penalties for driving uninsured
Under Ohio Revised Code 4509.101, a first violation brings a license suspension until you meet the reinstatement conditions and a $40 reinstatement fee. A second violation carries a one-year suspension and a $300 fee, and a third or later violation a two-year suspension and a $600 fee. A court may grant limited driving privileges only if you show proof of coverage.
Can you get cheap car insurance in Ohio with no down payment?
You can usually start with a small first payment, but a true $0 start is uncommon. We found no Ohio statute that sets a minimum or maximum down payment for auto insurance. That is different from New York, where a new policy needs at least 10% of the annual premium paid, or Florida, which generally requires one month's premium. In Ohio, each insurer's payment plans decide the amount.
Insurers publish their own plans. GEICO, for example, lists plans for new policies that start at 25% of the premium on a five-payment plan, or 20% with automatic payments. It says installment fees may apply and some plans are not available in every state. Ask each insurer for its Ohio terms in writing.
How Ohio compares with other states
First-payment rules in Ohio and four other states
| State | State rule on the first payment | Source |
|---|---|---|
| Ohio | No state minimum or maximum found; set by each insurer's plan | Our review of Ohio law |
| New York | At least 10% of the annual premium on a new policy | N.Y. Vehicle and Traffic Law § 311(5)(c) |
| Florida | At least one month's premium on most new policies, with exceptions | Fla. Stat. § 627.7295(7) |
| Texas | About two months' premium as a ceiling under a 1997 rule | TDI Bulletin B-0039-97 |
| Pennsylvania | No state minimum or maximum found | Pennsylvania Insurance Department guide |
Ohio's 90-day rule for new policies
Ohio Revised Code 3937.31 requires every auto policy to be issued for at least one year, or to be guaranteed renewable for periods adding up to at least a year. Once a policy has been in force for 90 days, the insurer can cancel it only for reasons the law lists, such as fraud, loss of driving privileges, or nonpayment of premium.
Those limits generally do not apply to a new policy that has been in effect for less than 90 days. For a driver starting with a small first payment, the lesson is simple: the first three months are when your policy is most exposed, and a missed installment can end it at any point.
Questions to ask before you buy
- What exact amount is due before the policy becomes effective?
- Does enrolling in automatic payments lower the amount due today or the fees?
- What is the fee on each installment, and is there a late or returned-payment fee?
- Is any part of my premium financed by a separate premium finance company?
- Will you confirm the effective date and amount in writing?
The cheapest car insurance companies in Ohio
GEICO had the lowest full-coverage rate in an October 2026 study of a 40-year-old Ohio driver, at $66 a month. Auto-Owners followed at $74 and Erie at $83. For minimum coverage, Auto-Owners and Erie tied for cheapest at $29 a month, with GEICO next at $35.
A second analysis, based on real quotes current to September 30, 2026, found even lower figures. State Farm led at $35 a month for liability-only coverage and $57 for full coverage, followed by Mile Auto, a pay-per-mile insurer, at $36 and $59. The studies use different drivers and limits, so compare each study's numbers only with each other.
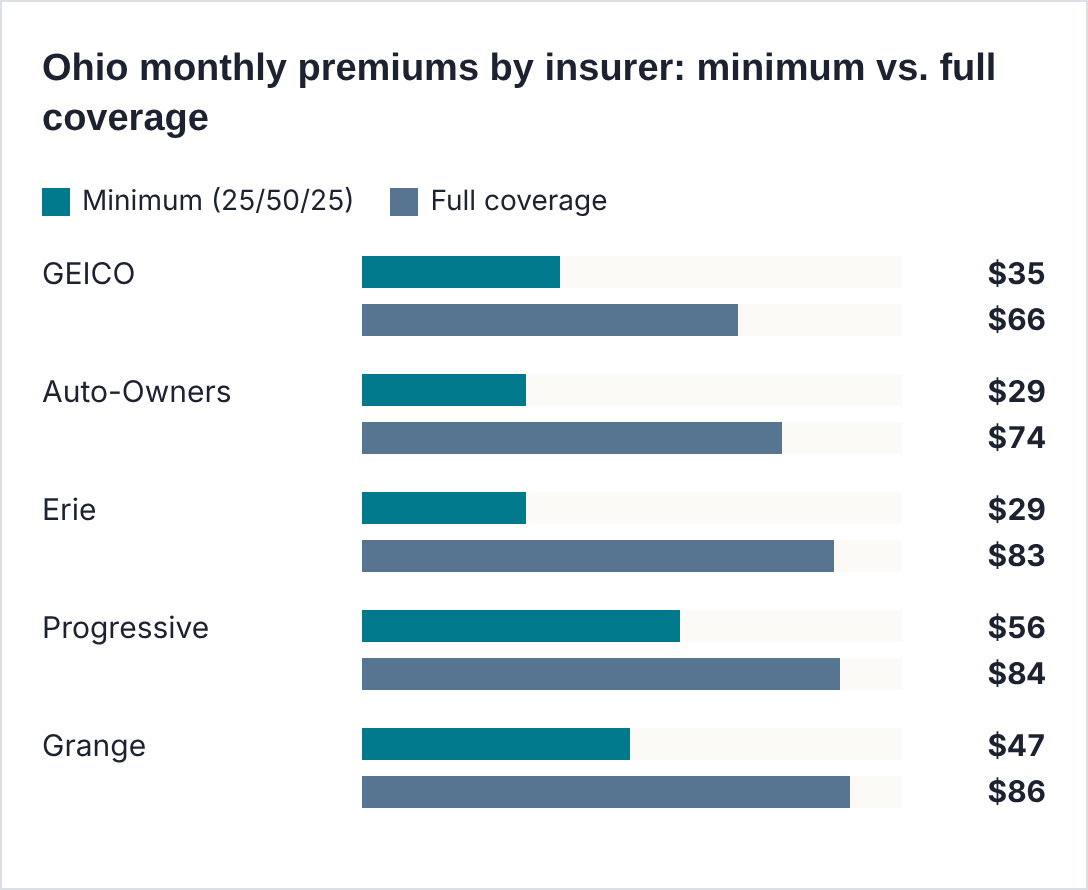
Study A: rate study updated October 6, 2026. Driver: 40-year-old man, 2012 Toyota Camry LE, clean record, good credit, 12,000 miles a year. Full coverage: 100/300/100 liability with a $1,000 deductible. Minimum: Ohio 25/50/25 liability. Statewide Ohio rates.
Ohio insurers in two 2026 rate studies
| Insurer | Minimum, study A (monthly) | Full coverage, study A (monthly) | Liability-only, study B (monthly) | Full coverage, study B (monthly) |
|---|---|---|---|---|
| GEICO | $35 | $66 | Not publicly confirmed | Not publicly confirmed |
| Auto-Owners | $29 | $74 | $41 | $67 |
| Erie | $29 | $83 | $41 | $67 |
| Progressive | $56 | $84 | $41 | $75 |
| Grange | $47 | $86 | Not publicly confirmed | Not publicly confirmed |
| State Farm | Not publicly confirmed | Not publicly confirmed | $35 | $57 |
| Mile Auto | Not publicly confirmed | Not publicly confirmed | $36 | $59 |
Study A: rate study updated October 6, 2026 (profile above); it excludes USAA. Study B: real quotes current to September 30, 2026, drivers ages 20 to 70 with clean records, and $1,000 deductibles on full coverage. "Not publicly confirmed" means the study did not publish that figure. Treat both as benchmarks for drivers with clean records; your quote may be higher.
How much does car insurance cost in Ohio?
Ohio averages $65 a month for liability-only coverage and $117 for full coverage in study B, compared with national figures of $99 and $187 from the same source. That puts Ohio $34 and $70 a month below the national averages (our calculation).
Your own price depends on your age, driving record, vehicle, location, coverage, and credit-based insurance score. Ohio insurers may consider credit history, and the chart shows how much it and a drunk-driving conviction, called OVI in Ohio, moved the cheapest full-coverage rate in study A.
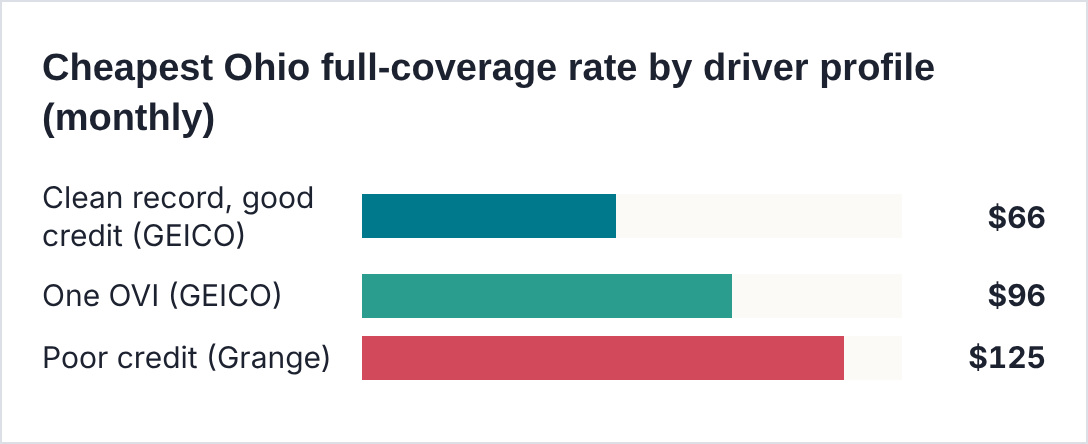
Study A, updated October 6, 2026. Cheapest company rate for each profile, 40-year-old driver, 100/300/100 limits, $1,000 deductible. Each profile changes one factor from the clean-record, good-credit driver.
If your credit is weak
Credit had a bigger effect than an OVI in study A. GEICO, the cheapest company for a clean-record driver with good credit, charged $172 a month for full coverage to the same driver with poor credit, while Grange charged $125. If your credit is weak, do not assume the company that is cheapest for others will be cheapest for you; get quotes from regional insurers as well as national ones.
Teen drivers on a family policy pay more, but Ohio's figures are low by national standards. In study A, GEICO was cheapest for every age shown: $175 a month for a 16-year-old male, $125 at 18, $90 at 21, and $72 at 25.
Minimum coverage vs. full coverage in Ohio
| Minimum (25/50/25 liability) | Full coverage | |
|---|---|---|
| What it pays for | Injuries and property damage you cause to others, up to the limits | Liability plus damage to your own car from crashes, theft, weather, and more |
| Required by Ohio law? | Yes: $25,000 per person, $50,000 per accident, $25,000 property damage | No, but lenders and leasing companies usually require collision and comprehensive |
| Cheapest monthly rate, study A (40-year-old) | $29 (Auto-Owners, Erie) | $66 (GEICO) |
| Average monthly cost, study B (real quotes) | $65 (liability-only) | $117 |
| What it leaves out | Repairs to your own car; your own injuries | Little for most drivers, depending on limits |
Figures are averages or cheapest-company rates, not quotes. Study B's liability-only policies include limits between the state minimum and $50,000/$100,000.
Five vehicles that cost less to insure in Ohio
The vehicle you insure moves your premium, and a smaller premium means a smaller first payment. A vehicle-model rate study compared average six-month full-coverage premiums across Ohio, using sample 18- and 40-year-old drivers, 100/300/100 limits, and $500 deductibles. The study's page shows no update date; we accessed it in October 2026. For more options, see our list of the top cheapest cars to insure.
Ohio's list is the most varied we have seen: a subcompact SUV, a two-seat convertible, a compact crossover, an electric crossover, and a compact SUV, all within $30 of each other over six months.
1. Hyundai Venue
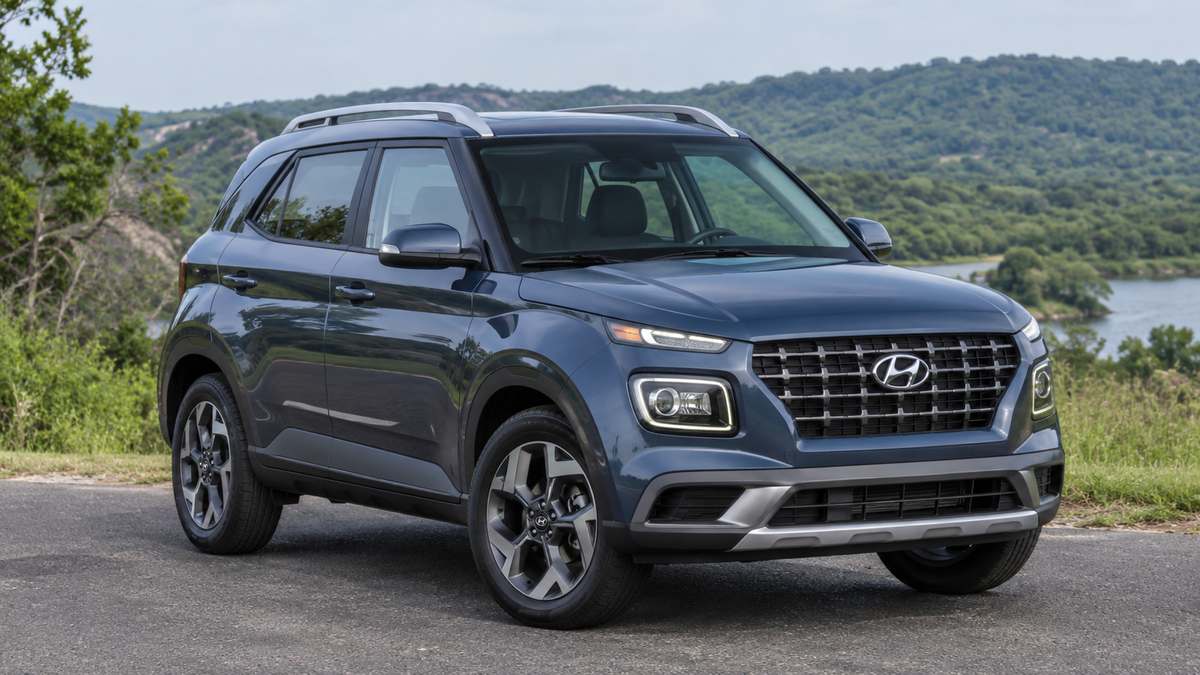
Original vector illustration of the Hyundai Venue, a subcompact SUV. Illustration only; not to scale.
Average premium: $687 for six months of full coverage in Ohio. The Hyundai Venue is a subcompact SUV. It had the lowest average premium of any model in the Ohio study.
2. Mazda MX-5 Miata
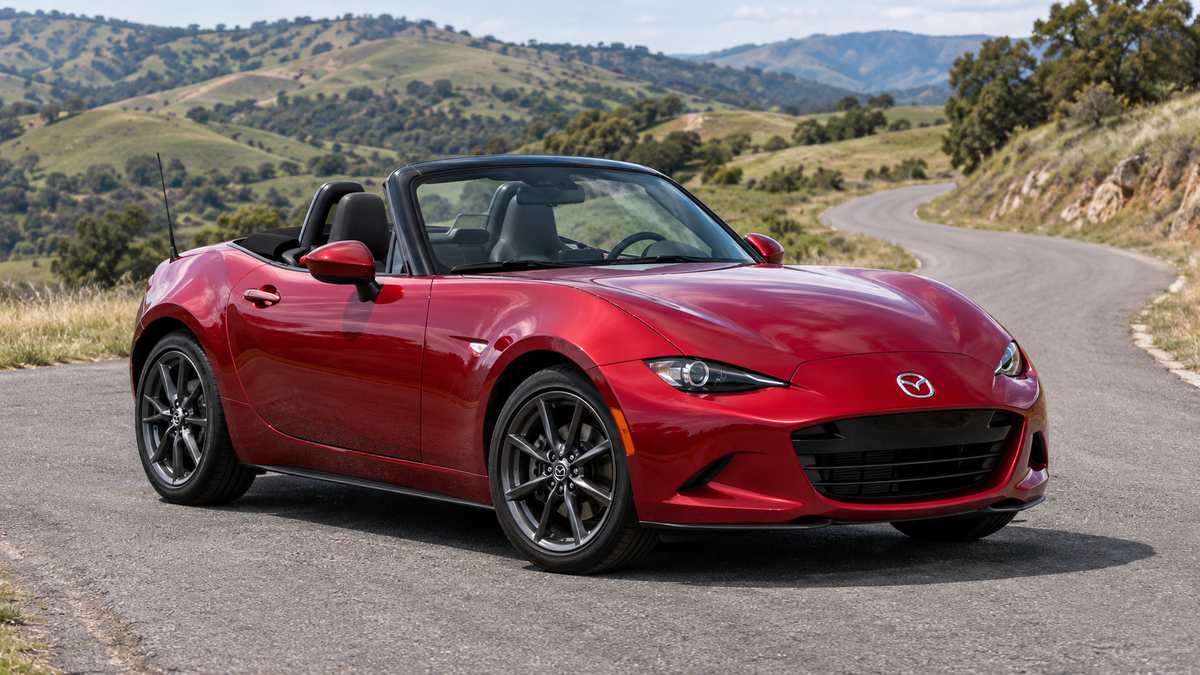
Original vector illustration of the Mazda MX-5 Miata, a two-seat convertible. Illustration only; not to scale.
Average premium: $695 for six months of full coverage in Ohio. The Mazda MX-5 Miata is a two-seat convertible. It ranked second, only $8 above the Venue, and was the cheapest to insure for an 18-year-old.
3. Toyota Corolla Cross
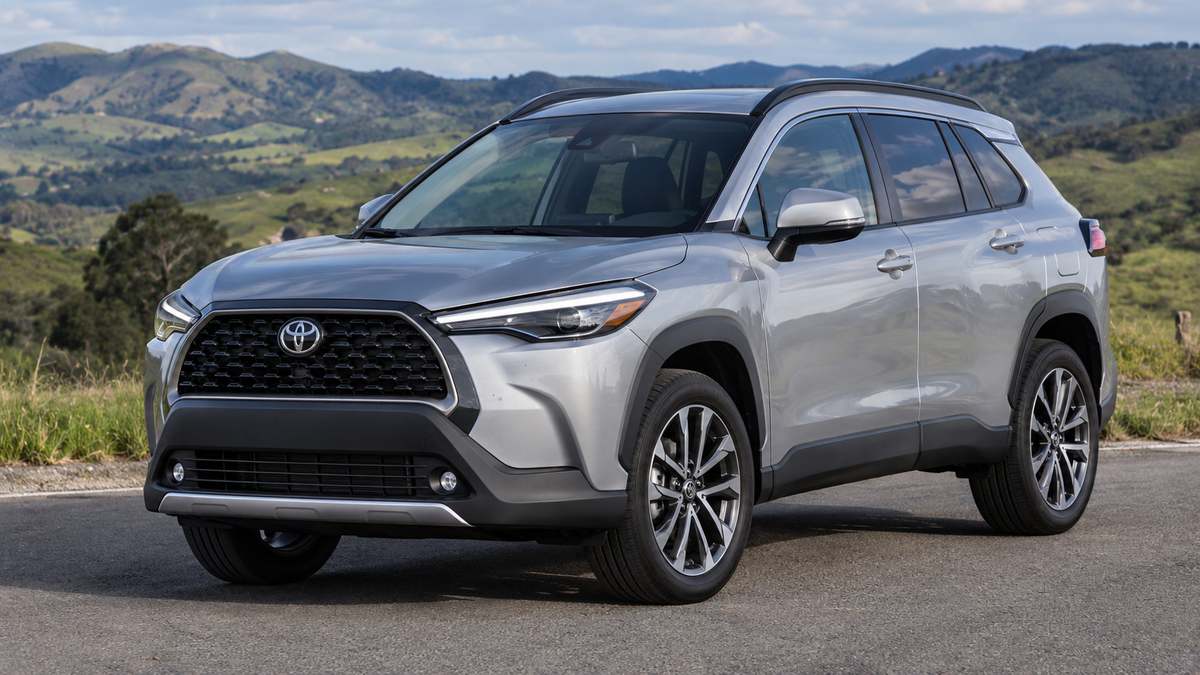
Original vector illustration of the Toyota Corolla Cross, a compact crossover. Illustration only; not to scale.
Average premium: $715 for six months of full coverage in Ohio. The Toyota Corolla Cross is a compact crossover. It ranked third, $28 above the Venue over six months.
4. Kia Niro EV
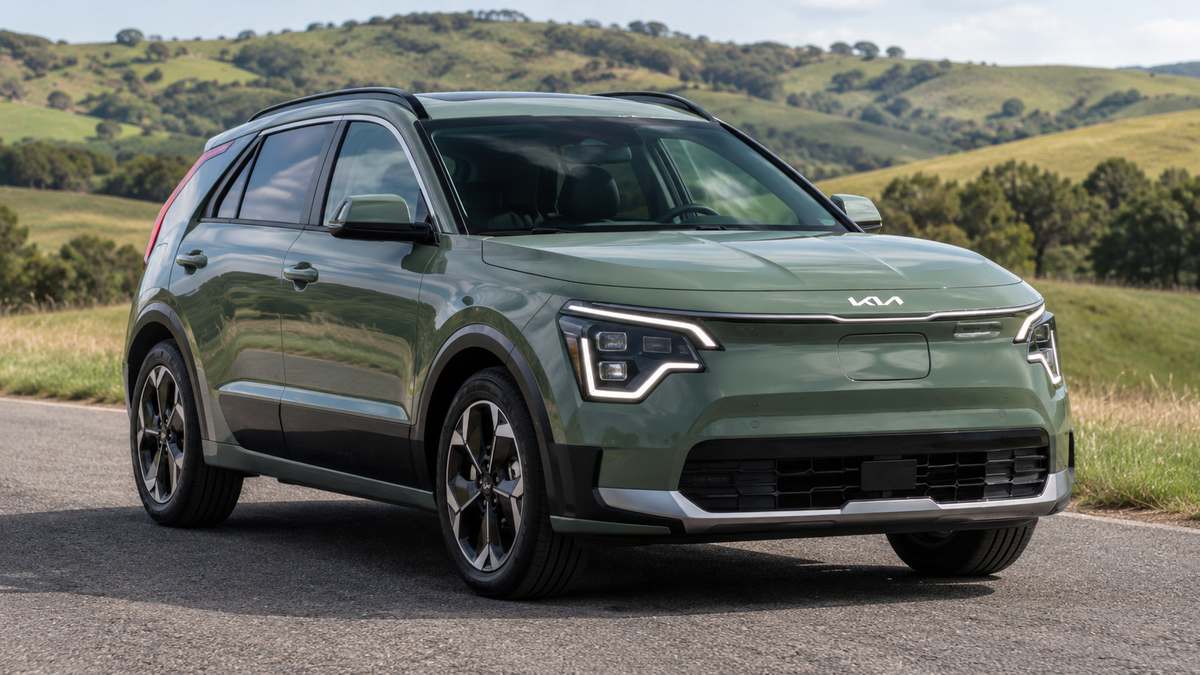
Original vector illustration of the Kia Niro EV, an electric crossover. Illustration only; not to scale.
Average premium: $716 for six months of full coverage in Ohio. The Kia Niro EV is an electric crossover. It is the only electric vehicle in the top five, $1 behind the Corolla Cross.
5. Mazda CX-5
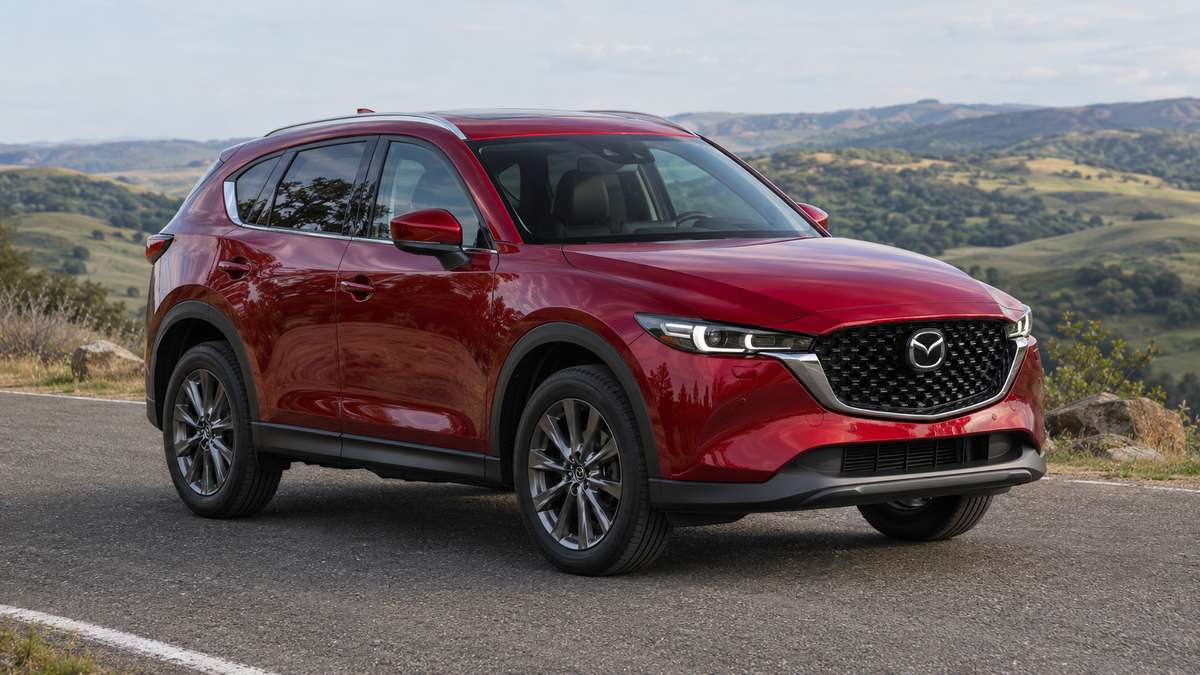
Original vector illustration of the Mazda CX-5, a compact SUV. Illustration only; not to scale.
Average premium: $717 for six months of full coverage in Ohio. The Mazda CX-5 is a compact SUV. It rounded out the five, $30 above the Venue over six months.
Five vehicles with the lowest average insurance premiums in Ohio
| Rank | Make and model | Model year | Average six-month premium | Insurance-cost finding | Source |
|---|---|---|---|---|---|
| 1 | Hyundai Venue | Not specified by source | $687 | Lowest in the Ohio study | Vehicle-model rate study, accessed Oct. 2026 |
| 2 | Mazda MX-5 Miata | Not specified by source | $695 | Only convertible; $8 above first | Vehicle-model rate study, accessed Oct. 2026 |
| 3 | Toyota Corolla Cross | Not specified by source | $715 | $28 above first place | Vehicle-model rate study, accessed Oct. 2026 |
| 4 | Kia Niro EV | Not specified by source | $716 | Only EV in the top five | Vehicle-model rate study, accessed Oct. 2026 |
| 5 | Mazda CX-5 | Not specified by source | $717 | Fifth-lowest; $30 above first | Vehicle-model rate study, accessed Oct. 2026 |
Statewide Ohio averages for sample 18- and 40-year-old drivers, full coverage at 100/300/100 with $500 deductibles. The study does not publish model years. For an 18-year-old, the MX-5 Miata averaged $2,272 for six months and the Venue $2,454.
To connect the car to your first payment: one month of a six-month premium is one-sixth of it. On these averages, that is about $115 for the Venue and $120 for the CX-5 (our calculation). These are illustrations from statewide averages, not quotes.
How to start Ohio coverage with a small first payment
Aim for the smallest first payment on a policy whose total you can also afford. Follow these steps in order.
- 1. Get at least three quotes. In study A, full coverage ranged from $66 to $86 a month among the five cheapest insurers.
- 2. Use identical coverage on every quote. Match liability limits, uninsured motorist coverage, deductibles, drivers, and term.
- 3. Consider a pay-per-mile policy if you drive little. A per-mile insurer was among the cheapest in study B; check the base rate and per-mile charge.
- 4. Ask for the amount due today, with and without automatic payments.
- 5. Compare fees and due dates, and add them up to find the total for the term.
- 6. Confirm the effective date and amount in writing, and keep your old policy active until the new one starts.
Is pay-per-mile insurance a fit?
A pay-per-mile insurer ranked second in study B, which makes this option worth a look in Ohio. These policies usually charge a monthly base rate plus a few cents for each mile you drive, so a low-mileage driver can end up with a small monthly bill and a small first payment. They are a poor fit for long commutes, and the per-mile charge and tracking method vary by company, so compare a full month's likely cost before you switch.
First payment vs. total cost: a hypothetical comparison
The chart uses a hypothetical $720 six-month premium, or $120 a month. It compares paying in full, GEICO's published 25% and 20% plans, and a one-month start with automatic payments. Installment fees of $5, or $1 with automatic payments, are our assumptions, not real charges.
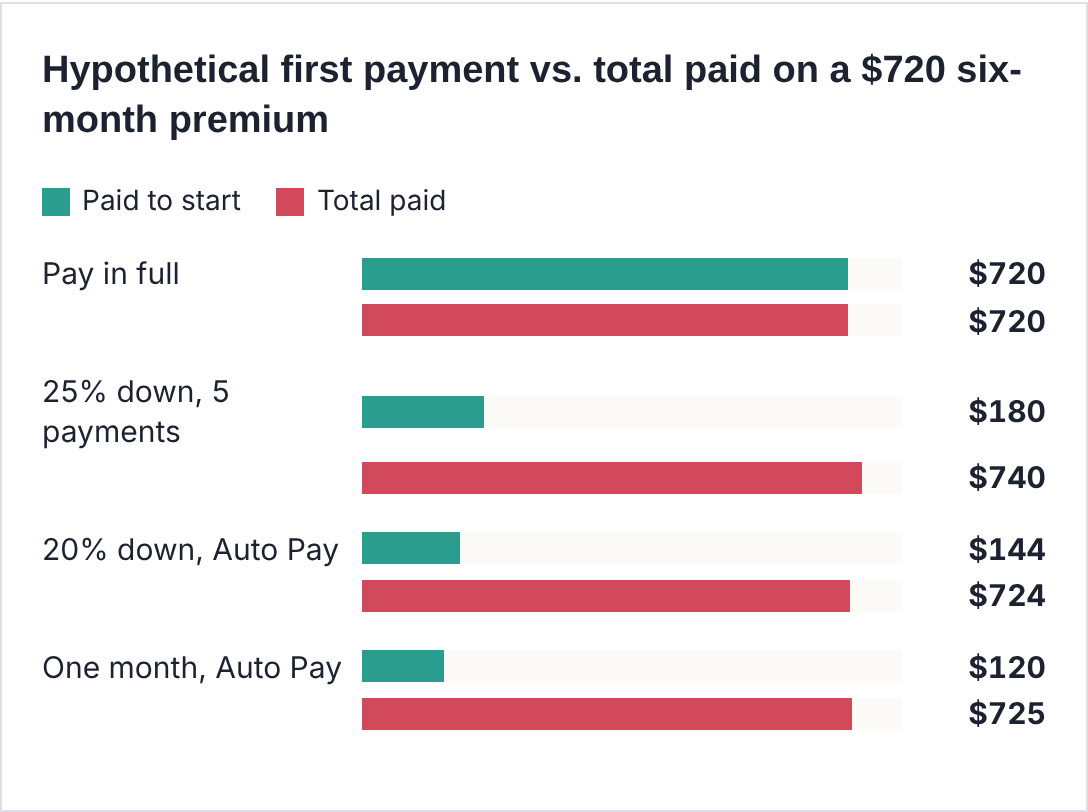
Hypothetical example calculated by us. The 25% and 20% levels are GEICO's published plans for new policies; the other plan and all fees are assumptions, not quotes.
Hypothetical payment plans on a $720 six-month premium
| Plan | Paid to start | Later payments | Assumed fees | Total paid |
|---|---|---|---|---|
| Pay in full | $720 | None | $0 | $720 |
| 25% down, 5 payments | $180 | 4 × $135 | $20 (4 × $5) | $740 |
| 20% down with Auto Pay | $144 | 4 × $144 | $4 (4 × $1) | $724 |
| One month down with Auto Pay | $120 | 5 × $120 | $5 (5 × $1) | $725 |
All figures are hypothetical and calculated by us. They are not insurer quotes. Not every insurer offers a one-month start on new policies.
Because Ohio premiums are relatively low, the gap between the plans is small in dollars. That makes it realistic for many drivers to pay a larger first installment, or even pay in full, and skip installment fees altogether.
What affects your first payment in Ohio?
Your premium, your coverage choices, and the insurer’s payment plans decide the amount due today.
- Driver factors: age, driving record, location, and credit-based insurance score.
- Vehicle and coverage: the car you drive, your limits, and your deductibles.
- Payment plan: the number of installments, automatic payments, and any installment fees.
Discounts and other ways to cut the cost
Every dollar you take off the premium also comes off the first payment. Ask each Ohio insurer which of these apply to you.
Ways to lower your Ohio premium or first payment
| Discount or strategy | Who may qualify | What to verify | Limitation |
|---|---|---|---|
| Pay-per-mile policy | Drivers who drive few miles | Base rate plus the charge per mile | Costs rise if you drive more |
| Automatic payments | Drivers with a reliable bank account or card | Whether it lowers the amount due today or fees | Missed drafts can lead to cancellation |
| Bundling auto with home or renters | Drivers who need property insurance | The combined total of both policies | Can raise the total if the second policy is costly |
| Good student | Young drivers with qualifying grades | Proof required | Age limits apply |
| Higher deductible | Drivers with savings for a claim | That you could pay it after a crash | Raises your out-of-pocket cost |
| Choose a car that is cheaper to insure | Drivers buying a vehicle | Actual quotes on each car | Averages may not match your quote |
Discount amounts vary by insurer, so we do not list percentages. Never misstate your address, garaging location, mileage, driving record, or household drivers; doing so can void a claim.
Common mistakes when shopping for low-cost insurance in Ohio
Buying only 25/50/25 without uninsured motorist coverage. With nearly one in five Ohio drivers uninsured, this gap can be expensive.
Judging a quote by the first payment alone. Always ask for the total for the term, including every fee.
Comparing quotes with different limits. Match liability limits and deductibles before comparing prices.
Missing a payment in the first 90 days. A new policy has the least protection from cancellation during this period.
Frequently asked questions
Can I get car insurance in Ohio with no money down?
Rarely with literally nothing paid. We found no Ohio law setting a down payment, so each insurer's plan decides it, and most collect a first installment before coverage starts. Because Ohio premiums are low, that first payment is often modest. Ask for the amount due today with and without automatic payments.
How much is the first payment for car insurance in Ohio?
It depends on your premium and plan. On a hypothetical $720 six-month premium, a one-month start is $120, and a 25% start is $180. GEICO publishes new-policy plans starting at 25% of the premium, or 20% with automatic payments. Get each insurer's Ohio terms in writing.
Can my Ohio insurer cancel my new policy?
During a new policy's first 90 days, Ohio's cancellation limits generally do not apply. After that, an insurer can cancel only for reasons the law lists, including fraud, loss of driving privileges, and nonpayment of premium. Paying every installment on time is the best protection.
Does paying monthly cost more overall?
It can. Many insurers charge a fee on each installment, and paying in full sometimes earns a discount. Because Ohio premiums are relatively low, paying in full may be within reach. Compare the total of all payments for each plan, using identical coverage, before deciding.
What is the minimum car insurance required in Ohio?
Ohio requires 25/50/25 liability: $25,000 per person and $50,000 per accident for injuries, plus $25,000 for property damage. Uninsured motorist coverage is optional but worth considering, since about 18.5% of Ohio drivers were uninsured in 2023. Lenders usually require collision and comprehensive.
Who has the cheapest car insurance in Ohio?
In an October 2026 study of a 40-year-old driver, GEICO was cheapest for full coverage at $66 a month, and Auto-Owners and Erie tied for minimum coverage at $29. A real-quote study ranked State Farm first. Your cheapest company depends on your profile, so compare quotes.
Which cars are cheapest to insure in Ohio?
A vehicle-model rate study found the lowest average full-coverage premiums for the Hyundai Venue, Mazda MX-5 Miata, Toyota Corolla Cross, Kia Niro EV, and Mazda CX-5. All five were within $30 of each other over six months. A cheaper car lowers your premium and your first payment.
What happens if I drive uninsured in Ohio?
A first violation brings a license suspension until you meet the reinstatement conditions, plus a $40 fee. A second violation brings a one-year suspension and a $300 fee, and a third or later a two-year suspension and a $600 fee. Limited privileges require proof of coverage.
Final recommendation
In Ohio, low premiums make a small first payment realistic, but your insurer’s plan, not state law, sets the amount. Compare the amount due today and the total for the term, along with coverage limits, uninsured motorist coverage, fees, and due dates.
Premiums, payment plans, and eligibility vary by insurer and by your circumstances. The rates in this article are averages and hypothetical examples, not quotes. This article is for information only and is not legal or financial advice. The publisher is not an insurance company or a licensed insurance agency.
The bottom line on cheap car insurance in Ohio with no down payment: expect a modest first installment rather than $0, protect your policy in its first 90 days, and choose the policy whose first payment and total cost both fit your budget.
Sources
- Ohio Revised Code 3937.31, Automobile insurance policy period and cancellation (accessed October 15, 2026).
- Ohio Revised Code 4509.101, Operating without proof of financial responsibility and 4510.02, Suspension classes (accessed October 15, 2026).
- Ohio Administrative Code 4501:1-2-04, Deposits of money (effective July 1, 2024).
- American Family Insurance, Ohio Minimum Car Insurance Requirements (accessed October 2026).
- GEICO, Auto Payment Methods and Plans (accessed October 2026).
- MoneyGeek, Cheapest Car Insurance in Ohio (updated October 6, 2026).
- Insurify, Ohio Car Insurance (rates current to September 30, 2026).
- CarInsurance.com, Cheapest Cars to Insure in Ohio (accessed October 2026).
- Insurance Information Institute, Uninsured Motorists, citing the Insurance Research Council.