
Cheapest Toyota Sienna Insurance: Rates, Companies & Coverage
Published Toyota Sienna insurance prices vary sharply by company, state, driver profile and model year. In one 2025-model sample (Study A), Progressive was $1,763 a year and Allstate $3,663 for the same assumed driver; that $1,900 difference is a study comparison, not a guaranteed individual saving. Study C reports an overall Sienna full-coverage average of $2,766 annually, while its detailed 2025-model table lists $2,581. Compare quotes using the same limits, deductibles and garaging address.
The Sienna has used a hybrid-only powertrain since its 2021 redesign. The current generation pairs a 2.5-liter gasoline engine with a hybrid system rated at 245 combined horsepower, with front- or all-wheel drive depending on trim. Toyota reported 2025 U.S. sales of 101,486 Siennas; sales volumes do not establish an individual insurance rate.
This guide compares published Sienna premiums across insurers, coverage levels, trims, model years and states. It also examines second-row seat recalls, crash-test results, teen-driver premiums, discounts and the Sienna’s position relative to other minivans. Rankings identify insurers worth quoting; they are not a statistically weighted national verdict.
Toyota Sienna insurance at a glance
| Measure | Figure | Source |
| Average full coverage, 2025 model (Study C detail) | $2,581 a year (about $215 a month) | Study C, 2025 detail; overall model avg $2,766 |
| Average liability-only (50/100/50) | $1,109 a year | Study C, Oct 2026 |
| Cheapest company, 2025 Sienna, 30-year-old | Progressive, $1,763 a year | Study A |
| Cheapest company, 2025 Sienna, 40-year-old | Travelers, $1,848 a year | Study C, Oct 2026 |
| Cheapest current trim in the trim data | LE, $184 a month | Study G, May 2026 |
| Average for an 18-year-old male driver | $8,934 a year | Study D, Mar 2026 |
| Average for a 55-year-old driver | $2,099 a year | Study E |
Sources use different ages, vehicle years, states, coverages and deductibles. Compare numbers within the same study rather than ranking prices across different studies. These are sample or aggregated estimates, not binding quotes. Study letters and their source links appear at the end.
The 10 cheapest insurance companies for a Toyota Sienna
The ten companies below are an editorial shortlist assembled from studies using different profiles and geographic samples. The numbered order is not a reproducible overall-price ranking: one entry (Farm Bureau) comes from a Texas-only sample, and some insurers are not available in every state. Compare like-for-like quotations to identify the lowest price for your household.
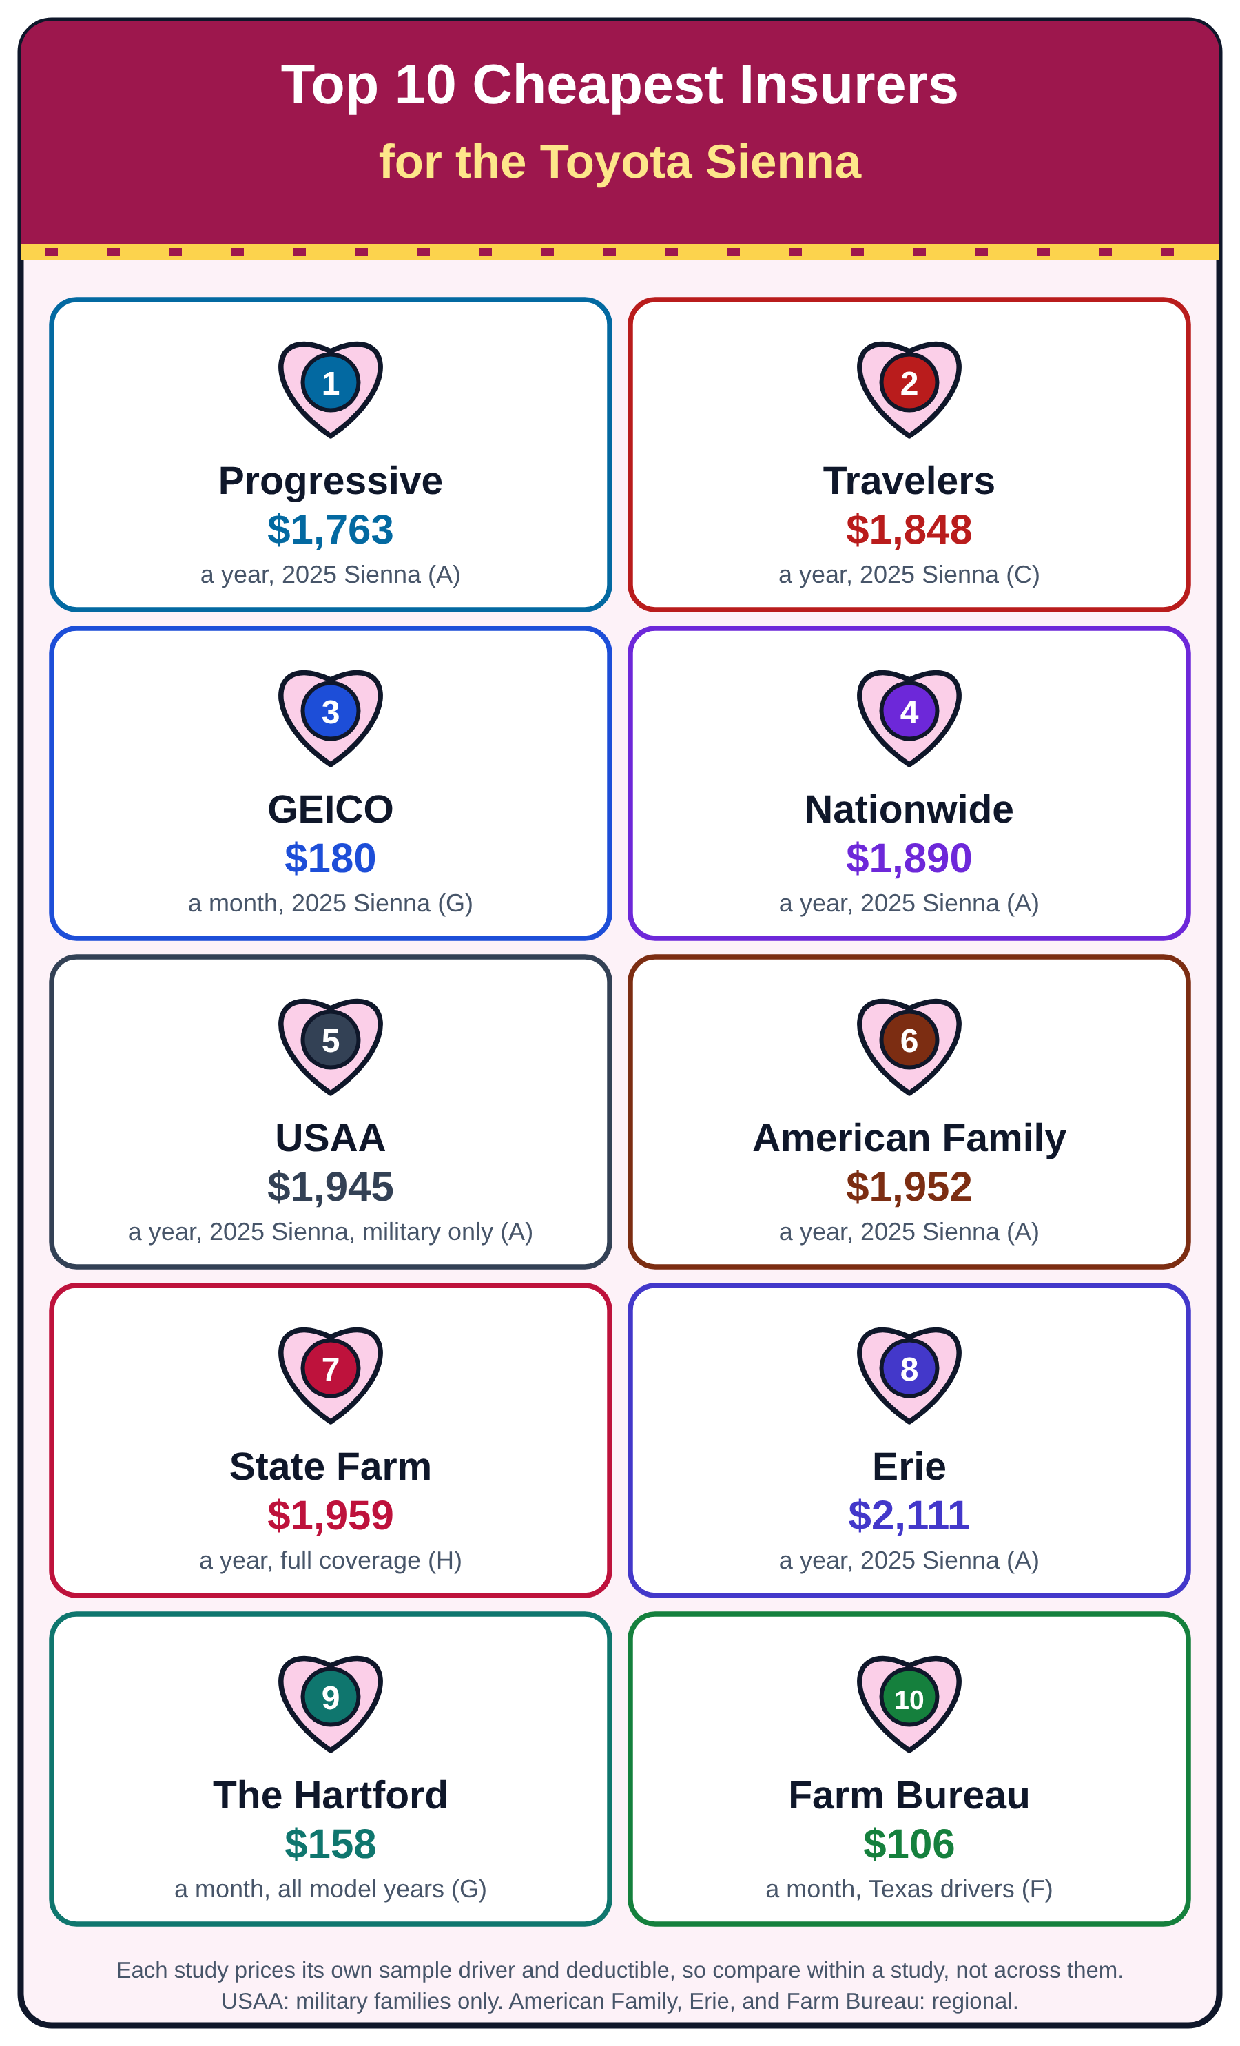
Graphic data note: The numbered graphic mixes rates from different driver profiles and includes a Texas-only Farm Bureau quote. It is not a verified nationwide cheapest-to-most-expensive ranking.
The 10 cheapest insurers for a Toyota Sienna. The letter after each price names the study.
Sienna prices for the top 10 companies by study
| Insurer | Study A, 2025 (year) | Study C, 2025 (year) | Study G, 2025 (month) | Study H (year) |
| 1. Progressive | $1,763 | $2,638 | $222 | $1,905 |
| 2. Travelers | — | $1,848 | $179 | — |
| 3. GEICO | $2,464 | $2,238 | $180 | $2,068 |
| 4. Nationwide | $1,890 | $2,445 | $201 | $1,991 |
| 5. USAA* | $1,945 | $2,010 | — | — |
| 6. American Family | $1,952 | — | — | — |
| 7. State Farm | $2,210 | $2,430 | $239 | $1,959 |
| 8. Erie | $2,111 | — | — | — |
| 9. The Hartford | — | — | $223 | — |
| 10. Farm Bureau | — | — | — | — |
Full coverage. Study A: 30-year-old male, 2025 Sienna. Study C: 40-year-old, 100/300/100, $500 deductible, October 2026. Study G: 40-year-old male, $1,000 deductible, May 2026. Study H: 40-year-old male, $500 deductible. Farm Bureau appears only in Study F, which priced Texas drivers at $106 a month. *USAA sells only to military families.
1. Progressive
Different insurers led different samples: Progressive in Study A and Study H, Travelers in Study C, and GEICO across the mixed model years in Study G. The cheapest for your Sienna depends on an individual quote.
2. Travelers
Travelers was the cheapest company in Study C for every model year from 2018 to 2025, including $1,848 for a 2025 Sienna. It also had the lowest 2025 full-coverage price in Study G, at $179 a month. Beyond price, its coverage and discount options are discussed in a Spanish-language insurer review.
3. GEICO
GEICO had the lowest averages across all model years in Study G, at $130 a month for full coverage and $60 for state minimum, and it charges $2,238 a year for a 2025 Sienna in Study C.
4. Nationwide
Nationwide was second in Study A at $1,890 a year for a 2025 Sienna, and it was the cheapest company in Study C’s Florida sample for a 2025 Sienna LE, at $2,025. Drivers interested in its discounts can review Nationwide coverage and SmartRide features in Spanish before confirming availability in their state.
5. USAA
USAA charges $1,945 a year for a 2025 Sienna in Study A and $2,010 in Study C, and it was the cheapest company in Study A for many older Siennas, including every model year from 2011 to 2015. Only military families can buy it.
6. American Family
American Family costs $1,952 a year for a 2025 Sienna in Study A, close behind USAA, and it beat USAA on the 2024 model at $1,862. It sells in fewer states than the national companies.
7. State Farm
State Farm was the second-cheapest company in Study H, at $1,959 a year, just $54 above Progressive.
8. Erie
Erie charges $2,111 a year for a 2025 Sienna in Study A, below the $2,414 average, and it leads three regions in J.D. Power’s 2026 satisfaction study.
9. The Hartford
The Hartford’s average across all model years in Study G is $158 a month, third-lowest among 14 companies. Its policies are sold mainly through the AARP program.
10. Farm Bureau
Study F, which priced Sienna drivers in every Texas ZIP code, found Farm Bureau cheapest at an average of $106 a month. Farm Bureau insurers operate state by state.
PRO TIP #1
Begin with Progressive, Travelers, GEICO and Nationwide if they write policies where you live; add other suitable companies, including USAA if eligible. The $1,900 annual gap in Study A describes one sample driver and is not an expected saving for every Sienna owner. When comparing insurance rates before your renewal, keep the coverage limits and deductibles identical.
Sienna insurers compared on service
Price alone does not establish claims quality. The satisfaction figures below reflect regional results across auto insurance customers, not Toyota Sienna claims specifically. NAIC complaint indexes are national, can differ by underwriting legal entity and data year, and are not a direct claims-speed ranking. AM Best gauges financial strength, not a guarantee of claim payment.
Service ratings for leading Sienna insurers
| Insurer | J.D. Power 2026 (regional range) | NAIC complaint index | AM Best rating |
| Progressive | 604 to 645 | 0.71 | A+ |
| Travelers | 584 to 657 | 0.52 | A++ |
| GEICO | 631 to 668 | 0.69 | A++ |
| Nationwide | 612 to 685 | 0.63 | A |
| USAA* | 707 to 763 | 1.18 | A++ |
| American Family | 632 to 649 | 0.33 | A |
| State Farm | 632 to 669 | 0.79 | A+ (Nov. 2025 downgrade) |
| Erie | 652 to 704 | 0.89 | A+ |
| Allstate | 612 to 660 | 1.10 | A+ |
| Farmers | 558 to 675 | 0.86 | A |
J.D. Power scores are out of 1,000 from its June 2026 U.S. Auto Insurance Study, where the average was 644. AM Best ratings and NAIC indexes as reported by Study D in December 2025 and August 2026. *USAA is not officially ranked by J.D. Power because it sells only to military families.
Best price for most families: Progressive
Progressive led Studies A and H on price, holds an A+ rating, and has a complaint index of 0.71.
Best for a 40-year-old driver: Travelers
Travelers led Study C for eight straight model years, holds an A++ rating, and has a complaint index of 0.52, among the lowest of the large insurers.
Best for claims: Nationwide and Amica
Amica ranked first in J.D. Power’s October 2026 claims study with 775 points and Nationwide second with 743, against an average of 700. Nationwide is also the second-cheapest company for a 2025 Sienna in Study A.
Fewest complaints: American Family
American Family’s complaint index of 0.33 is the lowest in our table, and its 2025 Sienna price is $462 below Study A’s average.
Best for military families: USAA
USAA earned the highest J.D. Power scores in every region, from 707 to 763, and it was the cheapest company in Study A for every Sienna from 2011 to 2015.
PRO TIP #2
Ask each insurer about its rental car coverage limit. A family of seven or eight needs a minivan or large SUV while the Sienna is in the shop, and a low daily limit may not cover a vehicle that size.
The cheapest Sienna insurance company overall
Progressive led two of the published samples, but the evidence does not establish that it is cheapest for most Sienna drivers. In Study A, its $1,763 rate was $1,900 below Allstate for the same hypothetical 2025 Sienna. Study C and Study G instead favored Travelers under their different assumptions.
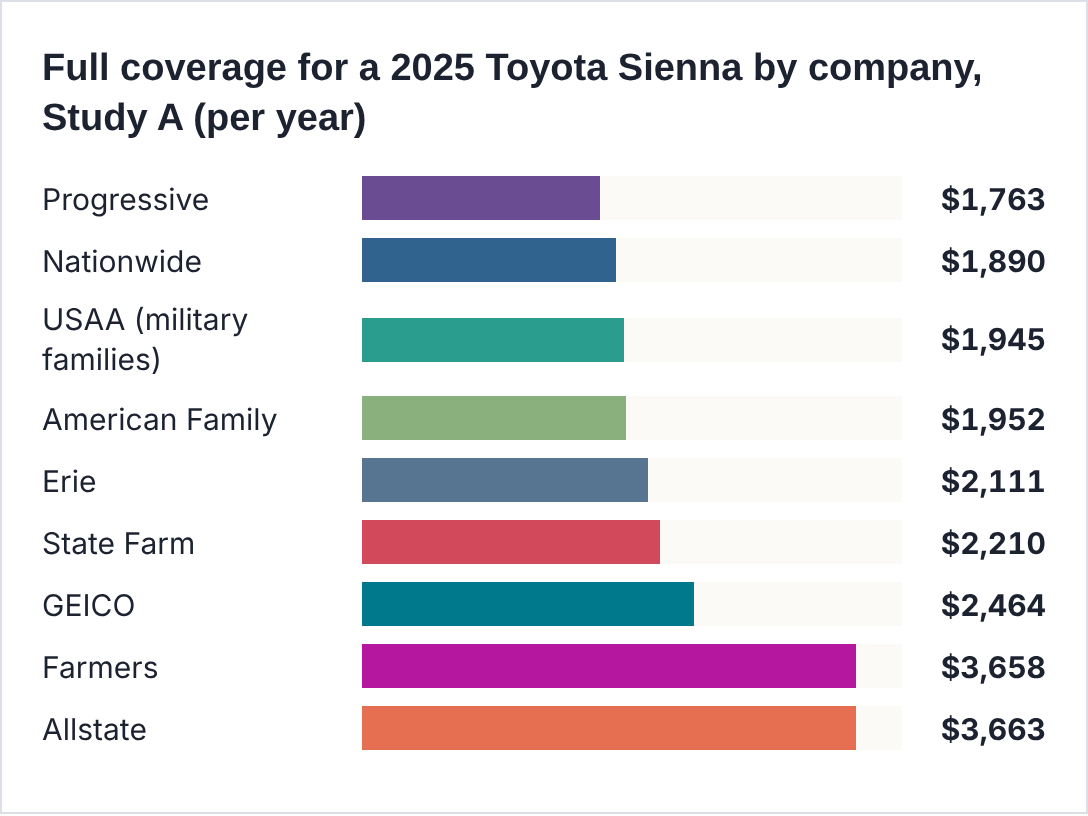
30-year-old male, full coverage, no violations. Source: Study A, Toyota Sienna insurance.
The cheapest Sienna insurer in each study
| Study | Sample driver | Cheapest open to everyone | Price |
| Study A, 2025 Sienna | 30-year-old male | Progressive | $1,763 a year |
| Study C, 2025 Sienna | 40-year-old, $500 deductible | Travelers | $1,848 a year |
| Study G, 2025 Sienna | 40-year-old male, $1,000 deductible | Travelers | $179 a month |
| Study G, all model years | 40-year-old male, $1,000 deductible | GEICO | $130 a month |
| Study H | 40-year-old male, $500 deductible | Progressive | $1,905 a year |
| Study F, Texas | 30-year-old, $500 deductible | Farm Bureau | $106 a month |
How to get your lowest Sienna quote
- Note your model year, trim, and whether your Sienna has all-wheel drive.
- List every driver in the home, including teens with a permit.
- Get quotes from Progressive, Travelers, GEICO, and Nationwide, plus USAA if you qualify.
- Compare the same limits at a $500 and a $1,000 deductible.
- Ask which discounts are included, and request any that are missing.
How we ranked these insurers
We reviewed eight published or updated rate studies (A–H), primarily from 2025–2026, with different samples and some shared or overlapping underlying data. Companies were selected editorially for competitive published results and relevant coverage. No statistical weighting formula, uniform national quote set or independently obtained policy quotes were used. Financial strength, complaints and regional customer satisfaction are additional context, not Sienna-specific scores. Independent profiles must not be treated as eight independent experiments.
Toyota Auto Insurance
Toyota has promoted a branded insurance-shopping program through Toyota Insurance Management Solutions and partner companies. Its participating insurers, policy administrator and geographic availability can change; verify the current underwriting carrier and eligibility on Toyota’s official insurance channel before treating it as a quote option. A branded offering does not necessarily mean Toyota itself underwrites the policy.
How the Sienna compares with other Toyotas
In the cited Study C sample, the Sienna’s overall model average is $2,766 annually, placing it above some Toyota models and below others. That overall model average should not be confused with the detailed 2025 Sienna figure of $2,581 on Insurance.com’s model-year table. Vehicle mix, driver, coverage and methodology can change these comparisons.
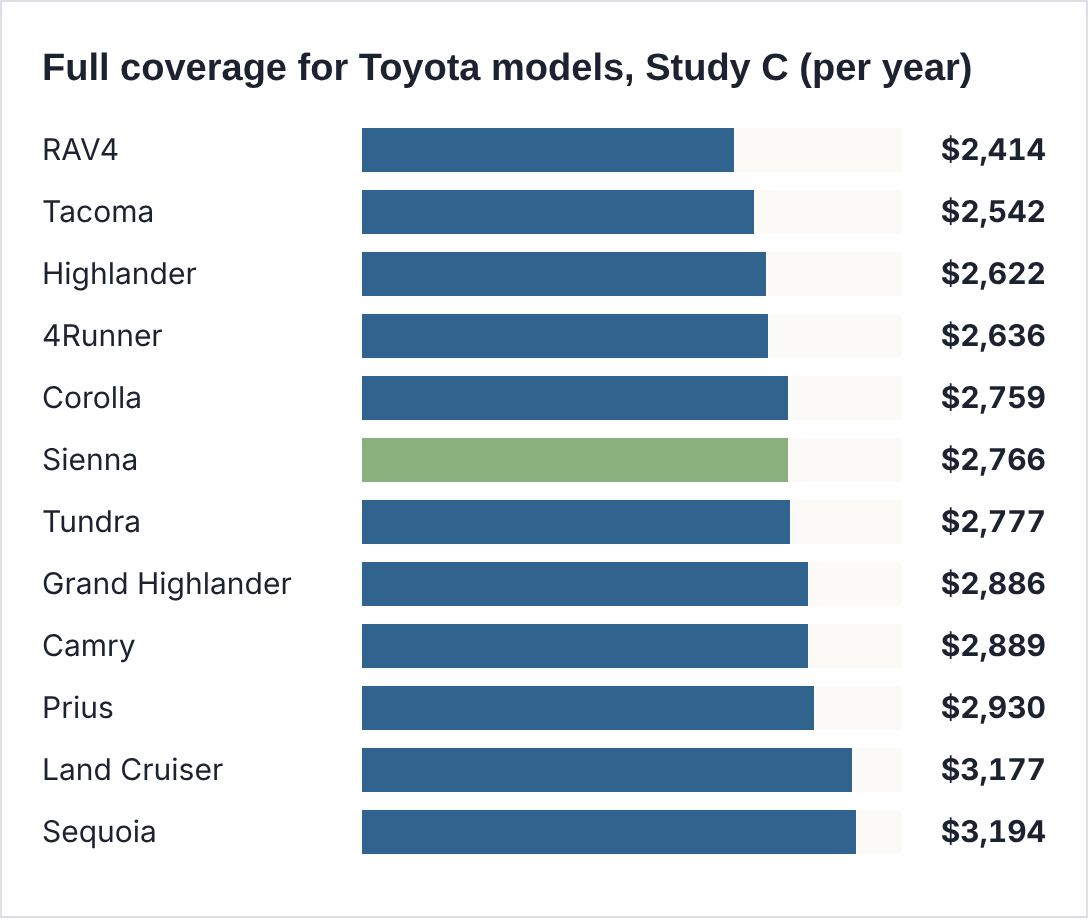
40-year-old driver, clean record, 100/300/100 with a $500 deductible. Source: Study C, Toyota insurance, October 26, 2026.
Liability coverage tells a different story. Study B found the Sienna has the lowest average liability premium of any Toyota it tracks, $88 a month, and Study C’s 50/100/50 liability price of $1,109 a year is near the bottom of Toyota’s range too.
Collision and comprehensive costs can increase with the vehicle’s insured value, repair parts and loss experience. Toyota listed the 2026 LE FWD at $40,120 MSRP before its destination charge; the original comparison’s $41,615–$59,005 range is for selected trims including an assumed $1,495 destination charge. Actual transaction prices and insurance quotes vary.
PRO TIP #3
Trading a Highlander for a Sienna? In Study C, the minivan costs $144 a year more to insure for full coverage, but its liability price is $15 lower. Your deductible and collision choices drive the difference.
Liability-only coverage for a Sienna
Liability-only coverage generally pays covered injuries and property damage you cause to others, but not collision damage to your own Sienna. In Study G, its state-minimum sample averaged $1,076 a year; Study C lists $1,109 for 50/100/50 liability limits. These are different coverage definitions and should not be treated as equivalent.
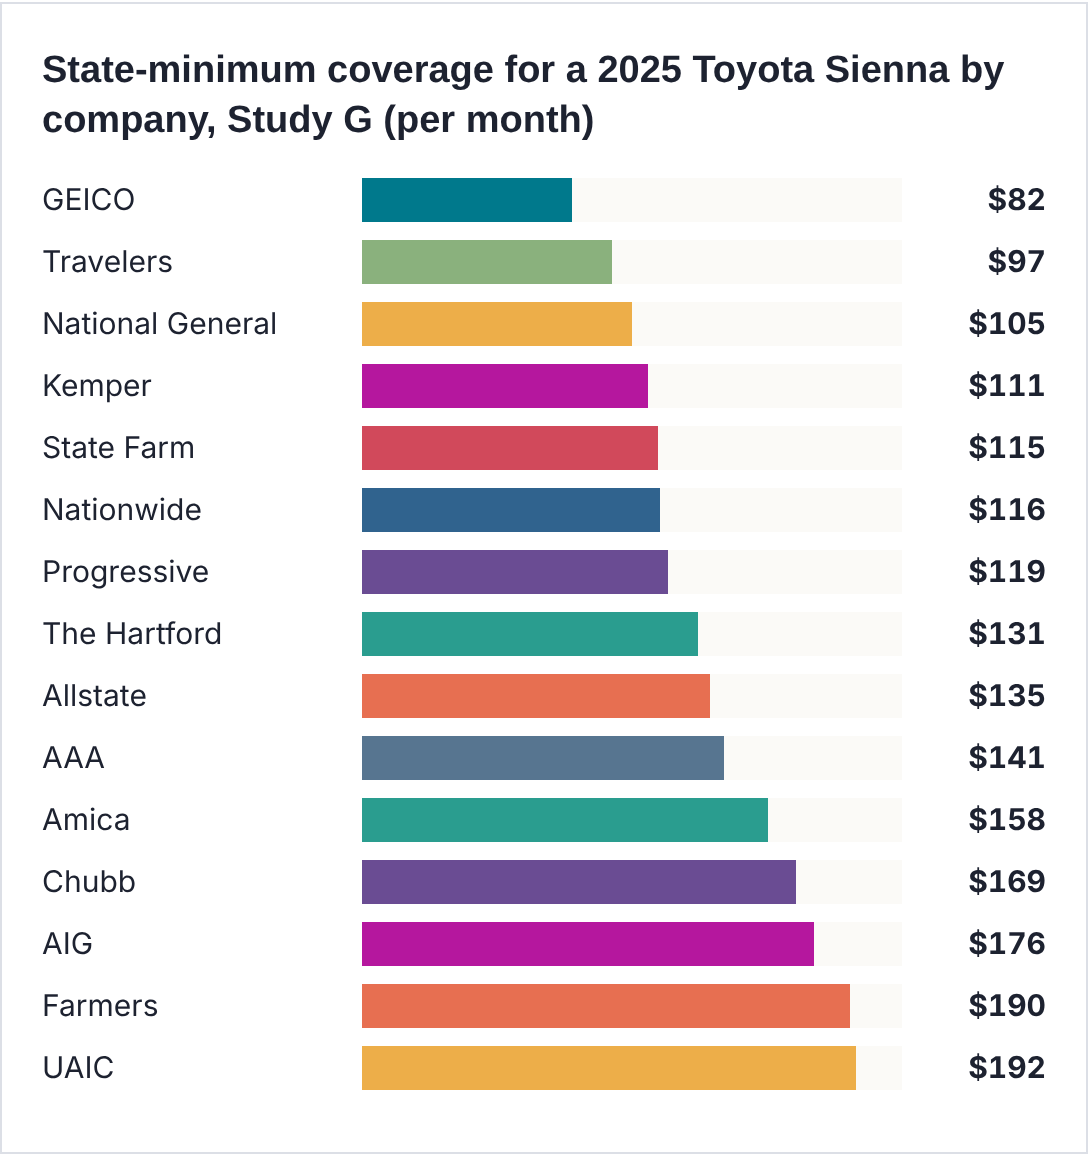
40-year-old male, clean record, good credit, state-minimum liability. Source: Study G, Toyota Sienna insurance, May 25, 2026.
For a 2025 Sienna, GEICO’s $82 a month is $110 less than UAIC’s $192, a gap of $1,320 a year for the same coverage.
When liability-only makes sense
On an older, paid-off Sienna, a liability-only policy may be worth pricing only if you could absorb the cost of a theft or total loss. A lender or lessor commonly requires collision and comprehensive under the contract; confirm the actual terms rather than assuming liability-only is an option.
PRO TIP #4
A minivan often carries several passengers, so a state-minimum policy can run out quickly after a serious crash. Even on an older Sienna, consider 100/300/100 limits with uninsured motorist coverage. For an illustration in another state, consider the financial risks of Illinois minimum liability coverage; your own state’s requirements may differ.
Full coverage for a Toyota Sienna
Full coverage adds collision and comprehensive coverage. Study C’s company figures for a 2025 Sienna range from $1,848 at Travelers to $3,743 at Farmers, a difference of $1,895 a year.
Full coverage for a 2025 Sienna by company, Study C (per year)
| Insurer | Per year | Per month |
| Travelers | $1,848 | $154 |
| USAA* | $2,010 | $168 |
| GEICO | $2,238 | $187 |
| State Farm | $2,430 | $203 |
| Nationwide | $2,445 | $204 |
| Progressive | $2,638 | $220 |
| Allstate | $3,294 | $275 |
| Farmers | $3,743 | $312 |
40-year-old driver, 100/300/100 with a $500 deductible. Monthly figures are the annual price divided by 12. *USAA sells only to military families. Source: Study C, Toyota Sienna car insurance, October 26, 2026.
Full coverage by company, Study H (per year)
| Insurer | Per year | Per month |
| Progressive | $1,905 | $159 |
| State Farm | $1,959 | $163 |
| Nationwide | $1,991 | $166 |
| GEICO | $2,068 | $172 |
| Allstate | $2,991 | $249 |
| Farmers | $3,042 | $254 |
40-year-old male, 100/300/100 with a $500 deductible. Source: Study H, Toyota Sienna car insurance cost.
Study H’s four cheapest companies sit within $163 a year of each other, while Allstate and Farmers cost more than $1,000 a year above Progressive. In practice, that means your shortlist matters more than fine differences between the leaders.
Five years of Sienna insurance
For illustration only, multiplying Study A’s annual samples by five gives $8,815 for Progressive and $18,315 for Allstate, a difference of $9,500. This is not a five-year forecast: premiums, discounts, driver ages, and vehicle value change at renewal, so the gap may narrow, widen or reverse.
Average Sienna full coverage by study
| Study | Full coverage | Sample driver |
| Study C (Oct 2026) | $2,766 a year | Overall Sienna model average; 2025-specific detail $2,581 |
| Study D (Mar 2026) | $2,766 a year | 40-year-old male, 100/300/100 |
| Study A | $2,414 a year | 30-year-old male, 2025 model |
| Study E | $2,352 a year | 40-year-old, good credit, new model |
| Study H | $2,304 a year | 40-year-old male, $500 deductible |
| Study G (May 2026) | $2,083 a year | 40-year-old male, $1,000 deductible |
| Study F (Jun 2026) | $199 a month | 30-year-old in Texas, 2023 model |
| Study B (Nov 2026) | $165 a month | Customer quotes and rate data |
Sienna insurance by trim
Toyota offered the 2026 Sienna in six trims: LE, XLE, XSE, Woodland Edition, Limited and Platinum. Study G lists 24 trim labels without consistent model years; its figures should not be interpreted as confirmed 2026 quotes for every named trim. The displayed pricing table refers to 2026 vehicles, not newly verified 2027 MSRP.
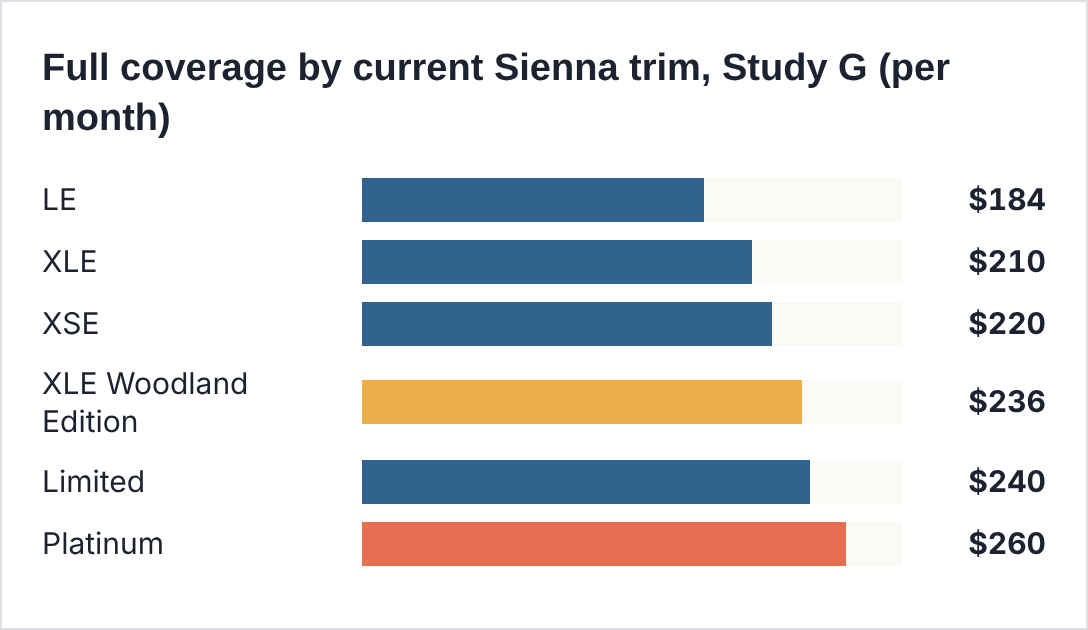
40-year-old male, 100/300/100 with a $1,000 deductible. Trim names as listed, without model years. Source: Study G, May 25, 2026.
Current Sienna trims: price and insurance
| Trim | 2026 price with destination | Study G (month) | Study H (year) |
| LE | $41,615 | $184 | $2,202 |
| XLE | $46,315 | $210 | $2,300 |
| XSE | $49,540 | $220 | $2,334 |
| Limited | $52,300 | $240 | $2,301 |
| Woodland Edition | $52,395 | $236 | $2,365 |
| Platinum | $59,005 | $260 | $2,433 |
Prices from Cars.com, October 23, 2025, including a $1,495 destination charge; the Woodland Edition and Platinum include all-wheel drive. Study G: 40-year-old male, $1,000 deductible. Study H: 40-year-old male, $500 deductible; model years not stated.
LE
The LE is the cheapest Sienna to buy and to insure, at $184 a month in Study G and $2,202 a year in Study H. For 2026, Toyota added a power liftgate, rear window shades, and an upgraded audio system as standard.
XLE
The XLE costs $210 a month in Study G, $26 more than the LE, and $2,300 a year in Study H, only $98 more.
XSE
The sporty-looking XSE costs $220 a month in Study G and $2,334 a year in Study H. For 2026, Toyota made a 12-speaker JBL sound system standard on it.
Woodland Edition
The Woodland Edition comes with all-wheel drive and costs $236 a month in Study G and $2,365 a year in Study H. Its price is almost identical to the Limited’s, and its Study G figure is only $4 a month lower.
Limited
The Limited costs $240 a month in Study G, the second-highest current trim, but in Study H it costs about the same as an XLE, at $2,301 a year.
Platinum
The Platinum is the most expensive Sienna to buy and to insure in both studies, at $260 a month in Study G and $2,433 a year in Study H. That is $76 a month, or $912 a year, more than an LE in Study G.
Front- or all-wheel drive
All-wheel drive adds $2,000 to the price of an LE, XLE, XSE, or Limited and is standard on the Woodland Edition and Platinum. No study separates insurance prices by drivetrain, so ask for quotes on both if you are undecided.
PRO TIP #5
Deciding between an XLE and a Limited? In Study G, the Limited costs $30 a month more to insure. Over five years, that adds about $1,800 on top of the higher purchase price.
Insurance for older Sienna trims
The third-generation Sienna, sold from 2011 to 2020, used a V6 engine and came in trims such as L, LE, SE, XLE, and Limited, with Premium packages on some. Study G lists these with the “Minivan 4d” label, and most cost less to insure than today’s hybrids.
Older Sienna trim names, Study G (per month)
| Trim as listed | State minimum | Full coverage |
| CE Minivan | $63 | $122 |
| LE Minivan | $68 | $130 |
| XLE Minivan | $69 | $133 |
| LE Minivan 4d | $81 | $157 |
| XLE Limited Minivan 4d | $85 | $164 |
| SE Minivan 4d | $86 | $166 |
| L Minivan 4d | $87 | $169 |
| XLE Minivan 4d | $88 | $170 |
| Limited Minivan 4d | $92 | $179 |
| XLE Premium Minivan 4d | $93 | $180 |
| Limited Premium Minivan 4d | $95 | $184 |
| XSE Minivan 4d | $95 | $186 |
| SE Premium Minivan 4d | $98 | $189 |
| XSE 25th Anniversary Edition Minivan 4d | $112 | $219 |
| Platinum Minivan 4d | $118 | $229 |
| XLE Woodland Edition Minivan 4d | $131 | $254 |
40-year-old male, $1,000 deductible for full coverage. Trim names as listed, without model years, so some names may cover more than one generation. Source: Study G, May 25, 2026.
The cheapest names on the list, such as the CE and the plain LE and XLE Minivan, likely belong to the oldest Siennas, at $122 to $133 a month. The 25th Anniversary Edition, sold for 2023, and the Woodland Edition listing at $254 sit at the top.
Sienna insurance by model year
Older Siennas cost less to insure, and the drop is steady. Study A’s averages for a 30-year-old fall from $2,414 a year for a 2025 Sienna to $1,398 for a 2011, a decline of about 42%.
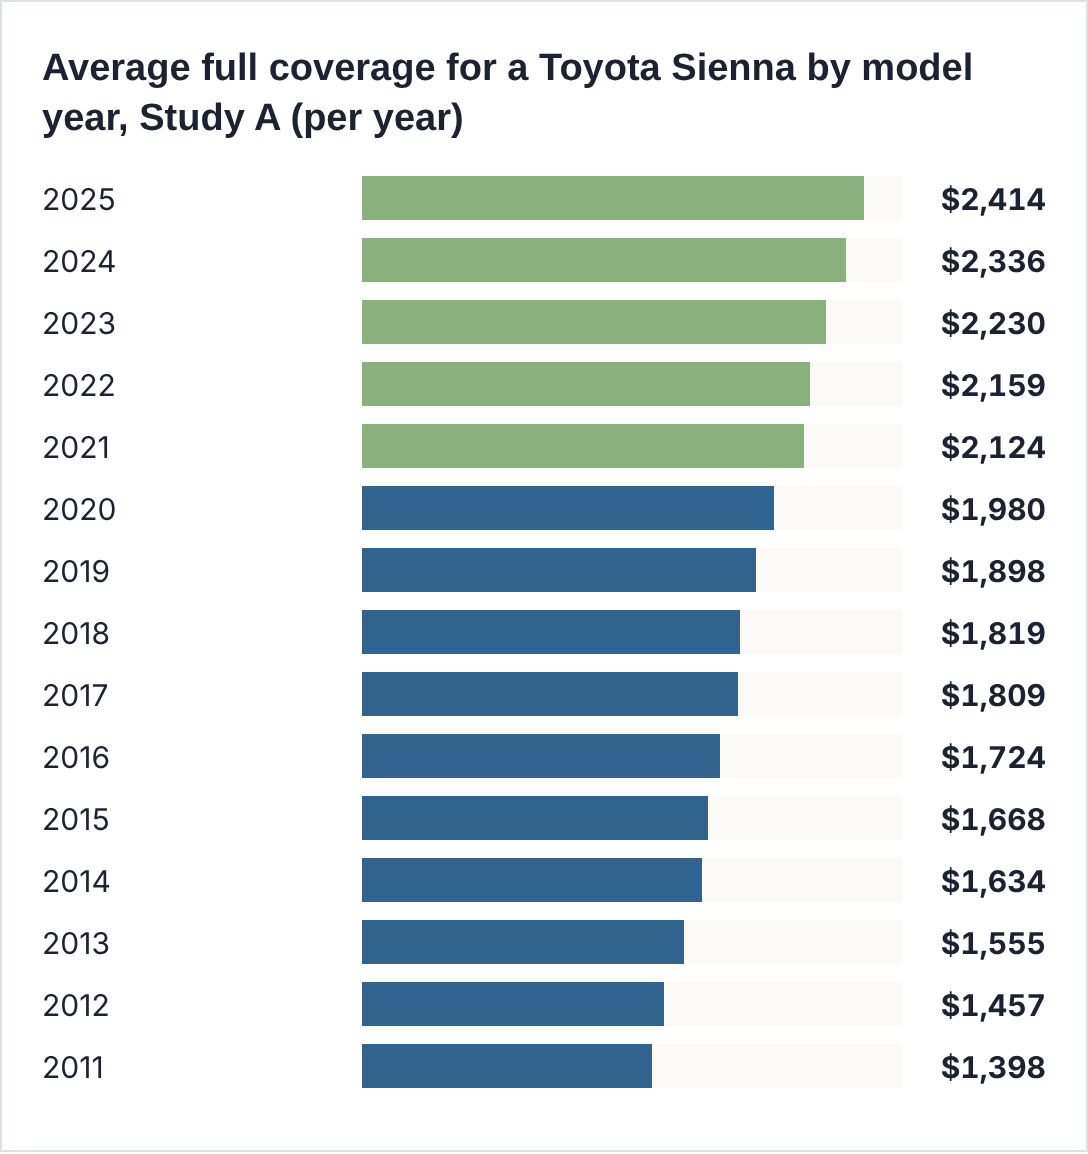
30-year-old male, full coverage. Source: Study A, Toyota Sienna insurance.
Sienna insurance by model year in two more studies
| Model year | Study C average (year) | Study C cheapest: Travelers (year) | Study F, Texas (month) |
| 2025 | $2,581 | $1,848 | — |
| 2024 | $2,546 | $1,861 | — |
| 2023 | $2,475 | $1,811 | $199 |
| 2022 | $2,409 | $1,780 | $195 |
| 2021 | $2,365 | $1,740 | $193 |
| 2020 | — | $1,708 | $193 |
| 2019 | — | $1,697 | $188 |
| 2018 | — | $1,651 | $185 |
| 2017 | — | — | $178 |
| 2016 | — | — | $176 |
| 2015 | — | — | $169 |
Study C: 40-year-old, 100/300/100 with a $500 deductible, October 2026. Study F: 30-year-old in Texas, full coverage with a $500 deductible, June 2026. A dash means the study did not publish that figure. Its 2025 model-year detail ($2,581) differs from the $2,766 overall model average highlighted elsewhere.
Hybrid generation vs. V6 generation
Study A’s sample shows that Siennas from the 2021–2025 hybrid generation averaged about $2,253 a year, versus approximately $1,694 for the 2011–2020 V6 generation. That does not establish that hybrid technology caused the $559 gap: the newer vehicles also have different age, insured values and equipment.
PRO TIP #6
Buying used? In Study A, some 2018–2020 Siennas were less costly to insure than selected 2023–2025 models, but the difference reflects both generation and vehicle age. Before buying a used Sienna, check the specific vehicle identification number (VIN) for any open safety recall.
Recalls and crash-test results
Two significant seat-related recall campaigns were announced for specific Sienna vehicles, including certain 2025 units and certain 2022–2026 seven-passenger hybrids. Not every vehicle in those model years is affected. Check the vehicle identification number (VIN) through NHTSA’s official recall lookup and ask a Toyota dealer about the remedy and appointment availability.
- In October 2025, Toyota announced a separate seat-rail weld recall for certain 2025 Siennas (NHTSA campaign 25V668). Verify whether a specific VIN is included and whether the dealer has performed the free remedy.
- Toyota announced recall NHTSA 26V690 in October 2026 for up to 228,367 certain 2022–2026 Sienna Hybrid seven-passenger vehicles. A second-row seatback might not remain secured in a crash. Dealers are to update SRS ECU software, while vehicles with the MaaS package require second-row seatback replacement. Repairs are free. Owner notification letters were scheduled for December 7, 2026; actual remedy status should be checked by VIN.
A recall notice does not automatically change an individual insurance premium, but its effect on claims experience or rates cannot be ruled out universally. An unrepaired defect presents a safety risk regardless of insurance cost. Check affected VINs and repair status at NHTSA.
IIHS and federal ratings
The IIHS 2026 Toyota Sienna ratings show Good results in the small-overlap front and updated side evaluations, but an overall Marginal grade in the updated moderate-overlap front crash test, with poor protection measures for a rear passenger. It therefore did not qualify for a 2026 IIHS Top Safety Pick award. These are crash-safety findings, not evidence of a specific insurance discount.
In federal testing, a third-party listing shows the 2026 Sienna Hybrid with all-wheel drive at five stars overall, four for frontal crashes, five for side crashes, and four for rollover. The Sienna uses Toyota Safety Sense 2.0, whose pedestrian crash prevention IIHS rates Acceptable.
PRO TIP #7
Follow the manufacturer’s seating and child-restraint guidance for every row. The IIHS results identify a rear-passenger protection concern; neither booster seats nor careful belt placement eliminates a vehicle-design weakness. Use age-, height- and weight-appropriate restraints for every child.
Sienna insurance vs. other minivans
In Study D’s selected 40-year-old sample, the Sienna cost $280 more annually than the Honda Odyssey and $80 more than the Kia Carnival. This does not prove that the Sienna is the most expensive major minivan for every driver or insurer. Differences in model year, fuel economy, repair cost and actual quotes should all inform the decision. The broader list of lower-cost vehicles to insure offers context for comparing a minivan with other body styles; those prices likewise reflect sample drivers.
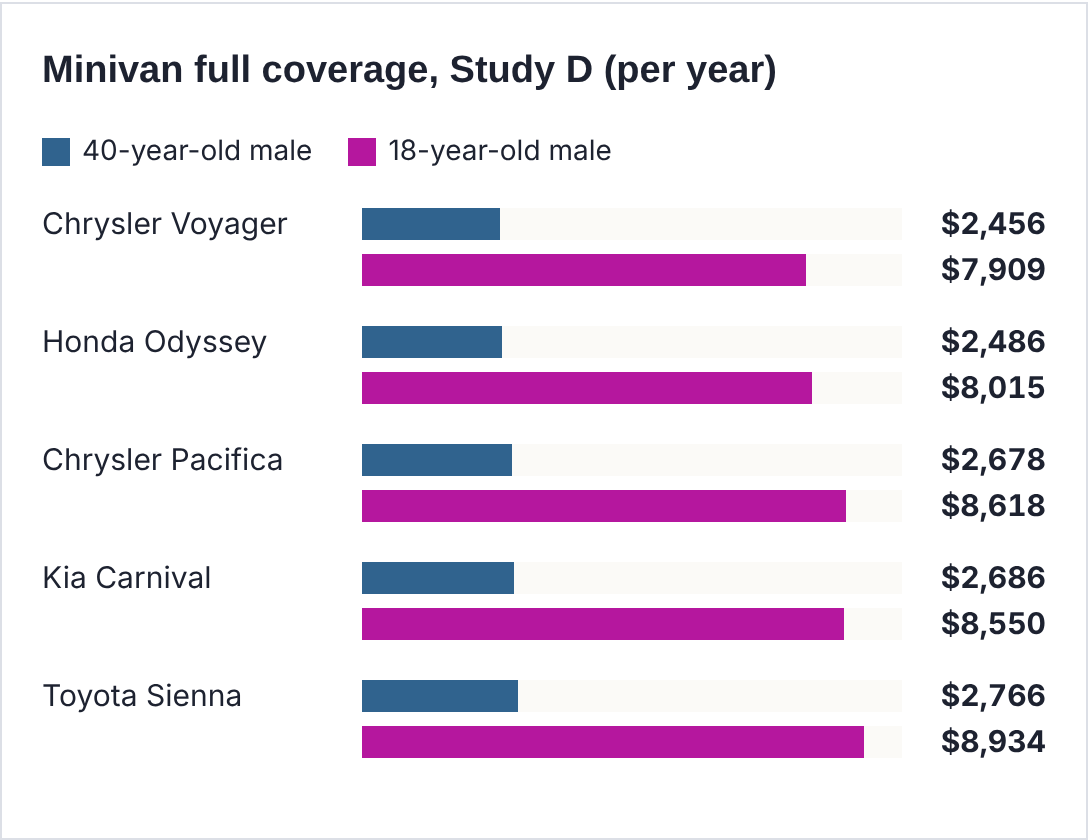
100/300/100 full coverage. Source: Study D, Toyota, Honda, Kia, and Chrysler insurance cost pages, March 23, 2026.
For an 18-year-old, the Sienna’s $8,934 a year is $919 more than the Odyssey’s $8,015. Families with a teen driver who are choosing between the two should price both.
Is the Sienna worth the higher premium?
The Sienna is sold as a hybrid-only minivan; Toyota rates some front-wheel-drive versions at approximately 36 mpg combined. Whether its potentially higher sample insurance cost is offset by fuel savings depends on the vehicles compared, local fuel prices, annual mileage and purchase price. Do not assume insurance differences alone determine total ownership cost.
Sienna insurance by state
Your state can change your bill more than any trim choice. Study G’s full-coverage figures range from $96 a month in Maine to $380 in Louisiana.
Cheapest and most expensive states for Sienna full coverage, Study G (per month)
| Cheapest states | Per month | Most expensive states | Per month |
| Maine | $96 | Louisiana | $380 |
| Idaho | $98 | Nevada | $281 |
| Vermont | $98 | Florida | $274 |
| Wyoming | $103 | Michigan | $270 |
| Hawaii | $105 | New Jersey | $241 |
| New Hampshire | $111 | Maryland | $231 |
40-year-old male, full coverage with a $1,000 deductible. Source: Study G, May 25, 2026.
Full coverage for a 2025 Sienna LE in Florida by company, Study C (per year)
| Insurer | Per year |
| Nationwide | $2,025 |
| State Farm | $2,127 |
| Travelers | $2,370 |
| UAIC | $2,669 |
| GEICO | $3,030 |
| Mercury | $3,166 |
| Allstate | $3,463 |
| Farmers | $3,513 |
| Progressive | $4,178 |
| AIG | $5,647 |
Florida shows how much rankings can shift. Nationwide is cheapest there at $2,025 a year for a 2025 Sienna LE, while Progressive, the national price leader in Study A, is the second-most expensive at $4,178. Broader provider comparisons, including The General versus Progressive in Florida, illustrate coverage questions but should not replace a Sienna-specific quote.
Sienna insurance in large states
Sienna full coverage in large states (per month)
| State | Study G ($1,000 deductible) | Study H ($500 deductible) |
| California | $172 | $240 |
| Texas | $225 | $256 |
| Florida | $274 | $226 |
| New York | $195 | $143 |
| Illinois | $152 | $189 |
| Pennsylvania | $184 | $206 |
| Ohio | $130 | $135 |
| Georgia | $214 | $240 |
| North Carolina | $145 | $189 |
| Michigan | $270 | $248 |
40-year-old male driver in both studies. Sources: Study G, May 2026, and Study H.
The two studies disagree in some states, such as New York, where Study G’s figure is $52 a month higher, and California, where Study H’s is $68 higher. They use a different deductible and different data, which is one more reason to compare your own quotes.
PRO TIP #8
Live in Texas? Study F, which priced every Texas ZIP code, found Farm Bureau cheapest at an average of $106 a month for a Sienna there, so a Farm Bureau quote is worth getting. For families budgeting the total first payment, Texas car insurance down-payment and installment terms are a separate consideration from the monthly Sienna rate.
How age, accidents, and credit affect Sienna rates
Study E shows how the same Sienna is priced for different drivers. A 40-year-old with a clean record and good credit pays $2,352 a year. One recent at-fault accident raises that to $3,454, and poor credit raises it to $4,040, about 72% more.
Sienna insurance by age and driver profile, Study E (per year)
| Age | Good driver and credit | Recent at-fault accident | Poor credit |
| 18 | $7,424 | $10,902 | $12,754 |
| 25 | $3,352 | $4,922 | $5,758 |
| 30 | $2,611 | $3,834 | $4,485 |
| 40 | $2,352 | $3,454 | $4,040 |
| 55 | $2,099 | $3,082 | $3,606 |
Full coverage on a new Sienna, about 13,000 miles a year, single-car policy. Source: Study E, Toyota Sienna insurance.
The comparison source says California, Hawaii and Massachusetts restrict credit-based factors for auto insurance rates. In the study sample, poor credit was associated with higher rates in states permitting its use. The premium difference is an association within the sample, not proof that credit alone caused it. State rules and insurers’ permitted rating factors should be verified individually.
Getting back on track after a claim
- Shop at your next renewal. Companies weigh accidents differently, so your current insurer may no longer be the cheapest.
- Ask about accident forgiveness before you need it.
- Complete a defensive driving course if your state allows a discount or point reduction for it.
- Join a usage-based program to earn a discount for safe driving now.
PRO TIP #9
Before reporting a small incident, review your deductible and policy obligations; do not withhold a report that your policy or state law requires. Study E’s modeled difference between a clean record and a recent at-fault accident is $1,102 annually for one 40-year-old Sienna profile, not a forecast of your individual surcharge.
10 discounts for Sienna owners
These discounts come from each insurer’s own pages. Availability and amounts vary by state, and the percentages are maximums or averages, not promises. When comparing annual and monthly premiums, check monthly insurance payment plans and installment fees alongside percentage discounts.
1. Bundle home and auto
Progressive says bundling customers save over $1,000 a year on average, Nationwide says $1,032, and The Hartford says $963. Farmers lists 10% or more.
2. Insure several vehicles
GEICO offers up to 25% off for more than one vehicle, and Progressive says its multi-car customers save 12% on average, useful when a Sienna shares a policy with a second car.
3. Good student
State Farm offers up to 25% for students with good grades, GEICO up to 15%, and Progressive about 5%.
4. Safe-driving programs
State Farm’s Drive Safe & Save offers up to 30%, Liberty Mutual’s RightTrack up to 30%, and USAA’s SafePilot 10% for joining and up to 30% at renewal. Nationwide’s SmartRide offers 10%, and Progressive says Snapshot users save $328 a year on average.
5. Clean record
GEICO offers up to 22% for drivers with five years free of accidents.
6. Hybrid vehicle
Every current Sienna is a hybrid, and The Hartford’s AARP program lists a discount for hybrid and electric vehicles. It does not publish the amount, so ask.
7. Safety equipment
State Farm offers up to 40% off certain medical coverages for factory airbags, and GEICO lists 5% for anti-lock brakes.
8. Newer vehicle
Travelers offers a discount on cars less than three years old in most states, though not in California.
9. Online quote and paperless signing
Progressive offers about 7% for an online quote and about 10% for signing documents online, and The Hartford lists 8% for an online quote.
10. Military and mature drivers
GEICO offers up to 15% for military members, and The Hartford takes 10% off for AARP members. See the senior and military sections below for more.
PRO TIP #10
Ask each company for the final quoted premium after eligible discounts, and verify what each discount applies to. Advertised percentage and dollar savings often apply to specific coverages or customer samples and generally cannot be added together to predict a total discount.
Sienna insurance for teen drivers
Adding a newly licensed driver can substantially increase a family premium. Study D’s $8,934 annual figure is a modeled standalone Sienna-related sample for an 18-year-old male, while other tables report the incremental cost of adding a teenager to a household policy. These are different measures and must not be compared as if they were identical quotes. Families preparing for the next stage may also compare car insurance options for college students, whose eligibility and discounts differ by carrier.
No study publishes Sienna prices by company for each teen age, so the sections below combine Sienna figures with national data on adding a teen to a family policy.
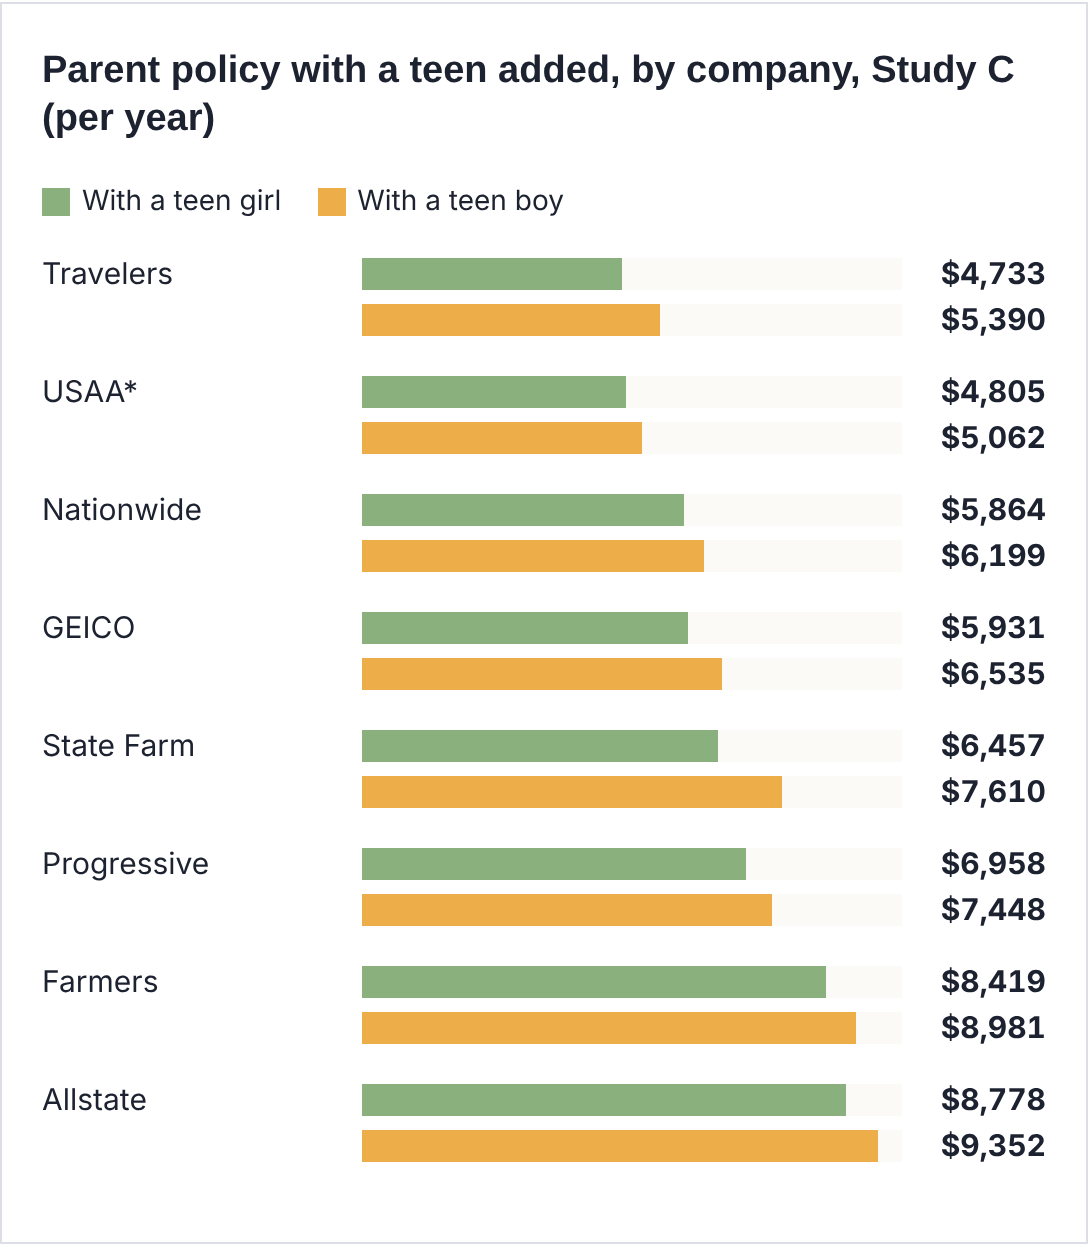
Total family premium with a teen on a parent’s full-coverage policy. National data, no specific test vehicle. *USAA sells only to military families. Source: Study C, teen car insurance costs, August 13, 2026.
Travelers had the lowest family total with a teen girl in Study C, at $4,733 a year, and USAA had the lowest with a teen boy, at $5,062. On average, adding a teen raised a family’s premium by $4,515 a year.
Cheapest Toyota Sienna insurance for a 16-year-old
Adding a 16-year-old costs about $4,050 a year in Study D, more than at any other teen age. A separate policy is far more expensive: GEICO was the cheapest national company for a 16-year-old on their own policy in Study C, at $8,436 a year.
Cheapest Toyota Sienna insurance for a 17-year-old
At 17, adding a teen costs about $3,740 a year in Study D, and GEICO remained the cheapest national company for a 17-year-old with a separate policy in Study C, at $6,937.
Cheapest Toyota Sienna insurance for an 18-year-old
Eighteen has the most Sienna data. Study F found an 18-year-old in Texas pays $647 a month for a 2023 Sienna and $588 for a 2015, about $708 a year apart. Nationally, Travelers was cheapest for an 18-year-old with a separate policy in Study C, at $5,566, and adding an 18-year-old to a family policy costs about $3,478 in Study D.
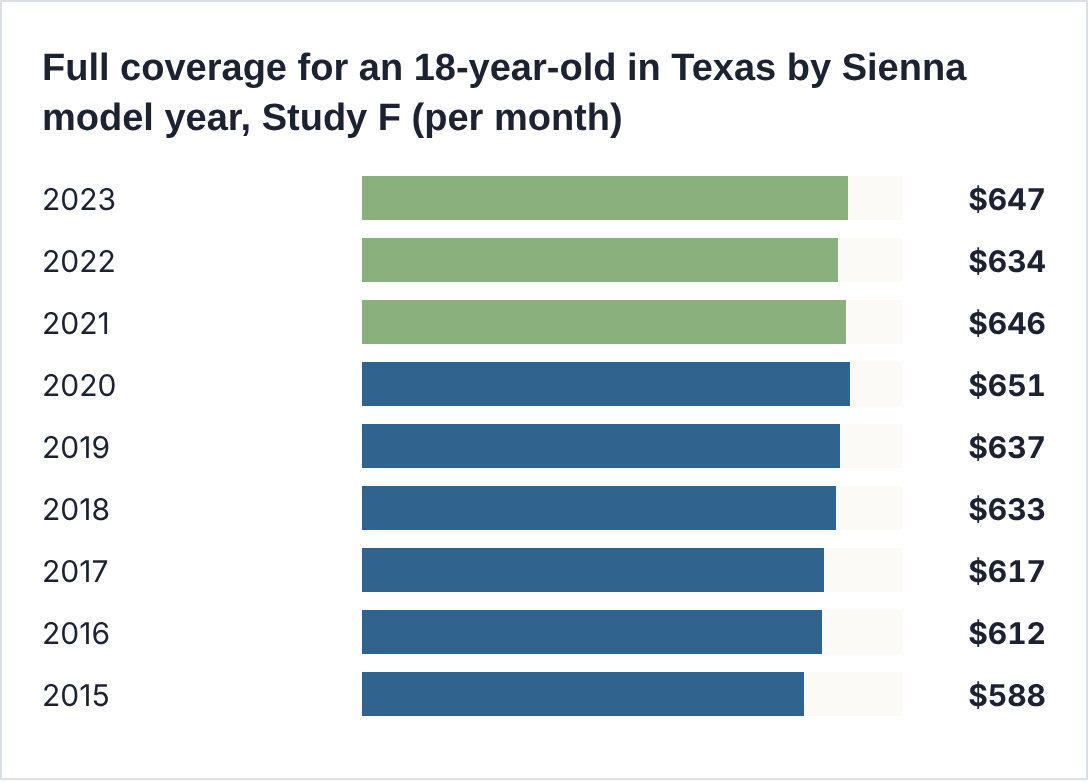
18-year-old driver in Texas, full coverage with a $500 deductible. Source: Study F, cost of Toyota car insurance, June 30, 2026.
Cheapest Toyota Sienna insurance for a 19-year-old
By 19, adding a teen costs about $3,105 a year in Study D, the lowest of the four teen ages, and Travelers stays the cheapest national company for a 19-year-old with a separate policy in Study C, at $4,465.
Ways to lower a teen’s Sienna premium
- Ask whether insuring an eligible teen on the household policy costs less than separate coverage; disclose the actual primary driver and the garaging location.
- If the teen will drive the Sienna, consider an older model or an LE, the cheapest trim in Studies G and H.
- Claim good student discounts of up to 25% at State Farm and up to 15% at GEICO.
- Sign the teen up for a safe-driving app, and requote at each birthday from 16 to 19.
PRO TIP #11
Study F’s Texas data shows the 2020 Sienna, the last V6 year, costing an 18-year-old about the same as a 2021 hybrid. Do not assume an older minivan is cheaper for a teen: get quotes on the exact years you are considering.
Coverage choices for a family minivan
Coverage needs depend on your financial exposure and contract terms, not simply the number of seats. For families using a Sienna as their primary vehicle, liability limits, uninsured/underinsured motorist coverage, rental reimbursement and appropriate child-seat replacement provisions deserve comparison.
- Higher liability limits. With up to eight seats, one crash can injure several people. Limits of 100/300/100 or higher protect your savings better than a state minimum.
- Uninsured and underinsured motorist coverage. It pays your family’s medical bills when the at-fault driver has too little insurance or none.
- Medical payments or personal injury protection. These pay medical bills for you and your passengers regardless of fault, and personal injury protection is required in no-fault states.
- Rental reimbursement. Check that the daily limit is high enough to rent a minivan or large SUV.
- Gap insurance. On a new loan or lease with little money down, it covers the difference between your balance and the minivan’s value if it is totaled.
PRO TIP #12
Ask whether your policy pays to replace child car seats after a crash. Federal guidance calls for replacing a car seat after a moderate or severe crash, and coverage for it varies by insurer.
Sienna insurance for senior drivers
Age-based prices are sample estimates, not universal senior discounts. Study E lists $2,099 annually for a 55-year-old Sienna driver with a clean record and good credit. The separate Study D figures for ages 65–75 are not Sienna-specific, so they should not be presented as the premium an older Sienna owner will receive.
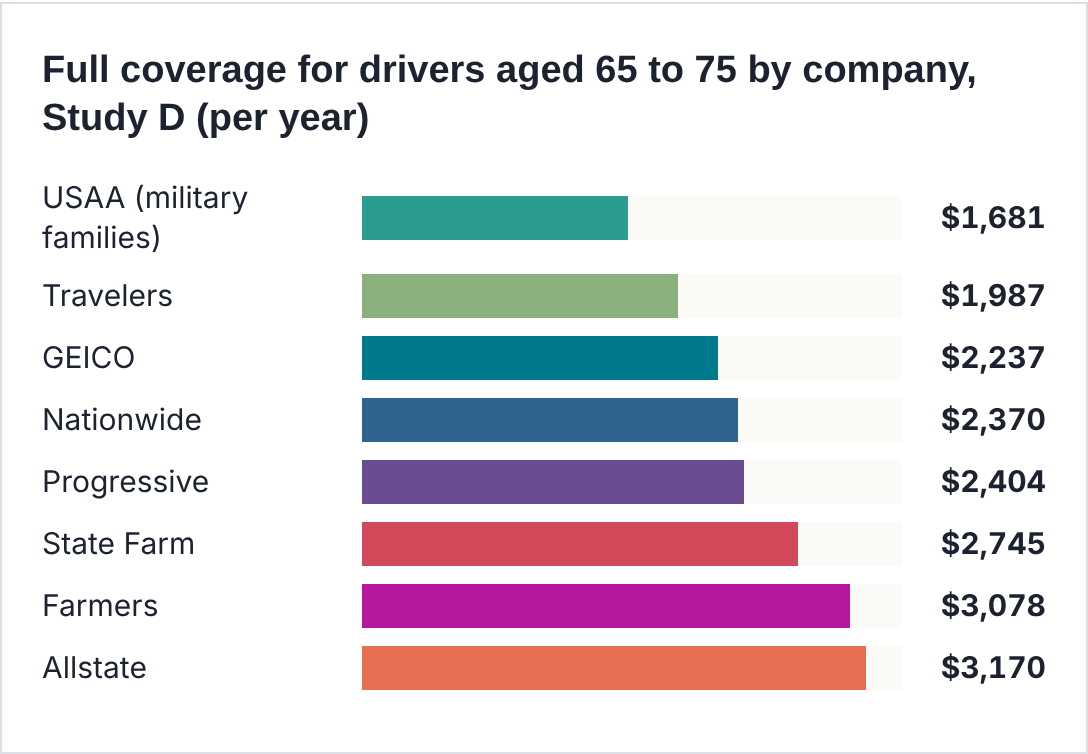
100/300/100 with a $500 deductible; no test vehicle named. Source: Study D, car insurance for seniors, April 16, 2026.
Travelers, the cheapest company for a 2025 Sienna in Study C, also has the lowest senior rate among companies open to everyone in Study D, at $1,987 a year.
Savings tips for older Sienna owners
- Complete an approved mature driver course. AARP says 33 states and Washington, D.C., require insurers to give a discount for one, and Kiplinger reports savings of up to 10%.
- Get a quote from The Hartford’s AARP program, which lists 10% off for AARP members, 5% for a defensive driving course, up to 15% through its TrueLane app, and a hybrid and electric vehicle discount.
- Report lower mileage after retirement.
- Keep liability limits high if you often drive grandchildren.
Pay-per-mile for a minivan that stays home
For low-mileage Sienna owners, genuine pay-per-mile insurance may be worth comparing with a conventional annual policy. Nationwide SmartMiles and other programs have state, vehicle and underwriting restrictions; do not assume the same base rate, daily cap, or availability applies to everyone. This is different from prepaid or pay-as-you-go car insurance arrangements, which are not necessarily priced by mileage.
Sienna insurance for military families
USAA is a strong choice for military families with a Sienna. It charges $1,945 a year for a 2025 model in Study A and $2,010 in Study C; it was the cheapest company in Study A for every Sienna from 2011 to 2015, and it earned the highest J.D. Power scores in every region in 2026.
Full coverage for military members vs. civilians, Study D (per year)
| Insurer | Military | Civilian | Military savings |
| USAA | $1,465 | $1,572 | $107 |
| Travelers | $1,818 | $2,103 | $285 |
| Auto-Owners | $1,908 | $2,051 | $143 |
| GEICO | $1,951 | $2,148 | $197 |
| Nationwide | $2,210 | $2,463 | $253 |
| Progressive | $2,382 | $2,675 | $293 |
| State Farm | $2,575 | $2,874 | $299 |
| Farmers | $2,676 | $3,085 | $409 |
| Allstate | $2,698 | $3,205 | $507 |
Full coverage; no test vehicle named. Savings are our subtraction. Source: Study D, best car insurance for military members, August 13, 2026.
Every company in Study D charged military members less than civilians. Travelers had the lowest military price after USAA, at $1,818 a year, and Allstate gave the largest dollar discount, $507.
Military discounts to ask about
- USAA advertises up to 60% off for a vehicle in storage, except in North Carolina and Virginia, and up to 15% off comprehensive coverage for a vehicle garaged on a base.
- GEICO offers up to 15% for active-duty, retired, Guard, and Reserve members and up to 25% when you are deployed overseas.
- Armed Forces Insurance can arrange auto coverage for military families through partner insurers.
PRO TIP #13
Moving the family to a new duty station? Report the Sienna’s new garaging address before the move, and get fresh quotes there, since the cheapest company can change from state to state.
Sienna insurance savings, drawn out
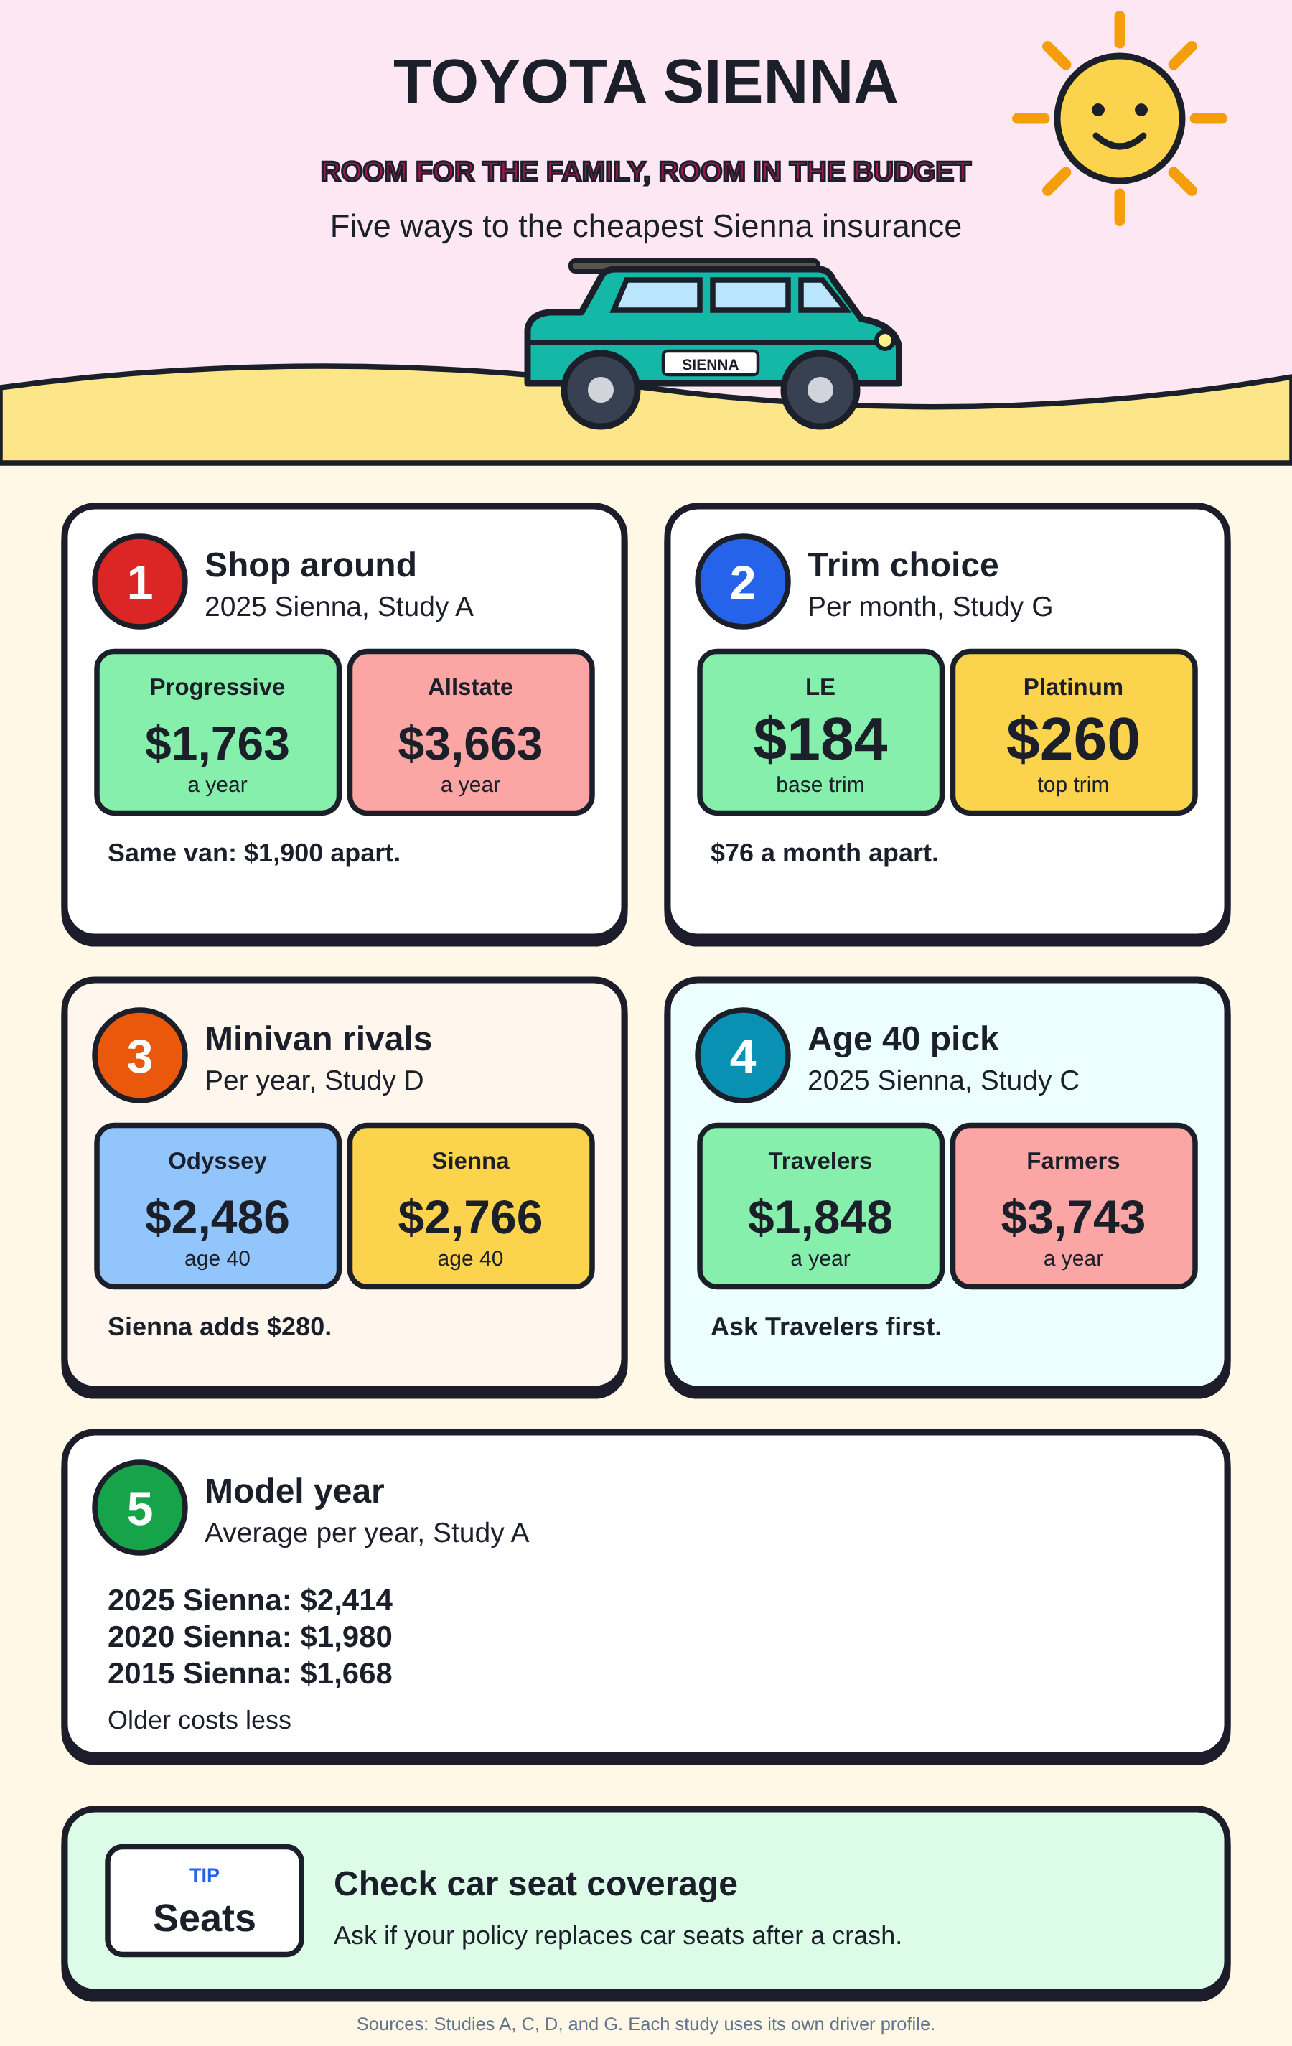
Graphic data note: The illustrated savings are based on hypothetical study samples; they are not a forecast of the savings an individual Sienna driver will obtain.
An original cartoon summary of five ways to get the cheapest Sienna insurance.
FAQs on the cheapest Toyota Sienna insurance
Which company has the cheapest Sienna insurance?
Progressive had the lowest 2025 Sienna price in Study A at $1,763 a year and the lowest in Study H. Travelers led Study C for a 40-year-old at $1,848, and GEICO had the lowest all-years average in Study G.
How much does Sienna insurance cost per month?
Full coverage for a 40-year-old runs about $174 to $231 a month in most studies. Liability-only coverage is about $92 a month in Study C and $88 in Study B.
Is the Sienna expensive to insure?
It was costlier than certain rival minivans in Study D’s sample. Prices differ by insurer, vehicle year and household, so the Sienna is not necessarily more expensive in every comparison.
Which Sienna trim is cheapest to insure?
The LE, at $184 a month in Study G and $2,202 a year in Study H. The Platinum is the most expensive.
Does a hybrid Sienna cost more to insure than an older V6?
Study A found higher sample premiums on 2021–2025 Siennas than on 2011–2020 models, but the data does not isolate the hybrid drivetrain from vehicle age, replacement value and model changes.
Is the Sienna an IIHS Top Safety Pick?
No. No minivan earned a 2026 award, and the Sienna scored Marginal in the updated moderate overlap test because of weak rear-seat protection.
Is my Sienna part of a recall?
If it is a 2022 to 2026 model with second-row captain’s chairs, or a 2025 model, it may be. Check your VIN at nhtsa.gov.
How much is Sienna insurance for a teen?
Study D gives $8,934 a year for one 18-year-old male Sienna sample. Separate studies report different prices for adding a teen to a household policy. Request a quote identifying the actual driver and vehicle assignment.
Does all-wheel drive raise Sienna insurance costs?
The cited studies do not isolate the cost of all-wheel drive, so no fixed insurance increase can be established. Compare quotes for the exact FWD and AWD versions before buying.
Does credit affect Sienna insurance?
In most states, yes. In Study E, poor credit raises a 40-year-old’s price from $2,352 to $4,040 a year. California, Hawaii, and Massachusetts do not allow it.
Is the Sienna cheaper to insure than a Grand Highlander?
Yes. Study C puts the Sienna at $2,766 a year, $120 less than the gas Grand Highlander, and its liability-only price is $25 lower.
Are 2027 Sienna insurance rates available?
We did not find a reliable published 2027 Sienna model-specific insurance-rate study at the time of this review. Toyota’s official U.S. newsroom still displayed 2026 Sienna product specifications rather than a confirmed 2027 national price table. Obtain quotes using the vehicle identification number (VIN) once available.
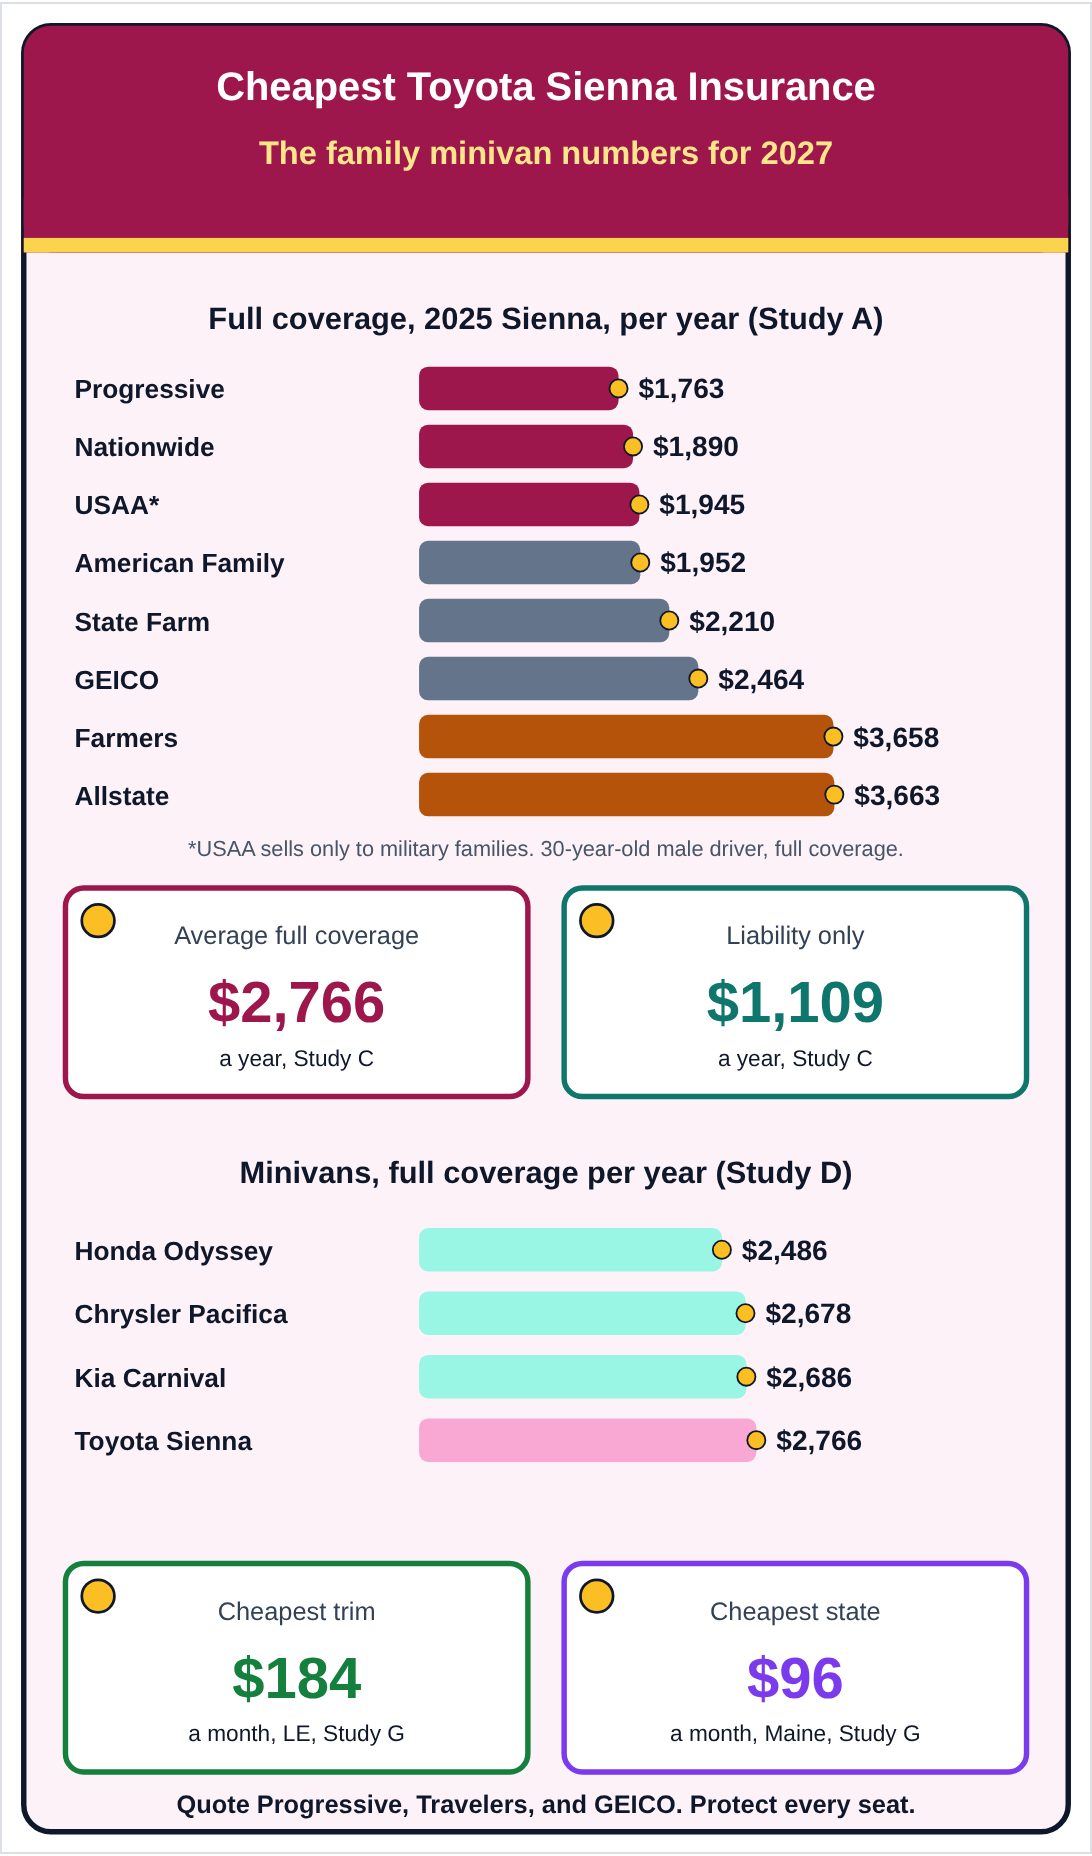
Graphic data note: This original summary image may display older average-price labels. Refer to the corrected model-year tables and sources in the article for updated figures.
Sienna insurance at a glance.
The final word on the cheapest Toyota Sienna insurance
In the cited published samples, the Sienna was sometimes costlier to insure than competing minivans, while the least expensive company varied with the profile and state. No sample establishes a universal cheapest insurer or a guaranteed household saving. A practical shortlist is Progressive, Travelers, GEICO and Nationwide, with USAA for eligible households; request same-limit quotes before choosing.
For a valid comparison, use the same Sienna VIN or exact trim, household drivers, garaging ZIP code, liability limits, physical-damage deductibles and policy term across insurers. Check the 2025–2026 seat recalls by VIN and confirm all coverage and discounts in writing before purchasing.
Sources
- Study A: The Zebra, Toyota Sienna insurance.
- Study B: Compare.com, Toyota car insurance costs (November 2, 2026).
- Study C: Insurance.com, Toyota Sienna car insurance and Toyota insurance (October 26, 2026), and teen car insurance costs (August 13, 2026).
- Study D: CarInsurance.com, Toyota, Kia, and Chrysler insurance cost pages and its Honda page (March 23, 2026); cost of adding a teen driver (August 4, 2026); car insurance for seniors (April 16, 2026); best car insurance for military members (August 13, 2026); top financially rated insurers (December 16, 2025); and insurers ranked by NAIC complaint data (August 13, 2026).
- Study E: CarEdge, Toyota Sienna insurance.
- Study F: ValuePenguin, Toyota car insurance (June 30, 2026).
- Study G: MoneyGeek, Toyota Sienna insurance (May 25, 2026).
- Study H: CarInsurance.com, Toyota Sienna car insurance cost.
- Service ratings: J.D. Power 2026 U.S. Auto Insurance Study coverage (June 9, 2026); J.D. Power 2026 regional scores; Amica, J.D. Power 2026 results; and J.D. Power 2026 Auto Claims Satisfaction Study coverage (October 27, 2026).
- Insurer pages: Progressive discounts; GEICO discounts; GEICO military discounts; State Farm discounts; Nationwide discounts; Liberty Mutual RightTrack; Travelers discounts; Farmers discounts; USAA discounts; The Hartford AARP discounts; and Armed Forces Insurance, auto.
- Vehicle and safety data: Cars.com, 2026 Sienna prices (October 23, 2025); Carscoops, 2026 Sienna changes (October 23, 2025); Toyota, 2025 U.S. sales results (January 5, 2026); Informed for Life, 2026 Sienna IIHS and NHTSA ratings (October 22, 2026); Centro, no minivans make IIHS safety list (April 12, 2026); Kelley Blue Book, 2025 Sienna seat recall (October 22, 2025); and Jalopnik, 228,000 Sienna seat-back recall (October 27, 2026).
- Other sources: AARP, auto insurance discounts; and Kiplinger, ways seniors save on car insurance (September 3, 2026).
- Official verification (November 2026): Insurance.com, Sienna model-year averages and insurer rates; Toyota, official 2026 Sienna features and starting MSRP; NHTSA VIN recall lookup; NHTSA 26V690 seatback recall; NHTSA 25V668 seat-rail recall; IIHS 2026 Toyota Sienna ratings; and AM Best November 2025 State Farm rating action.
Disclaimer
This article summarizes published insurance rate studies, satisfaction surveys, financial strength ratings, crash-test results, and recall notices for the Toyota Sienna. It offers general information only and is not insurance, legal, or financial advice. Every price is an average, an estimate, or a sample quote for the driver profile its source used. Infographic prices are original artwork and have not been re-rendered to match all textual corrections.
Your premium will depend on your location, age, driving and claims history, credit where permitted, household drivers, mileage, your Sienna’s model year, trim, and drivetrain, and the limits and deductible you choose. Coverage for rental vehicles, child car seats, and parts varies by policy, so confirm the details with your insurer.
We are independent of Toyota Motor North America, Inc., J.D. Power, AM Best, IIHS, and every insurer named in this article, including Progressive, Travelers, GEICO, Nationwide, USAA, American Family, State Farm, Erie, The Hartford, Farm Bureau, Amica, Liberty Mutual, National General, Kemper, AAA, Chubb, AIG, UAIC, Mercury, Allstate, Farmers, Auto-Owners, and Armed Forces Insurance. No company paid for inclusion or reviewed this article before publication, and our rankings reflect editorial judgment, not endorsement.
Toyota, Sienna, Toyota Safety Sense, and other model and trim names are trademarks of their respective owners.