
The Best and Cheapest Mobile Home Insurance in Texas
Finding the best and cheapest mobile home insurance in Texas can save you hundreds of dollars a year, because prices between companies differ by more than $1,800 for similar homes. Texas has about 776,232 mobile and manufactured homes, the second most of any state, and they face hail, tornadoes, floods, and Gulf Coast hurricanes.
This guide uses 2026 quote data and official state sources to rank the 10 cheapest mobile home insurance companies in Texas and name the overall cheapest. It also picks the best options for seniors, bundling with auto, and coastal homes, and explains Texas Windstorm Insurance Association coverage, the Texas FAIR Plan, Wind Zone II counties, hail and flood risk, the homestead exemption, and the discounts that can lower your bill.
KEY TAKEAWAYS
- Foremost is the overall cheapest mobile home insurer in Texas, at $1,680 a year in Study A, about 30% below the $2,408 Texas average for mobile homes (our calculation).
- Assurant is a close second at $1,741, and Foremost is also the best pick for seniors, with a discount from age 50.
- Coastal owners may need separate wind and hail coverage from TWIA, which insures manufactured homes up to $119,000 in 2026 and has frozen its rates for 2026 and 2027.
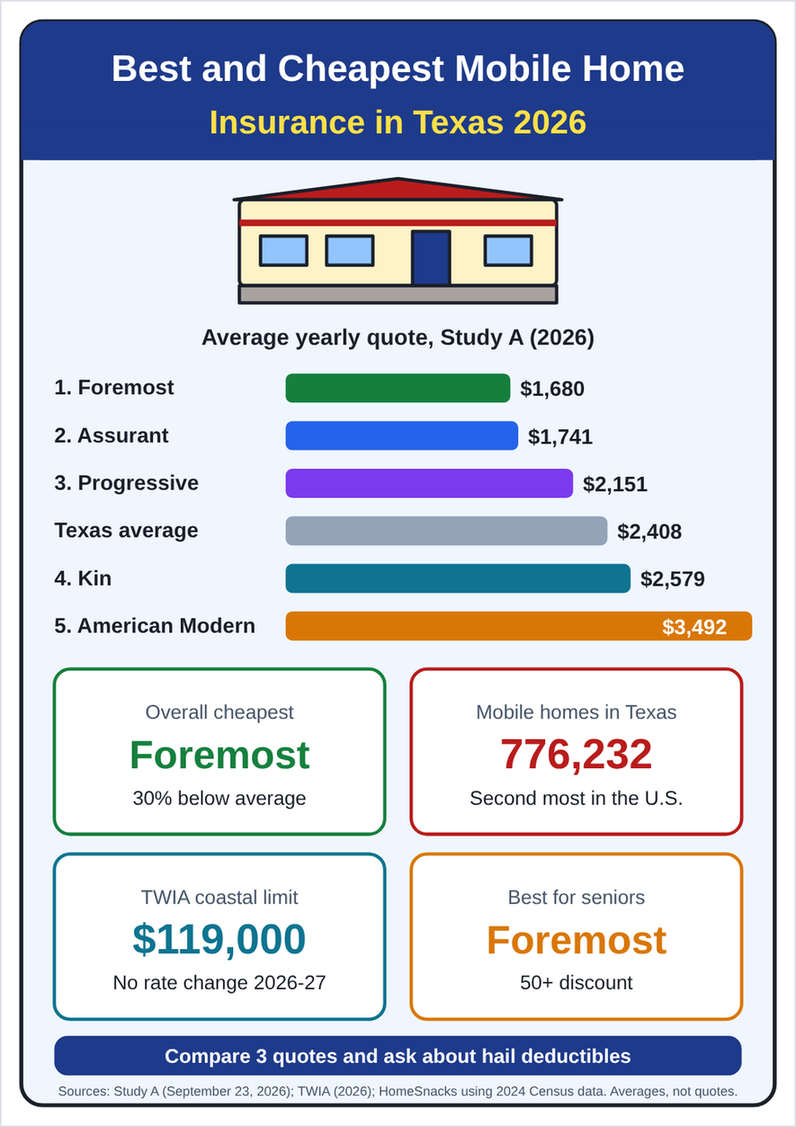
Texas mobile home insurance at a glance. Company prices are Study A's 2026 average quotes; the Texas average is Study A's figure. Averages, not quotes.
How much mobile home insurance costs in Texas
Texas does not publish a separate average premium for mobile homes, so the best current figure comes from Study A, a 2026 analysis of online quotes. It found an average of $2,408 a year, or about $201 a month, for typical manufactured homes built between 2012 and 2016, using quotes collected August 27, 2026, in El Paso, Lubbock, and Travis counties.
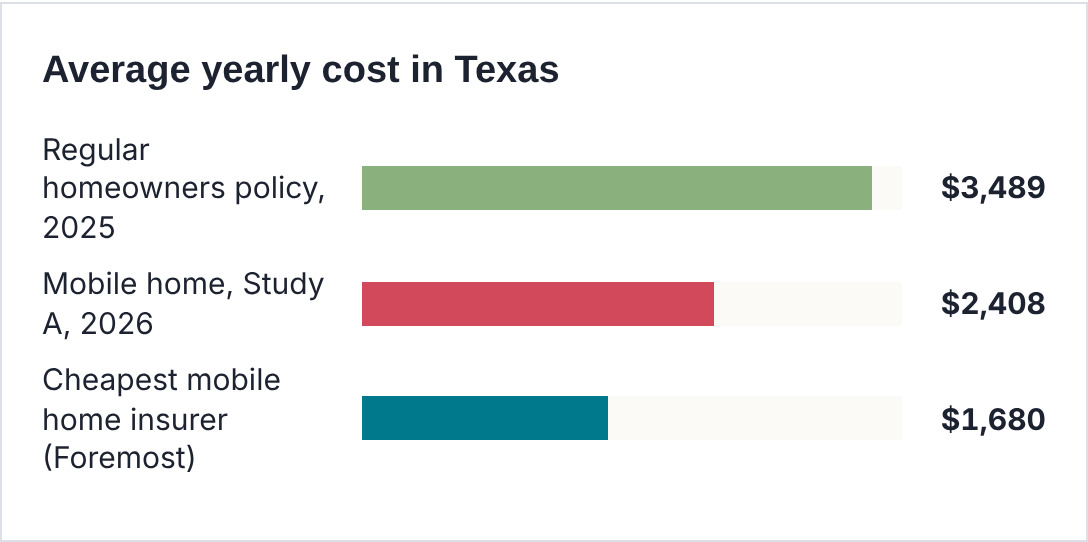
Texas Department of Insurance (2025 preliminary average for homeowners); Study A: Texas mobile home quote study updated September 23, 2026. Averages, not quotes.
A Texas mobile home policy costs about 31% less than the average regular homeowners policy, which the Texas Department of Insurance put at $3,489 in 2025 (our calculation). Foremost’s average quote was $728 below the Study A average for mobile homes.
Texas mobile home insurance is expensive compared with the rest of the country. Foremost, one of the largest mobile home insurers, puts its national average at about $1,267 a year, and American Modern estimates typical mobile home premiums at $800 to $2,000. Hail, wind, and flooding are the main reasons Texas costs more.
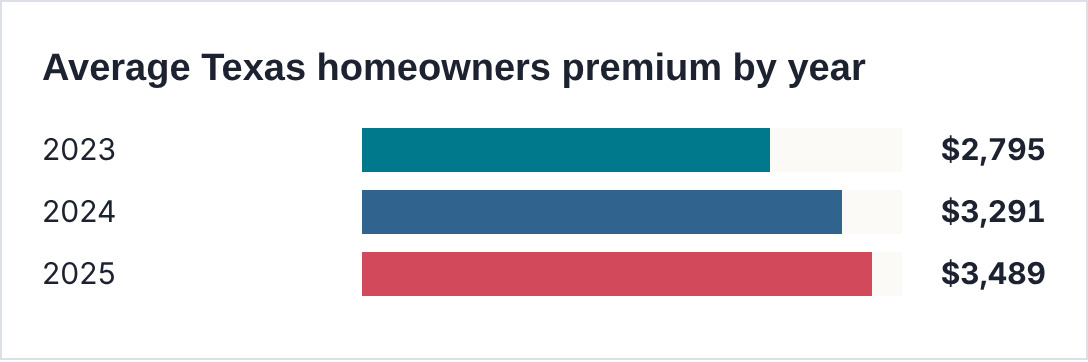
Texas Department of Insurance homeowners market overview; 2025 figure is preliminary. Regular homeowners policies, not mobile homes.
Home insurance prices in Texas rose fast in 2023 and 2024, with average rate increases of 21.1% and 18.7%, before slowing to 4.3% in 2025. The trend has now reversed. Homeowners rate filings averaged a 4.3% decrease over the 90 days before the Texas Department of Insurance's October 8, 2026, update, which means it is a good time to shop.
Texas mobile homes by the numbers
Texas has about 776,232 mobile and manufactured homes, making up 6.2% of the state's housing, according to 2024 Census data. Only Florida has more. Texas also led the country in new manufactured home shipments in 2025, with 17,458 homes, about 17% of the national total.
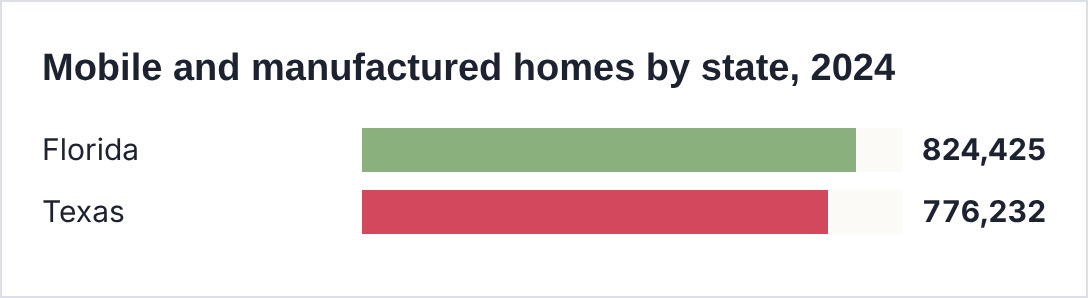
Census American Community Survey 2024, as reported July 18, 2026.
In Texas, a manufactured home's ownership is shown on a Statement of Ownership from the Texas Department of Housing and Community Affairs, which replaced titles in June 2003. A new owner must file it within 60 days of a sale for $55. Homes are personal property unless the owner elects to make them real property, which matters for taxes, loans, and the homestead exemption.
The top 10 cheapest mobile home insurance companies in Texas
We ranked the companies with the best public price data available. Ranks 1 to 5 are ordered by Study A's average Texas quotes from 2026. Ranks 6 to 10 have no published Texas mobile home prices, so we ordered them by discounts, availability, and how they sell in Texas. Several of these companies place policies with Foremost or Assurant, which we note below.
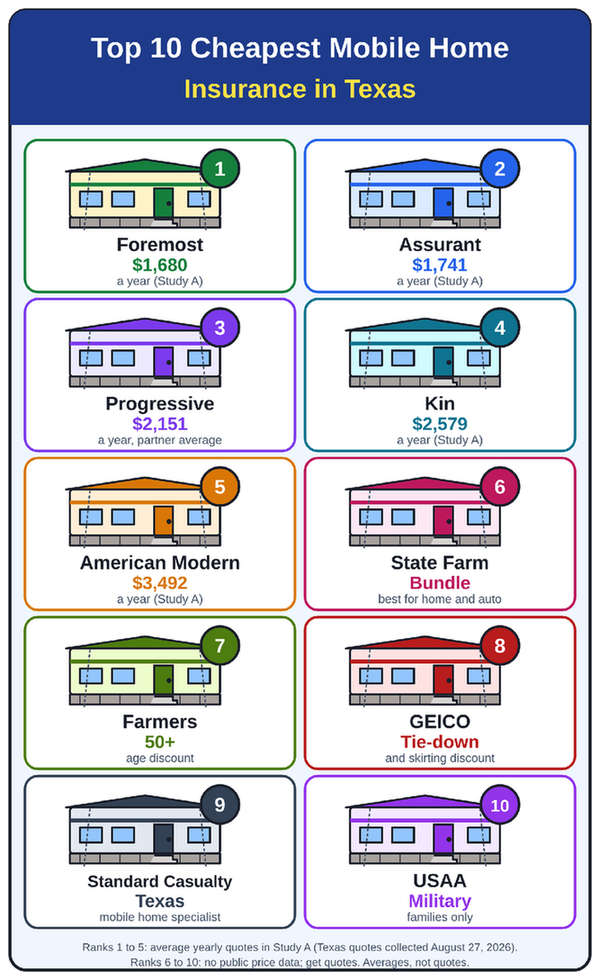
The 10 cheapest mobile home insurance companies in Texas. Prices for ranks 1 to 5 are Study A average quotes. Averages, not quotes.
Top 10 cheapest mobile home insurance companies in Texas
| Rank | Company | Average a year (Study A) | Rating | Complaint index |
|---|---|---|---|---|
| 1 | Foremost | $1,680 | AM Best A | 0.7 |
| 2 | Assurant | $1,741 | AM Best A+ | 3.1 |
| 3 | Progressive (partners) | $2,151 | Partner ratings | Not rated |
| 4 | Kin | $2,579 | Demotech A | 0.7 |
| 5 | American Modern | $3,492 | AM Best A+ | 1.4 |
| 6 | State Farm | No public price | Not checked | 1.4 |
| 7 | Farmers (Foremost policies) | No public price | AM Best A | Not rated |
| 8 | GEICO (partner policies) | No public price | Partner rating | Not rated |
| 9 | Standard Casualty | No public price | AM Best B++ | Not rated |
| 10 | USAA (partner policies) | No public price | Partner rating | Not rated |
Study A: Texas mobile home quote study updated September 23, 2026, with quotes collected August 27, 2026. NAIC complaint index for 2025, as reported by Study A; 1.0 is average and lower is better. AM Best and Demotech ratings from 2024 to 2026.
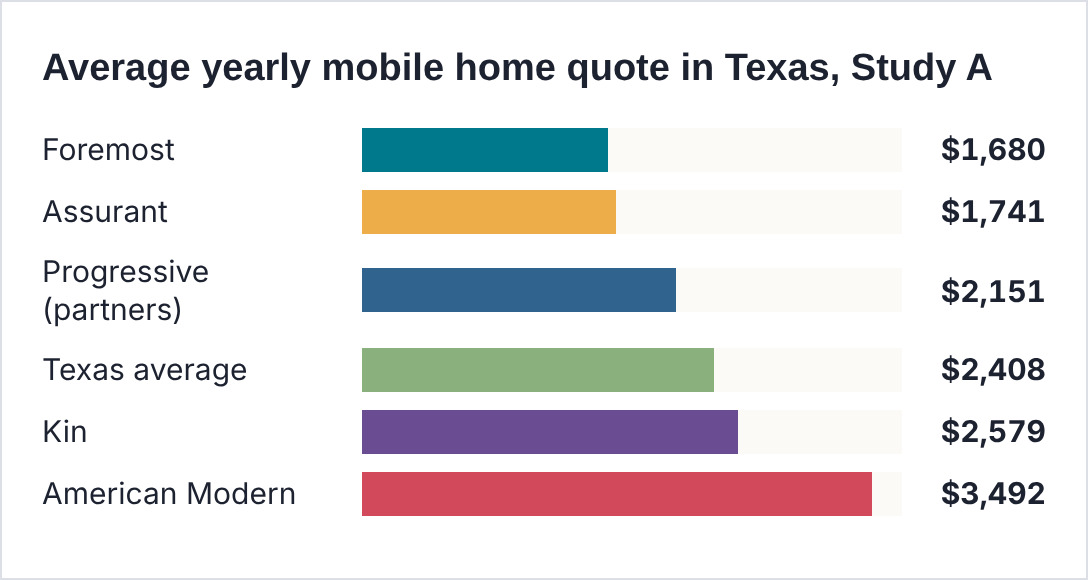
Study A: Texas mobile home quote study updated September 23, 2026, for homes built 2012 to 2016 in El Paso, Lubbock, and Travis counties. Averages, not quotes.
1. Foremost: the overall cheapest
Foremost had the lowest average quote in Study A, at $1,680 a year, or about $140 a month, 30% below the Texas average. A separate 2026 national quote study, Study B, priced a single-wide in Austin at $1,607 with Foremost, which supports its low Texas price. Its complaint index of 0.7 means fewer complaints than expected for its size, and AM Best rated it A in August 2025.
Foremost, part of the Farmers group, insures homes of any age and offers discounts for owners aged 50 and older, newer homes, homes in mobile home parks, and multiple policies. Its policies are also sold through Farmers, USAA, and Progressive, so you may see Foremost behind several brand names.
2. Assurant: a close second on price
Assurant averaged $1,741 a year in Study A, just $61 more than Foremost. AM Best rates it A+, the stronger financial grade of the two. Its weak spot is service: its complaint index of 3.1 means about three times the expected number of complaints. GEICO's mobile home quotes also lead to Assurant, so it is easy to compare.
3. Progressive: best for comparing several insurers
Progressive's $2,151 average in Study A is a blend of the insurers it places policies with, not one company's price. That makes it useful for comparison shopping, since one application can return several offers. Bundling saves an average of about 5% on Progressive auto, and when one event damages both your home and car, you pay a single deductible.
4. Kin: best for bundling discounts online
Kin averaged $2,579 a year in Study A, above the state average, but it stands out for service and bundling. Its complaint index is a low 0.7, it is rated A by Demotech, and it says bundling can cut up to 20% off your auto insurance. Kin launched its Texas house and mobile home products in March 2024 and sells online.
5. American Modern: strongest rating among the priced companies
American Modern, owned by Munich Re, carries an A+ rating from AM Best, but its Study A average of $3,492 was the highest of the five priced companies. It sells through independent agents and can be a good choice for homes that other companies decline, such as older or seasonal homes. An older American Modern sheet lists discounts of 5% for paying in full and 20% for three years without claims.
6. State Farm: best for bundling home and auto
State Farm is the largest home insurer in Texas and insures manufactured homes, though not mobile homes built before 1976. It sells only through agents, so there are no online quotes, and Study A did not publish a price. It is a strong choice for bundling because Study A named it the cheapest car insurer in Texas, and it offers discounts for newer model years, home alarms, and long-time customers.
7. Farmers: best for seniors through a local agent
Farmers sells mobile home coverage written by Foremost, so its prices should track Foremost's. Working through a local Farmers agent makes sense if you want to bundle auto and home in person. Farmers offers a discount for owners aged 50 and older, plus claims-free and protective device discounts.
8. GEICO: best for well-anchored homes
GEICO places mobile home policies with a partner insurer, and its quote links lead to Assurant. It lists discounts for tie-downs and full skirting, newer homes, a recent purchase, a loss-free history, and bundling with GEICO auto. A properly anchored, fully skirted home is safer in Texas storms and can earn a lower price.
9. Standard Casualty: a Texas specialist
Standard Casualty is a New Braunfels company owned by manufactured home builder Cavco that specializes in manufactured home insurance in Texas. AM Best rates it B++ (Good), and in 2026 it moved the company's outlook to positive. It has been non-renewing some high-risk policies, so ask an independent agent whether it will insure your home.
10. USAA: for military families
USAA does not write mobile home insurance itself, but members can get coverage through partners such as Foremost or American Modern. It is worth a call if you are eligible, especially to bundle with USAA auto insurance. Only military members, veterans, and their families can join.
PRO TIP #1
Because Farmers, GEICO, USAA, and Progressive often sell Foremost or Assurant policies, getting quotes from all of them can return the same insurer several times. Make sure at least one quote comes from a different company, such as Kin or Standard Casualty.
The overall cheapest mobile home insurance in Texas
Foremost is our pick for the overall cheapest mobile home insurance in Texas. It had the lowest average quote in Study A, at $1,680 a year, a low complaint index of 0.7, and an AM Best A rating, and a second 2026 study found a similar price in Austin. Assurant is a close second at $1,741, with a stronger financial rating but far more complaints.
Keep in mind that Study A gathered quotes in El Paso, Lubbock, and Austin, not on the coast. Homes near the Gulf usually cost more to insure, and many need separate wind and hail coverage from TWIA. Use these rankings to decide where to start, then compare your own quotes.
The best mobile home insurance in Texas by need
Best mobile home insurance in Texas, by need
| Need | Best pick | Why |
|---|---|---|
| Overall cheapest | Foremost | $1,680 in Study A; complaint index 0.7 |
| Runner-up on price | Assurant | $1,741 in Study A; AM Best A+ |
| Seniors | Foremost | 50+ discount; insures homes of any age |
| Bundling with auto | State Farm | Cheapest Texas car insurance in Study A |
| Online bundling | Kin | Up to 20% off auto |
| Comparing several insurers | Progressive | One application, several offers |
| Older or hard-to-insure homes | American Modern | A+ rating; accepts many home types |
| Texas specialist | Standard Casualty | Focuses on Texas manufactured homes |
| Military families | USAA | Partner policies for members |
| Coastal wind and hail | TWIA | Up to $119,000 for manufactured homes |
| Last resort | Texas FAIR Plan | For homes declined by two insurers |
Our assessment, based on Study A and company and state information.
Cheapest mobile home insurance for seniors in Texas
Many Texas mobile home owners are retirees on fixed incomes, and some of the best discounts are aimed at them. No study publishes Texas prices by age, but Foremost combines the lowest average price in Study A with a discount from age 50, which makes it our pick for seniors.
Mobile home insurance options for Texas seniors
| Company | Senior benefit | Other savings |
|---|---|---|
| Foremost | Discount at age 50+ | Lowest average quote; park and newer-home discounts |
| Farmers | Discount at age 50+ | Foremost policies through a local agent |
| Allstate | Discount for retirees 55+ | Ask whether it writes mobile homes in your area |
| Assurant | No senior discount found | Second-lowest average quote |
| State Farm | No senior discount found | Strong bundle savings with auto |
Company websites and Study A (2026). Discount amounts are not published.
Seniors who own the land under their home have another way to save. Under Texas Tax Code section 11.432, a manufactured home owner who owns the land can claim the homestead exemption whether the home is personal or real property. The exemption is $140,000, and owners 65 and older get an extra $60,000, retroactive to 2025. Lower property taxes can free up money for insurance.
- Ask every insurer for an age 50+ or retiree discount by name.
- Ask whether your mobile home park qualifies for a park discount.
- Choose a deductible you could pay from savings after a hailstorm.
- Review your personal property limit, which may be higher than you need.
- Set up automatic payments so a missed bill does not cancel your policy.
PRO TIP #2
If you are 65 or older and own the land under your mobile home, file for the homestead exemption with your county appraisal district. Combined with a 50+ insurance discount, it can lower your total housing costs by hundreds of dollars a year.
Texas mobile home insurance by region
Texas is so large that the biggest risk to your home depends on where you live. Your region should shape the coverage you buy as much as the company you choose.
Main risks and coverage needs by Texas region
| Region | Main risk | What to check |
|---|---|---|
| Gulf Coast | Hurricanes and storm surge | TWIA wind and hail coverage, flood insurance, Wind Zone II rules |
| Hill Country | Flash floods | Flood insurance, even far from rivers |
| North Texas and the Panhandle | Hail and tornadoes | Wind and hail deductible, roof credits, tie-downs |
| Houston area | Hurricanes and flooding | TWIA east of Highway 146, flood coverage |
| West Texas | Wind and hail | Wind and hail deductible, skirting and tie-downs |
Our assessment is based on TWIA, Texas Department of Insurance, and FEMA information.
Study A's prices came from El Paso, Lubbock, and Austin, so they reflect inland Texas. If you live on the coast, expect to pay more in total once you add TWIA and flood coverage, and get quotes for all three policies before you decide.
Policies with and without wind and hail coverage
Along the coast, many private policies exclude wind and hail, and owners buy that coverage separately from TWIA. Inland, most mobile home policies include wind and hail but apply a separate deductible, often a percentage of the dwelling limit.
- Full policy with wind and hail: the simplest choice inland, with one company handling every claim.
- Policy without wind and hail plus TWIA: the usual setup on the coast, with two companies and two deductibles.
- Policy without wind and hail and no TWIA policy: the cheapest option, but a hurricane or hailstorm would not be covered.
If you have two policies, keep both sets of contact details handy. After a hurricane, you may need to file a wind claim with TWIA and a flood claim with your flood insurer for the same storm.
TWIA: wind and hail coverage on the Texas coast
Many insurers exclude wind and hail damage on the Texas coast. The Texas Windstorm Insurance Association, or TWIA, fills that gap. It sells wind and hail coverage in the 14 coastal counties and in part of Harris County east of Highway 146, and it had 288,676 policies covering about $128.3 billion in property at June 30, 2026.
TWIA rules for manufactured homes
| Rule | Details |
|---|---|
| Where it sells | 14 coastal counties and part of Harris County east of Highway 146 |
| Manufactured home limit | $119,000 for 2026, up from $116,700 |
| Tie-down proof | A tie-down form (MH-96 or Form T) is required |
| Building certificate | A WPI-8 certificate of compliance is required |
| Flood requirement | Only for homes in V flood zones built or changed after September 2009 |
| Rates | No change for 2026 or 2027; last increase was 5% in 2022 |
| Funding | A 2025 law, HB 3689, replaced bond funding with state financing repaid by a statewide surcharge |
TWIA (2026), including its Q2 2026 fact book and board decisions of August 4, 2026; Texas Department of Insurance Order 2025-9540 (October 6, 2025); HB 3689 analysis.
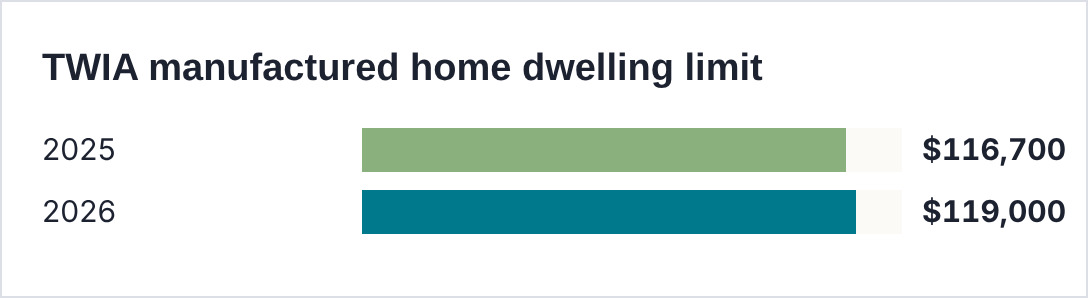
Texas Department of Insurance Order 2025-9540 (October 6, 2025).
If you live on the coast, you will usually need two policies: a mobile home policy that excludes wind and hail, and a TWIA policy for wind and hail. Ask your agent to quote both together, and make sure your tie-down paperwork and WPI-8 certificate are in order before you apply.
The Texas FAIR Plan for mobile homes
If private insurers will not cover your home, the Texas FAIR Plan Association is the insurer of last resort. You need two declinations from private insurers to apply, and mobile homes must meet extra rules.
Texas FAIR Plan rules for mobile homes
| Rule | Details |
|---|---|
| Eligibility | Two declinations from private insurers |
| Setup | Wheels removed and the home tied down |
| Minimum size | At least 8 by 32 feet |
| Tie-down form | Form T must reach the FAIR Plan within 30 days |
| Valuation | Actual cash value only; no replacement cost for mobile homes |
| Wind and hail deductible | At least 2% on homeowners policies from July 1, 2026 |
Texas FAIR Plan Association coverage and eligibility pages and underwriting manual (2023 to 2026).
Because the FAIR Plan pays only actual cash value on mobile homes, an older home could be worth far less than the cost to replace it. Treat it as a temporary safety net and keep shopping private insurers each year.
Wind Zone II counties in Texas
Fifteen Texas counties are in HUD Wind Zone II, where manufactured homes must be built for stronger winds: Aransas, Brazoria, Calhoun, Cameron, Chambers, Galveston, Jefferson, Kenedy, Kleberg, Matagorda, Nueces, Orange, Refugio, San Patricio, and Willacy. Under Texas Occupations Code section 1201.256, homes built on or after September 1, 1997, must meet Wind Zone II standards to be installed in these counties.
Orange County is in Wind Zone II but is not a TWIA county, so owners there should ask private insurers about wind coverage. Homes in these counties cost more to insure, so properly installed tie-downs and a copy of your installation report can help your quote.
Hail, storms, and floods in Texas
Hail is the biggest driver of home insurance losses in Texas. Hail claims cost $4.93 billion in 2024, according to the Texas Department of Insurance, and more than 235,000 Texas homes were hit by hail two inches or larger in 2025. State Farm paid $1.4 billion in Texas hail claims in 2025, more than in any other state.
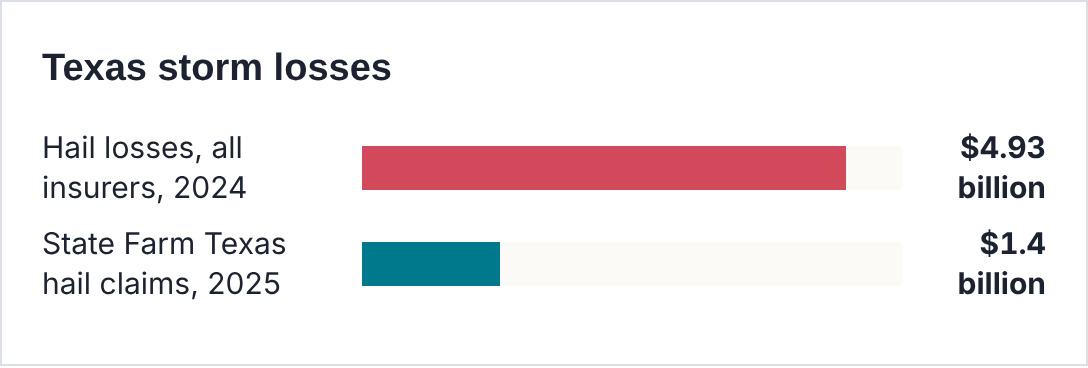
Texas Department of Insurance (2024 losses); State Farm newsroom (2025 hail claims).
Floods are a growing danger. The July 2025 Hill Country floods killed at least 138 people, and only about 2% of Kerr County homeowners had flood insurance. Another Kerr County flood in July 2026 destroyed or heavily damaged 135 homes. In a 2026 survey of flood-hit households, 10.6% lived in manufactured homes, and only 52 of 513 insured households had flood coverage.
Hurricane Beryl, which made landfall on July 8, 2024, caused an estimated $2.5 billion to $4.5 billion in insured losses in the U.S. Coastal owners should review both TWIA and flood coverage before every hurricane season.
Hail, roofs, and your premium
Because hail causes more losses than any other peril in Texas, your roof matters. The Texas Department of Insurance says a Class 4 impact-resistant roof earns the biggest roofing credit, though each insurer sets its own amount. In September 2026, the department urged insurers to offer real discounts for storm-resistant upgrades.
Mobile homes often have metal or shingle roofs, and many insurers pay roof claims on an actual cash value basis as roofs age. Before you buy, ask how the company pays for roof damage, whether your roof qualifies for a credit, and how your wind and hail deductible works. A new or upgraded roof can lower both your premium and the cost of your next hail claim.
Insuring older and pre-1976 mobile homes in Texas
Homes built before June 15, 1976, when the federal HUD code took effect, are often harder to insure. State Farm, for example, insures manufactured homes but not mobile homes built before 1976. Foremost insures homes of any age, and American Modern accepts many home types other companies decline.
If your home is older, keep records of updates to the roof, wiring, plumbing, and heating, and make sure it is properly tied down with an installation report on file. If two private insurers decline you, the Texas FAIR Plan can cover the home, but only at actual cash value.
Flood insurance for Texas mobile homes
Standard mobile home policies and TWIA policies do not cover flooding. The National Flood Insurance Program covers manufactured homes anchored to a permanent foundation, with up to $250,000 for the home and $100,000 for contents. There is usually a 30-day wait before coverage starts. Texas had 561,842 NFIP policies on August 31, 2026.
PRO TIP #3
Do not assume you are safe from flooding because you are far from the coast. The deadly 2025 and 2026 floods hit the Hill Country, hundreds of miles inland. Buy flood coverage at least 30 days before storm season.
Texas laws every mobile home owner should know
- Texas law does not require home insurance, but lenders do, according to the Texas Department of Insurance.
- Insurers can use credit information in pricing, but they cannot deny or cancel a policy based on credit alone, and they must make exceptions for major life events.
- Your Statement of Ownership, filed with the state housing department, is your proof of ownership.
- Installers must file an installation report, called Form T, within seven days of installation.
- Homes are personal property unless you elect real property, but you can still claim the homestead exemption if you own the land.
- The Texas Department of Insurance has urged insurers to offer real discounts for storm-resistant upgrades, such as Class 4 impact-resistant roofs.
What Texas mobile home insurance covers
Main coverage parts of a Texas mobile home policy
| Coverage | What it pays for |
|---|---|
| Dwelling | Repairs or replacement of the home |
| Other structures | Carports, decks, sheds, skirting, and fences |
| Personal property | Furniture, clothes, and belongings |
| Loss of use | Hotel and living costs after a covered loss |
| Personal liability | Injuries or damage you cause to others |
| Wind and hail | Storm damage, often with a separate percentage deductible |
| Optional add-ons | Replacement cost, trip coverage, and flood |
Company policy descriptions; coverage varies by insurer.
Two choices shape every Texas policy. The first is actual cash value versus replacement cost. Actual cash value subtracts depreciation, so you may get far less than the cost of a similar new home after a total loss. The second is the wind and hail deductible, which is often a percentage of your dwelling limit rather than a flat amount.
Wind and hail deductible on a $100,000 home
| Deductible | You pay before coverage starts |
|---|---|
| 1% | $1,000 |
| 2% | $2,000 |
| 5% | $5,000 |
Our calculation for an example $100,000 dwelling limit. Available options vary by insurer; the Texas FAIR Plan's minimum is 2%.
What sets your mobile home insurance price in Texas
Main factors in your Texas mobile home premium
| Factor | Why it matters |
|---|---|
| Location | Coastal and hail-prone areas cost more |
| Wind zone | Wind Zone II counties need stronger homes and often TWIA coverage |
| Year built | Newer homes earn discounts; pre-1976 homes are harder to insure |
| Tie-downs and skirting | Anchored, skirted homes earn credits at some insurers |
| Roof | Impact-resistant roofs can earn credits, depending on the insurer |
| Deductibles | Higher wind and hail deductibles lower the premium |
| Credit | Insurers can use credit, with limits |
| Claims history | Recent claims raise prices; claims-free years lower them |
| Age of the owner | Discounts from age 50 or 55 at some insurers |
Texas Department of Insurance; company discount lists. Factor weights vary by insurer.
Mobile home insurance vs. homeowners insurance in Texas
How Texas mobile home and homeowners policies compare
| Feature | Mobile home policy | Homeowners policy |
|---|---|---|
| Average yearly cost | About $2,408 (Study A, 2026) | About $3,489 (2025) |
| TWIA dwelling limit | $119,000 | Higher limits for site-built homes |
| Texas FAIR Plan valuation | Actual cash value only | Replacement cost available |
| Ownership document | Statement of Ownership | Deed |
| Common extras | Skirting, tie-downs, carports | Garages, fences, pools |
Study A; Texas Department of Insurance; TWIA; Texas FAIR Plan Association.
Park homes vs. homes on private land
Where your home sits changes your coverage needs. Foremost offers a discount for homes in mobile home parks, which often have paved roads, nearby fire hydrants, and on-site managers. Read your park lease, since parks may set their own insurance rules.
Homes on land you own usually need more coverage for sheds, barns, carports, fences, and wells, and you are responsible for liability on the whole property. Rural homes may also be farther from a fire station, which can raise the price. If you own the land, ask about the homestead exemption, too.
How to check an insurer's financial strength and service
Ratings for Texas mobile home insurers
| Company | Financial rating | Complaint index (2025) |
|---|---|---|
| Foremost | AM Best A (August 2025) | 0.7 |
| Assurant | AM Best A+ (September 2025) | 3.1 |
| Kin | Demotech A | 0.7 |
| American Modern | AM Best A+ (July 2025) | 1.4 |
| State Farm | Not checked | 1.4 |
| Standard Casualty | AM Best B++, outlook positive (2026) | Not reported |
AM Best and Demotech ratings as reported in 2024 to 2026; NAIC complaint index for 2025 as reported by Study A. A complaint index of 1.0 is average, and lower is better.
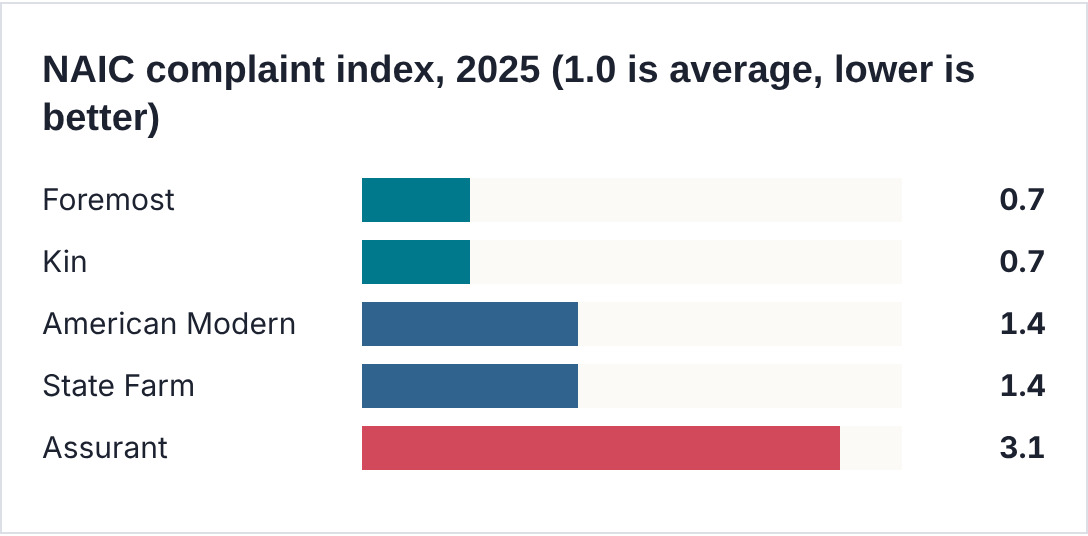
NAIC complaint index for 2025, as reported by Study A (September 23, 2026).
Foremost and Kin draw fewer complaints than expected for their size, while Assurant draws about three times as many. Since Foremost and Assurant are only $61 apart in Study A, Foremost's better service record is a strong reason to start there.
Bundling mobile home and auto insurance in Texas
Bundling can lower your total cost and make claims easier when a hailstorm damages both your home and your car.
Bundling options for Texas mobile home owners
| Company | Bundle savings | Notes |
|---|---|---|
| Kin | Up to 20% off auto | Sells online |
| Progressive | About 5% on auto on average | One deductible when one event damages both |
| American Modern | 5% for multiple policies; 5% for auto with your agent | From a 2018 company sheet |
| State Farm | Not published for mobile homes | Study A named it the cheapest Texas car insurer |
| Foremost and Farmers | Multi-policy discount | Amount not published |
| GEICO | Multi-policy discount with GEICO auto | Amount not published |
Company websites (2018 to 2026); Study A.
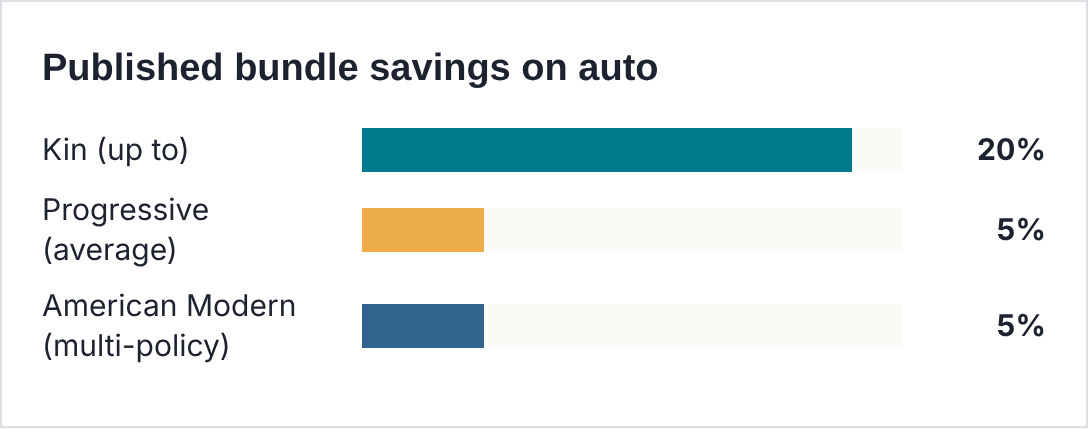
Company websites; American Modern figure from a 2018 sheet. Savings apply to the auto policy unless noted.
For many Texans, the cheapest combination is Foremost for the mobile home and State Farm for the car, even without a bundle discount. Compare that total against a single-company bundle from Kin, Progressive, or State Farm before you decide.
Mobile home insurance discounts in Texas
Discounts to ask for in Texas
| Discount | Who offers it |
|---|---|
| Age 50+ or retiree | Foremost, Farmers (50+), Allstate (55+ retired) |
| Newer home | Foremost, GEICO, State Farm |
| Mobile home park | Foremost |
| Tie-downs and full skirting | GEICO |
| Alarms and protective devices | State Farm, Farmers |
| Claims-free | GEICO, Farmers, American Modern |
| Paid in full | American Modern |
| Multi-policy | Kin, Progressive, Foremost, GEICO, American Modern |
| Long-time customer | State Farm |
| Impact-resistant roof | Varies by insurer; Class 4 roofs earn the biggest credit |
Company websites; Texas Department of Insurance roofing discount guidance. Discount amounts vary.
Tips to save money on mobile home insurance in Texas
- Get at least three quotes, starting with Foremost, Assurant, and Kin.
- Make sure your quotes come from different insurers, not the same company under several brands.
- Ask for every discount, including age, park, newer home, and claims-free.
- Install tie-downs and full skirting, and keep your installation paperwork.
- Choose a 1% or 2% wind and hail deductible only if you could pay it after a storm.
- Ask whether a Class 4 impact-resistant roof would lower your premium.
- Bundle with auto, or pair Foremost with a cheap car insurer.
- On the coast, get quotes for TWIA wind and hail coverage plus a policy that excludes wind.
- Buy flood insurance early to avoid the 30-day wait.
- Claim the homestead exemption if you own the land under your home.
- Shop again every year, since Texas rates are now falling.
How to compare Texas mobile home insurance quotes
- Use the same dwelling limit, liability limit, and deductibles for every quote.
- Check whether each quote pays actual cash value or replacement cost.
- Confirm whether wind and hail are included or excluded.
- Ask how the wind and hail deductible is calculated.
- Check each insurer's financial rating and complaint index.
- Add the cost of TWIA and flood coverage when you compare totals.
The Texas Department of Insurance has consumer guides on getting insurance for a manufactured home and a helpline for complaints, and HelpInsure.com, its consumer site, can help you compare companies.
Questions to ask before you buy
A few questions can save you from an expensive surprise after a storm. Ask each agent or company these before you sign.
- Does the policy pay replacement cost or actual cash value on the home and the roof?
- Is wind and hail included, and how is the wind and hail deductible calculated?
- Are carports, decks, skirting, and sheds covered, and up to what limit?
- Does the policy cover the home while it is being moved?
- Which discounts are already applied, and which could I still add?
- Will the price change if I install a Class 4 roof or new tie-downs?
- How do I file a claim, and is help available around the clock?
Write down the answers for each company. When you compare quotes side by side, the cheapest good policy is usually easy to spot, and you will know exactly what you are paying for.
What to do after a storm
- Get to safety, then call your insurer or agent as soon as you can.
- Take photos and video of all damage before cleaning up.
- Make temporary repairs, such as tarps, and keep the receipts.
- Ask about loss-of-use coverage for hotel and living costs.
- File wind and hail claims with TWIA if it insures your home, and flood claims with your flood insurer.
- Get your adjuster's name and contact details, and keep notes of every call.
- If you disagree with the settlement, contact the Texas Department of Insurance helpline.
Texas mobile home insurance at a glance
This illustrated summary pulls together the main points of this guide.
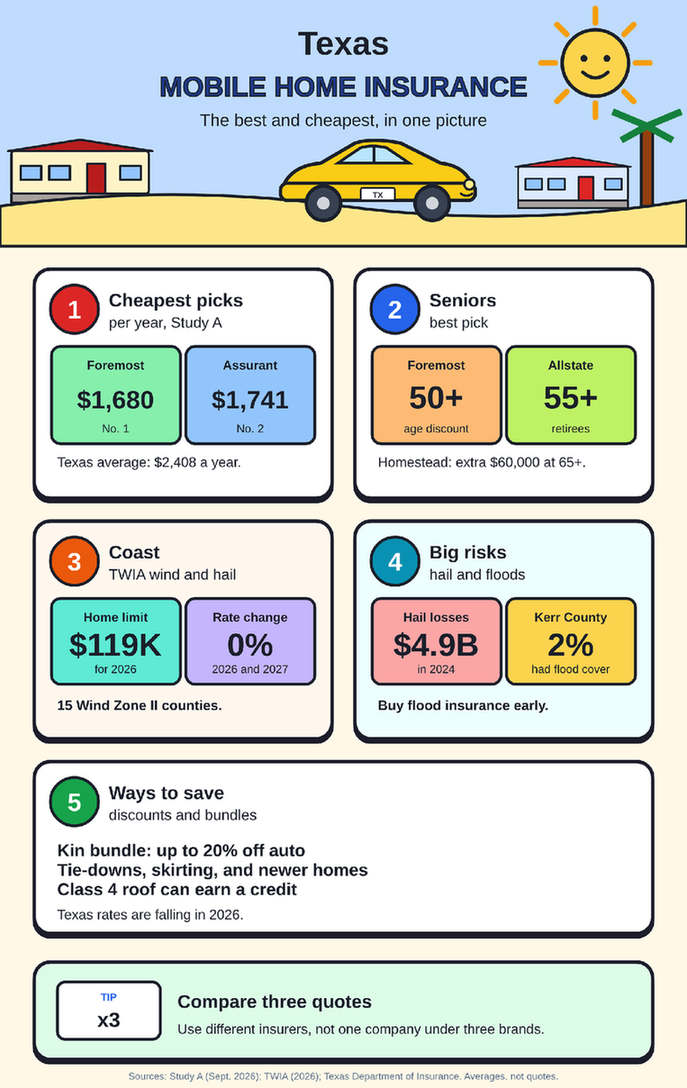
The best and cheapest mobile home insurance in Texas at a glance. Sources: Study A; TWIA; Texas Department of Insurance.
Frequently asked questions about Texas Mobile Home Insurance
How much is mobile home insurance in Texas?
Study A found an average of $2,408 a year, or about $201 a month, for typical manufactured homes built from 2012 to 2016, based on 2026 quotes. Coastal homes and homes in hail-prone areas can cost more. A regular Texas homeowners policy averaged $3,489 in 2025.
Who has the cheapest mobile home insurance in Texas?
Foremost had the lowest average quote in Study A, at $1,680 a year, followed by Assurant at $1,741 and Progressive's partners at $2,151. Prices vary by location and home, so compare at least three quotes from different insurers.
What is the best mobile home insurance for seniors in Texas?
Foremost is our pick for seniors because it has the lowest average quote and offers a discount from age 50. Farmers also offers a 50+ discount, and Allstate offers one to retirees 55 and older. Ask every insurer about age discounts.
Does TWIA cover mobile homes?
Yes. TWIA sells wind and hail coverage for manufactured homes in the 14 coastal counties and part of Harris County, with a dwelling limit of $119,000 for 2026. You need a tie-down form and a WPI-8 certificate. Its rates will not change in 2026 or 2027.
Does the Texas FAIR Plan insure mobile homes?
Yes, if two private insurers have declined you. The home must have its wheels removed, be tied down, and measure at least 8 by 32 feet. The FAIR Plan pays only actual cash value on mobile homes, so keep shopping private insurers.
Is mobile home insurance required in Texas?
Texas law does not require it, but your lender will if you have a loan, and some parks have their own rules. Because hail, wind, and floods are common, insurance is strongly recommended even if your home is paid off.
Can I bundle mobile home and auto insurance in Texas?
Yes. Kin says bundling can save up to 20% on auto, and Progressive averages about 5% on auto, with one deductible when one event damages both. State Farm is a strong bundling choice because it has some of the cheapest car insurance in Texas.
Can I insure an older mobile home in Texas?
Yes, but fewer companies will. Foremost insures homes of any age, and American Modern accepts many older homes. State Farm does not insure mobile homes built before 1976. If two insurers decline you, the Texas FAIR Plan covers eligible homes at actual cash value.
Do I need flood insurance for a mobile home in Texas?
Standard policies do not cover floods, so you need a separate flood policy. The NFIP covers anchored manufactured homes up to $250,000 for the home and $100,000 for contents, usually after a 30-day wait. The 2025 and 2026 Hill Country floods showed that inland homes are at risk, too.
The final word on the best and cheapest mobile home insurance in Texas
The best and cheapest mobile home insurance in Texas starts with Foremost, which had the lowest average quote in Study A, at $1,680 a year, along with a low complaint index and a discount for owners 50 and older. Assurant is a close second on price, Kin and State Farm are strong for bundling, and TWIA and the Texas FAIR Plan are there for coastal and hard-to-insure homes.
To pay the least, compare at least three quotes from different insurers, claim every discount, choose wind and hail deductibles you can afford, and add flood coverage before you need it. Texas rates are falling in 2026, so this is a good time to shop and lock in a better price for your home.
Sources
- Study A: LendingTree, mobile home insurance in Texas (September 23, 2026), and best mobile home insurance companies, methodology (September 15, 2026).
- Study B: ValuePenguin, mobile home insurance (July 6, 2026).
- Texas Department of Insurance, homeowners insurance market overview, rate update (October 8, 2026), how to get insurance for a manufactured home, credit and insurance, roofing discounts, and top 40 homeowners insurers.
- Texas Department of Insurance, property and casualty annual report 2025, and Order 2025-9540, TWIA limits (October 6, 2025).
- TWIA: eligibility, flood requirement, 2026 rates, 2027 rates, and Q2 2026 fact book.
- Texas Legislature, HB 3689 bill analysis (2025).
- Texas FAIR Plan Association: coverage and eligibility, underwriting manual (April 2023), and deductible changes (July 1, 2026).
- Texas Department of Housing and Community Affairs, Statement of Ownership FAQ, and Texas Occupations Code section 1201.256.
- Texas Tax Code section 11.432 and Texas homestead exemptions guide (December 2025).
- HomeSnacks, mobile homes by state (July 18, 2026), using 2024 Census data, and Texas Real Estate Research Center, housing trends.
- State Farm, 2025 hail claims, and Cotality, 2026 severe convective storm report.
- Claims Journal, Hurricane Beryl losses (July 16, 2024); Bloomberg Law, Texas flood insurance; KWTX, Kerr County flood (July 20, 2026); and Kerr County Lead, flood survivor survey.
- FEMA, manufactured homes flood coverage (August 2025).
- Kin, Texas mobile home insurance; NerdWallet, mobile home insurance, citing Foremost and American Modern.
Disclaimer
This website provides independent reviews and comparisons. It is not affiliated with, endorsed by, sponsored by, or connected to Foremost, Farmers, Assurant, Progressive, Kin, American Modern, State Farm, GEICO, Standard Casualty, Cavco, USAA, Allstate, the Texas Windstorm Insurance Association, the Texas FAIR Plan Association, or any of their affiliates.
All company names, brand names, trademarks, and logos are the property of their respective owners and are used here only to identify the companies being reviewed. Their use does not imply any affiliation or endorsement.
The information on this page is provided for general informational and educational purposes only. It is not insurance, legal, tax, or financial advice, and it is not an offer, quote, or solicitation to buy or sell insurance. We are not an insurance company, insurance agency, or licensed insurance producer, and we cannot bind coverage, change a policy, or handle claims.
Prices, discounts, ratings, and company details are drawn from public sources and third-party studies that use specific home profiles, and they can change at any time. They are estimates and averages, not guarantees of what you will pay. Coverage, eligibility, and discounts vary by location, home, and owner, and are subject to each insurer's underwriting rules and policy terms.
While we make reasonable efforts to keep this guide accurate and current, we make no representations or warranties, express or implied, about its completeness, accuracy, or reliability. Opinions here are our own. Always confirm details directly with the insurer, read your policy documents, and consult the Texas Department of Insurance or a licensed professional before making a decision. Your use of this information is at your own risk, and we are not liable for any loss or damage arising from reliance on it.