
Illinois Mobile Home Insurance: Companies, Costs & Coverage
Illinois mobile home insurance should be compared by policy coverage and the individual home—not by an unsupported list of the state’s supposedly cheapest insurers. Illinois has faced exceptional severe weather in 2026: the state climatologist confirmed a preliminary record of 210 tornadoes by the beginning of September. That raises the stakes for homeowners checking wind protection, replacement-cost options, anchoring requirements, and deductibles.
This guide compares ten insurers and distribution options that may help Illinois manufactured-home owners request quotes. It separates out-of-state manufactured-home sample prices from rates for conventional Illinois houses, which are not interchangeable. It also explains tornado, hail, flood, earthquake, and mine subsidence risks; park residents’ rights; taxes and seniors’ benefits; and how to compare coverage without assuming a published average is your quote.
KEY TAKEAWAYS
- Assurant ($969), American Modern ($1,025), and Foremost ($1,607) were quoted in a three-city manufactured-home study outside Illinois—not in an Illinois-specific price ranking.
- An estimated $1,231 Illinois manufactured-home premium appears in a third-party state table without a transparent pricing profile. It is not a verified statewide average or a guaranteed quote.
- Illinois FAIR Plan eligibility materials explicitly include mobile homes at a fixed location under a limited basic DP-1 dwelling policy. Liability and theft protection are not included in that form.
- A qualifying resident owner aged 65 or older (or with a qualifying disability) can pay 80% of the Illinois Mobile Home Local Services Tax after applying to the county clerk.
Editorial warning: This original image shows prices or a numbered “cheapest” ranking not validated with comparable Illinois manufactured-home quotes. The corrected text and tables take precedence.
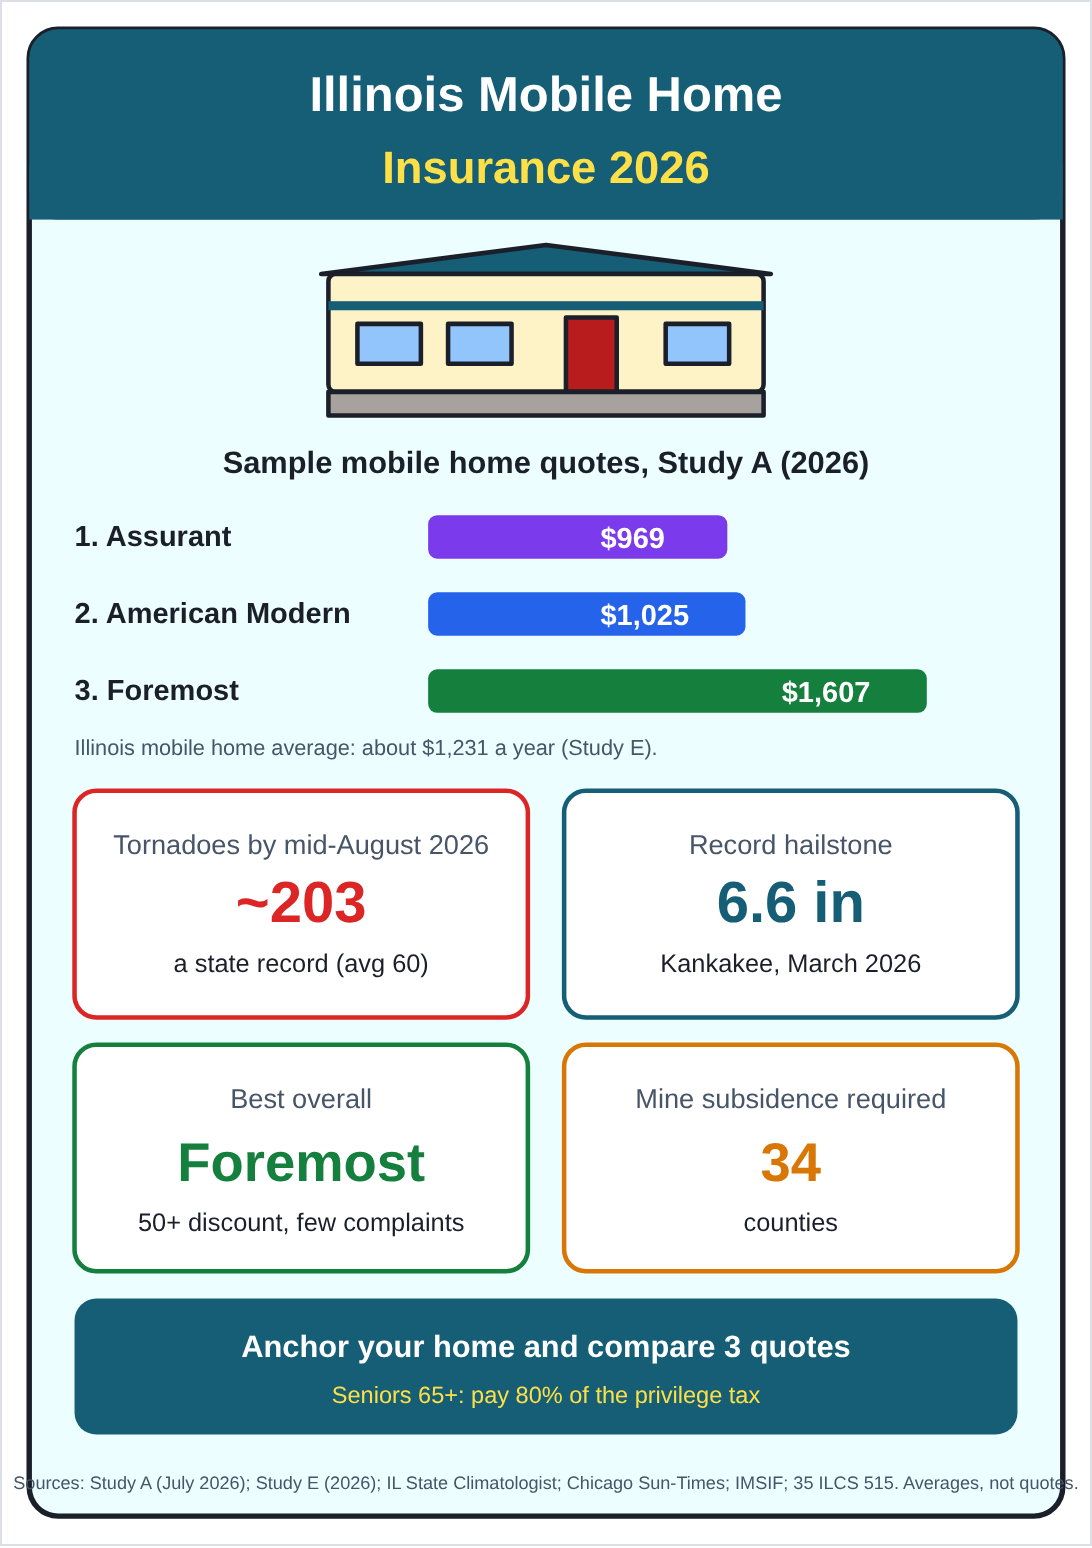
Illinois mobile home insurance at a glance. Company prices are Study A’s 2026 sample quotes, not Illinois quotes.
How much mobile home insurance costs in Illinois
Important price limitation: the sources cited here do not provide a head-to-head study quoting the same manufactured home in Illinois with ten insurers. Study A (ValuePenguin, July 2026) priced a 2016 single-wide in a park using sample locations in Austin, Indianapolis and Mesa. Its listed Assurant, American Modern and Foremost rates therefore cannot identify Illinois’s cheapest insurer. Study E displays an Illinois figure near $1,231 a year, but does not provide enough information about the insured home, coverage limits, sample size or underwriting assumptions to validate it as an Illinois average.
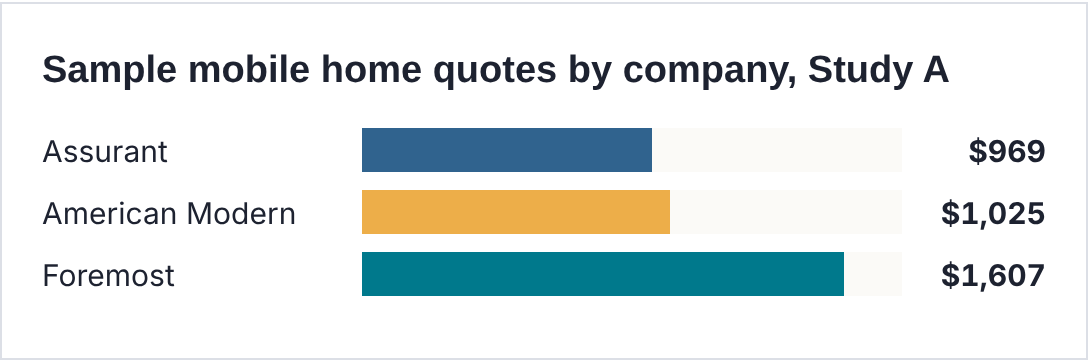
Study A: national mobile home quote study updated July 6, 2026, for a 2016 single-wide in a park in Austin, Indianapolis, and Mesa. Not Illinois quotes.
In the three-city Study A sample, Assurant had the lowest displayed price at $969, American Modern was $1,025 and Foremost was $1,607. The difference reflects only the study’s sample parameters. Do not infer that Illinois prices are lower or higher than Indiana, Wisconsin, Missouri or Kentucky from this table alone.
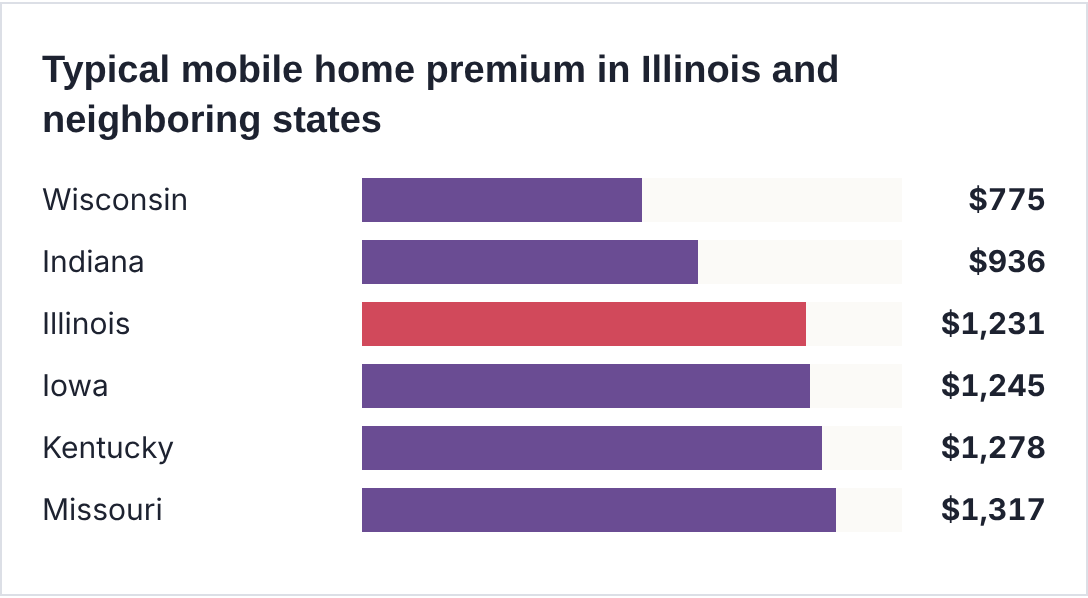
Study E national table (October 18, 2026). Method not published, so treat as rough estimates.
A separate March 2026 study covered conventional site-built Illinois homes insured for $200,000 of dwelling coverage; it listed Allstate at $1,215, USAA at $1,345, Travelers at $1,650 and State Farm at $1,830 annually. Those amounts may be helpful background about the broader property market, but they are not mobile-home insurance prices and should not guide a manufactured-home purchasing decision.
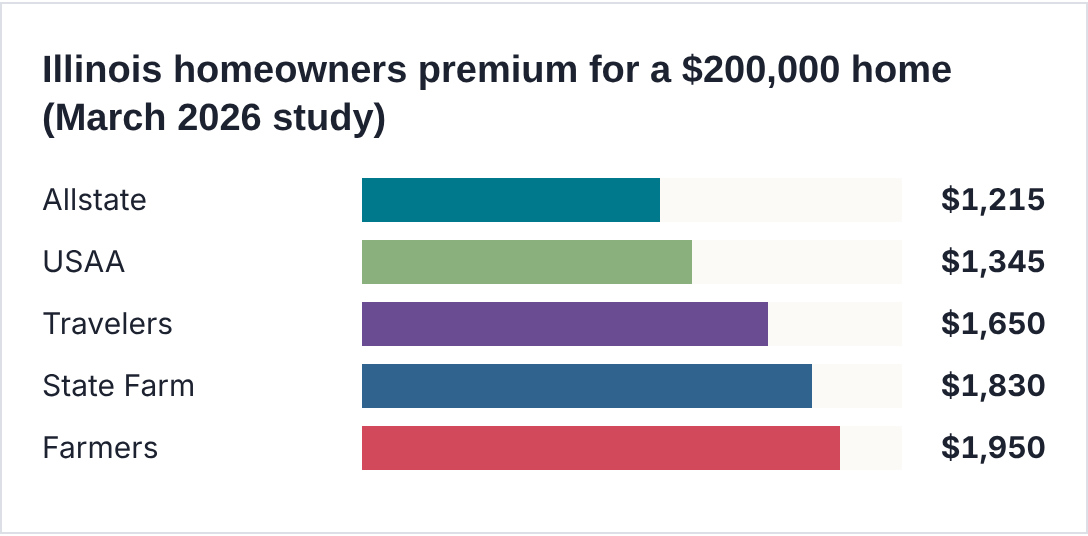
March 2026 national homeowners study, $200,000 dwelling. Standard-home policies, not mobile home policies. Averages, not quotes.
Illinois mobile home insurance price evidence
| Source | Yearly cost | Notes |
|---|---|---|
| Study E, Illinois average | $1,231 | Third-party state estimate; no verified representative rate profile |
| Study A, Assurant | $969 | Sample single-wide, not in Illinois |
| Study A, American Modern | $1,025 | Sample single-wide, not in Illinois |
| Study A, Foremost | $1,607 | Sample single-wide, not in Illinois |
| $200,000 standard home, Allstate | $1,215 | Illinois, March 2026 study |
| National mobile home range | $700 to $2,500 | September 2026 review |
Study A (July 6, 2026); Study E (October 18, 2026); March 2026 national homeowners study; national mobile home review (September 15, 2026).
Illinois studies of conventional homes report substantially different prices depending on the insured building, amount of dwelling coverage, deductible, and location. For instance, selected 2026 studies priced conventional Illinois homes with $300,000–$400,000 coverage at approximately $2,568–$3,240 annually. These estimates must not be compared directly with the manufactured-home estimate of $1,231 because they insure different property types and amounts. Get actual manufactured-home quotes for your specific address.
March 2026 national homeowners study, $400,000 home. Standard homes, not mobile homes. Averages, not quotes.
Illinois mobile homes by the numbers
An analysis using 2024 Census-based housing figures reports approximately 119,544 mobile homes in Illinois, or about 2.2% of its housing stock. This is an external estimate, not an insurance-policy census. Illinois’s Department of Public Health licenses and inspects qualifying mobile-home parks, and inspection requirements depend on park classification and jurisdiction. Before buying in a park, ask for inspection records, evacuation plans, and written lease terms.
Park conditions vary widely. In Champaign County, about 130 state inspections of 29 parks over five years found about 3,800 violations, and only three inspections found none. Before you buy, look at the park’s inspection history and its storm shelter plans.
10 mobile home insurance companies and quote options to compare in Illinois
This is not a verified cheapest-to-most-expensive Illinois ranking. The first three company prices are from one manufactured-home sample in other states. The other entries have no comparable Illinois mobile-home price; they are included for product availability, specialty coverage or distribution reasons. An independent licensed agent may be able to quote multiple carriers, but confirm the underlying company behind each proposal.
Editorial warning: This original image shows prices or a numbered “cheapest” ranking not validated with comparable Illinois manufactured-home quotes. The corrected text and tables take precedence.
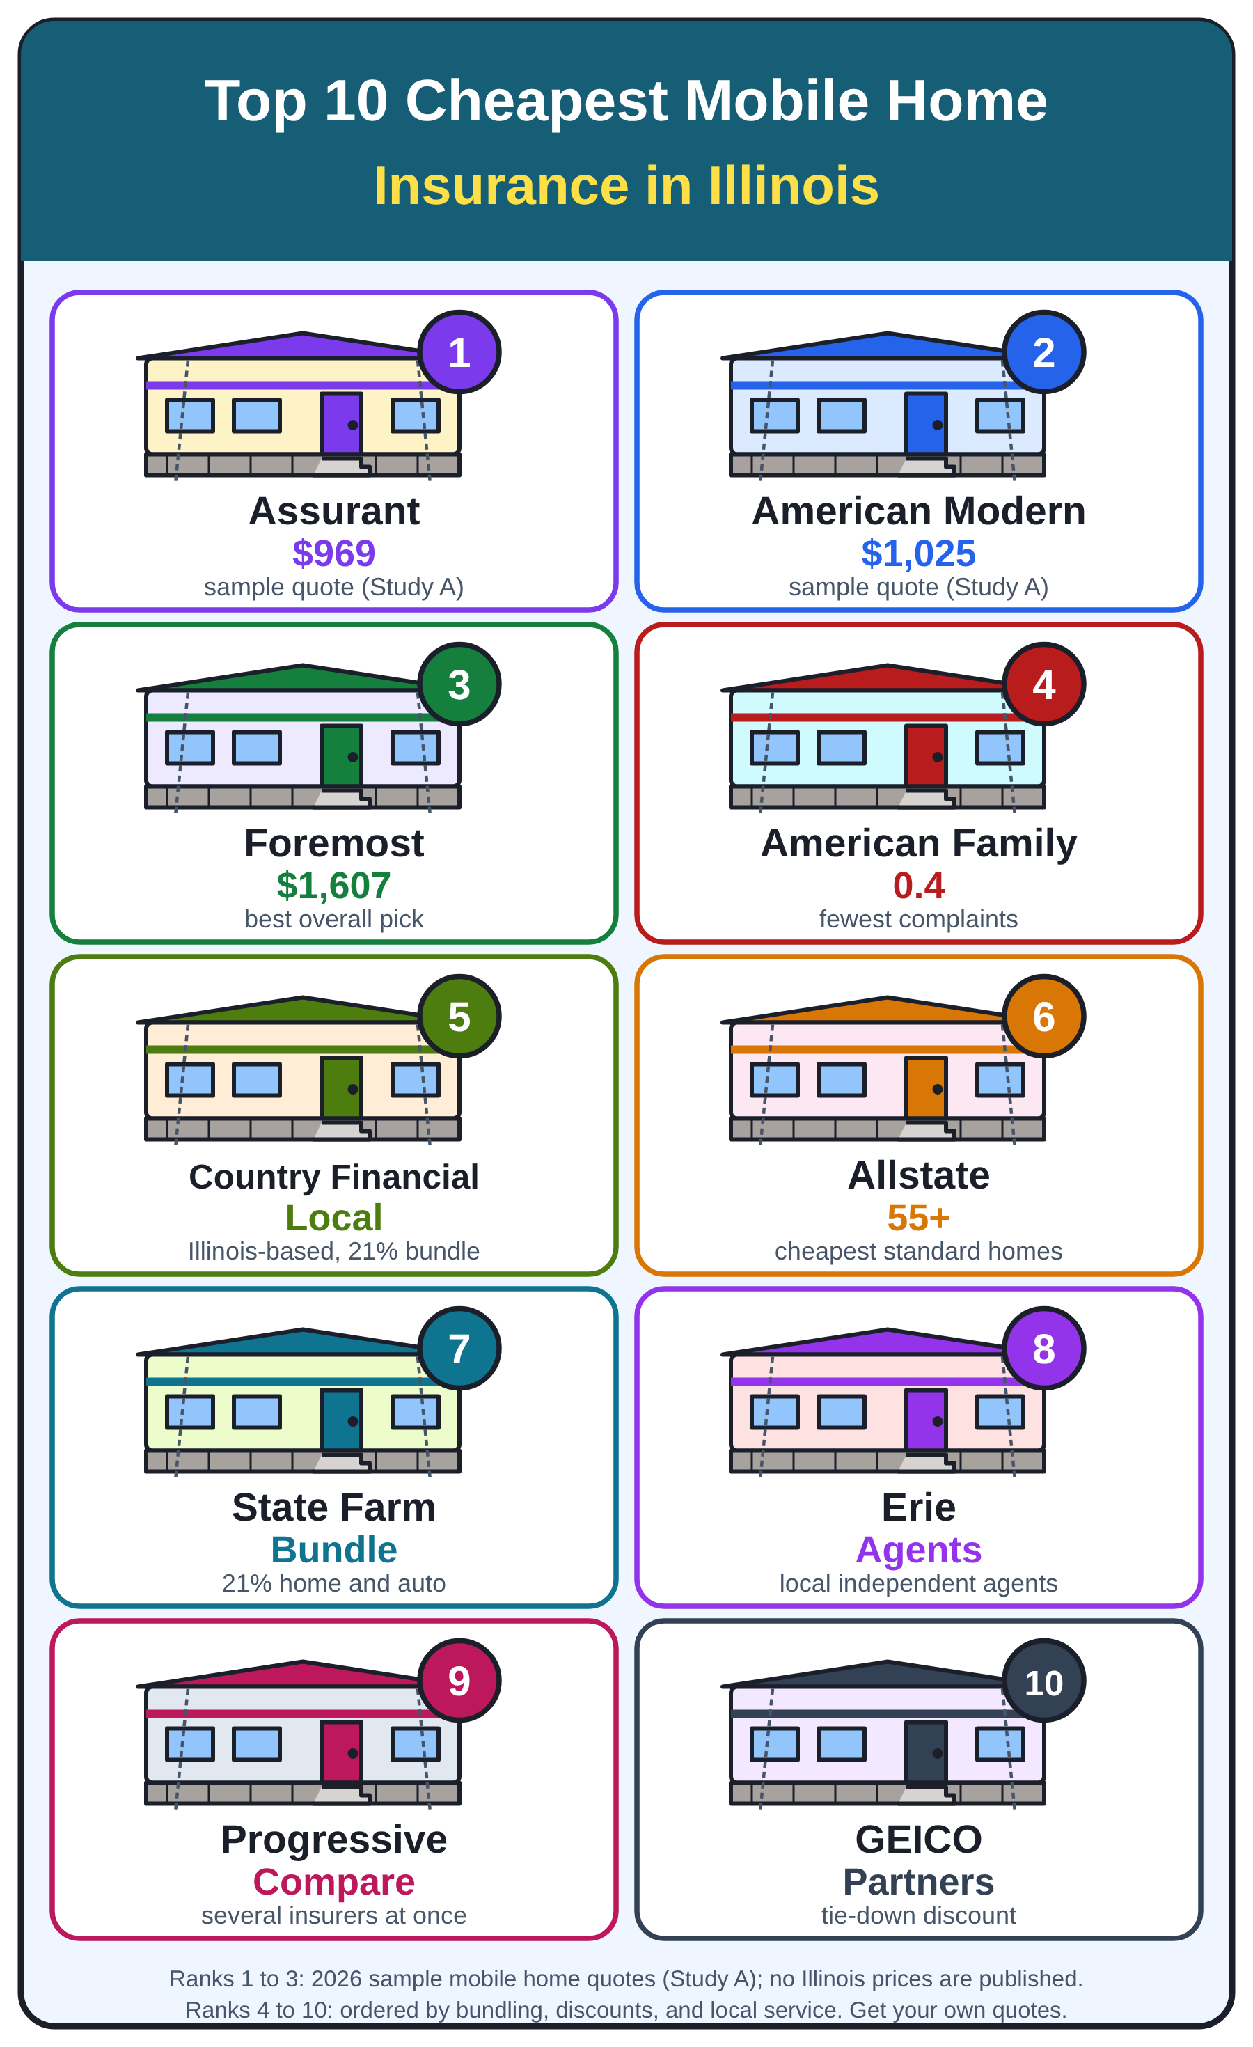
Legacy illustration: numerical ranks refer to editorial list order, not a verified cheapest-company ranking for Illinois. Dollar figures are out-of-state manufactured-home samples.
Ten Illinois manufactured-home insurance options — not price-ranked
| Option (not price-ranked) | Company | Price or evidence | Complaint index |
|---|---|---|---|
| 1 | Assurant | $969 (Study A sample) — OUT-OF-STATE SAMPLE | 3.1 (third-party index; verify insurer entity) |
| 2 | American Modern | $1,025 (Study A sample) — OUT-OF-STATE SAMPLE | 1.4 (third-party index; verify insurer entity) |
| 3 | Foremost | $1,607 (Study A out-of-state sample); specialist coverage options | 0.7 (third-party index; verify insurer entity) |
| 4 | American Family | Manufactured-home product; complaint score from secondary source only | 0.4 (third-party index; verify insurer entity) |
| 5 | Country Financial | Agency may refer manufactured-home risks; bundle rate is for conventional homes | Not verified for Illinois mobile-home line |
| 6 | Allstate | Manufactured-home option; quoted bundle savings are for conventional homes | 1.2 (third-party index; verify insurer entity) |
| 7 | State Farm | Manufactured-home product; conventional homeowners market share is not its mobile-home rate | 1.4 (third-party index; verify insurer entity) |
| 8 | Erie | Writes mobile homes in Illinois through agents | Not verified for Illinois mobile-home line |
| 9 | Progressive | Places policies with partner insurers | 1.8 (third-party index; verify insurer entity) |
| 10 | GEICO | Partner policies; tie-down and skirting discounts | Not rated |
Study A: ValuePenguin (July 2026), quotes from Austin, Indianapolis, and Mesa—not Illinois. Study D: conventional-home auto bundle research, not manufactured-home insurance. Complaint indices are secondary-source company/group examples, not confirmed Illinois manufactured-home subsidiary figures.
1. Assurant: lowest sample price
Assurant was lowest among the three companies in Study A’s out-of-state sample at $969 annually. That does not establish its price for an Illinois address or home. The quoted complaint index in the secondary review should not be applied automatically to every Assurant subsidiary, partner-issued policy, or state: verify the actual underwriting company’s NAIC record.
2. American Modern: low price, broad eligibility
American Modern averaged $1,025 in Study A’s out-of-state sample, $56 above Assurant in that particular comparison. Specialty carriers may consider older manufactured homes, subject to condition, location and underwriting. Confirm the legal insurer and coverage form, not only the brand shown on the quote.
3. Foremost: best overall in Illinois
Foremost’s $1,607 figure also comes from the out-of-state Study A sample. Its manufactured-home specialization, availability of coverage options, and discounts make it a useful Illinois quote candidate, but calling it definitively “best overall” would require a disclosed scoring method and comparable Illinois offers. Check whether the quote uses replacement-cost or actual-cash-value settlement.
4. American Family: fewest complaints
American Family offers manufactured and mobile-home insurance and may be an option for Illinois homes that meet its underwriting rules. A complaint-index figure reported by a third-party review is an indicator worth checking, not proof of the best claim service. Confirm the current rating at the subsidiary and property-insurance line level through state regulatory or NAIC information.
If considering American Family, its company overview in Spanish may help with general insurer background; mobile-home eligibility must still be verified.
5. Country Financial: the Illinois choice
COUNTRY Financial, based in Bloomington, Illinois, offers homeowners products and may refer some manufactured-home customers to specialist carriers. Verify directly with the agent whether the home will be insured by COUNTRY Financial or a different licensed company. The 21% home-auto bundle figure in Study D relates to conventional homeowners insurance and does not establish a mobile-home bundle discount.
6. Allstate: best for retirees
Allstate offers manufactured-home products and may have discounts for eligible retired owners. The quoted 23% bundling result and conventional Illinois homeowners rates come from research on standard houses; they should not be treated as Illinois mobile-home pricing. Ask for a manufactured-home quote with the exact home age, installation and tie-down details.
Readers comparing Allstate as a multi-policy option may consult this Allstate insurer overview in Spanish, then request an Illinois manufactured-home-specific quote.
7. State Farm: Illinois’s largest home insurer
State Farm offers manufactured-home coverage, with underwriting and availability depending on home age, condition, location, and policy options. Its Illinois market share for conventional homeowners insurance does not establish mobile-home market share or pricing. Any home-auto discount taken from a conventional-home study must be separately verified for the manufactured-home policy under consideration.
For homeowners evaluating a State Farm home-auto bundle, this State Farm auto insurance overview in Spanish covers the automobile side; the manufactured-home policy requires a separate quote.
8. Erie, 9. Progressive, and 10. GEICO
Erie and distribution sites such as Progressive or GEICO may be additional ways to request manufactured-home coverage in Illinois, sometimes through partner underwriters. Do not assume a single form produces offers from every carrier. Compare actual issuing insurer, policy form, limits and premium on every proposal so duplicate quotes from the same underwriting company are not counted as independent offers.
PRO TIP #1
Progressive, GEICO, USAA, and Farmers often place policies with Foremost, American Modern, or Assurant. To get truly different prices, make sure your three quotes come from three different underlying insurers, and add American Family or Country Financial as a fourth.
Can we name the cheapest mobile home insurer in Illinois?
Not from the published evidence in this article. Assurant had the lowest figure in Study A’s three-city sample outside Illinois, but that does not make it the cheapest company for Illinois homeowners. American Modern, Foremost, American Family, Allstate, State Farm, COUNTRY Financial and other eligible companies should be evaluated through matched, Illinois-address quotes. A specialized carrier can be better for one home and more expensive or unavailable for another.
Start by requesting three quotes from distinct underwriting insurers for one Illinois home and the same dwelling, personal property and liability limits, loss settlement terms, and wind/hail deductible. If the same specialist underwrites offers marketed through multiple agencies, compare their total premium and fees but count them as one carrier in the market comparison.
Compare Illinois property offers using the same coverage amount and deductible; the general home insurance quote comparison overview discusses quote-shopping questions, but any site-built-house pricing must be adjusted for manufactured homes.
Illinois mobile home insurers to consider by coverage need
Best mobile home insurance in Illinois, by need
| Need | Company to check (not a winner) | Why |
|---|---|---|
| Lowest sample price | Assurant | $969 in Study A |
| Older homes | American Modern | May consider older homes, subject to underwriting |
| Coverage flexibility | Foremost | Complaint index 0.7; 50+ discount |
| Complaint-index research | American Family | Complaint index 0.4 |
| Illinois company | Country Financial | Conventional-home bundle study; mobile-home offer unverified |
| Retirees 55+ | Allstate | Retiree discount may apply; ask for an Illinois quote |
| Online quotes | Progressive | Several partner offers |
Editorial comparison of products and distribution channels; not a validated ranking of the lowest-cost or highest-rated Illinois mobile-home insurers. Prices or bundles for conventional houses are not interchangeable with manufactured-home offers.
Mobile home insurance considerations for seniors in Illinois
Older Illinois homeowners can ask Foremost about age-based discounts and Allstate about discounts for eligible retirees, but neither is verified as the statewide cheapest choice for seniors. Compare the same dwelling value, wind deductibles, and policy form, and remember that a tax reduction under state law is separate from the insurance price.
The Mobile Home Local Services Tax Act, section 7, reduces the tax to 80% of its normal amount for a qualifying title-holding owner who lives in the home and is age 65 or older (or has a qualifying disability). You must apply with the county clerk; filing after May 1 makes the reduction begin with the next annual bill. This is a tax benefit, not an insurance-premium discount. Real-property tax exemptions, where applicable, have separate eligibility rules.
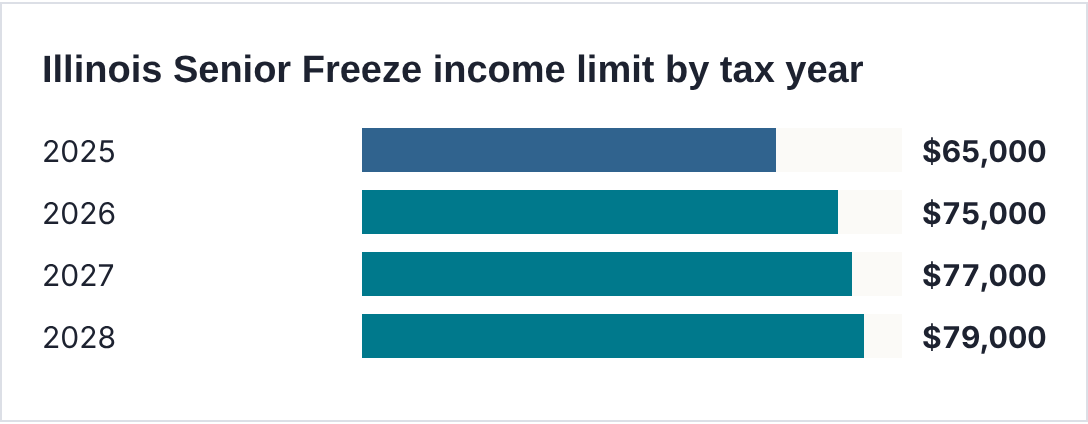
Kane County Assessments, Senior Assessment Freeze. Applies to real property; check whether your home qualifies.
PRO TIP #2
If you own and occupy the home and meet the age or disability criteria, ask the county clerk for the Mobile Home Local Services Tax reduction before May 1 to avoid delaying its application. Separately request actual insurer discount quotes: an advertised 50+ or retired-owner discount does not mean your entire premium falls by that percentage.
The Illinois mobile home privilege tax
Illinois’s Mobile Home Local Services Tax (sometimes called the privilege tax) can apply to qualifying mobile or manufactured homes, often in parks. It is calculated from square footage and the rate schedule under 35 ILCS 515/3, generally declining from 15 cents per square foot in the initial period to 7.5 cents after the relevant age threshold. However, tax treatment can differ for a home classified as real property or located outside a park, so confirm the category with the county assessor instead of assuming every Illinois mobile home pays this tax.
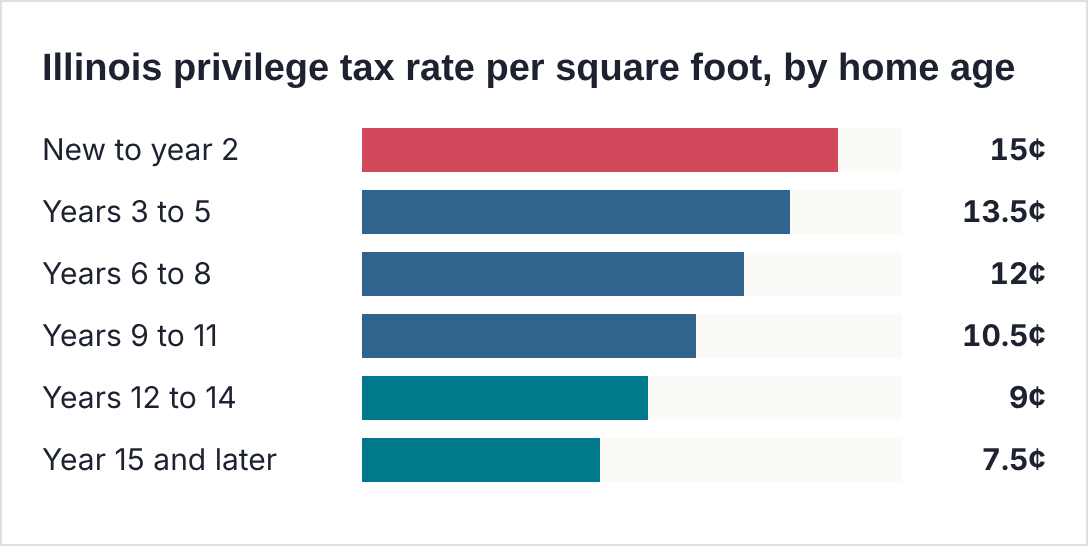
35 ILCS 515/3, Mobile Home Local Services Tax Act.
For example, a 14-by-70-foot single-wide has 980 square feet, so it would owe about $147 a year when new and about $73.50 a year once it is 15 or older, before any senior reduction (our calculation). That is far less than property tax on most site-built homes.
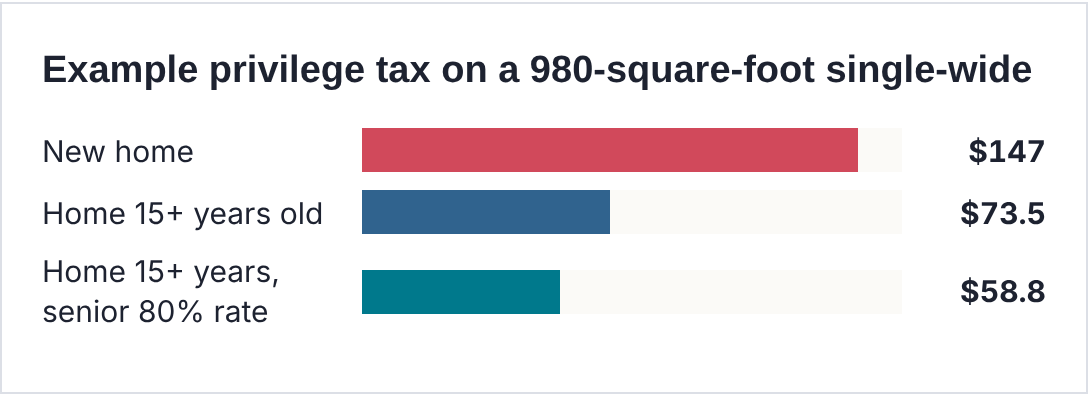
Our calculation uses 35 ILCS 515/3 and 515/7 rates. Actual bills may include local adjustments.
Tornadoes and mobile homes in Illinois
Illinois set a preliminary annual tornado record in 2026. According to the Illinois State Climatologist’s September 8 report, 210 tornadoes had been confirmed by the start of September, more than the previous annual record of 142. Counts remain subject to post-storm review. Manufactured-home owners should prioritize reliable warnings, a designated sturdy off-site shelter, and a policy that explains wind/hail protection and any separate wind deductible.
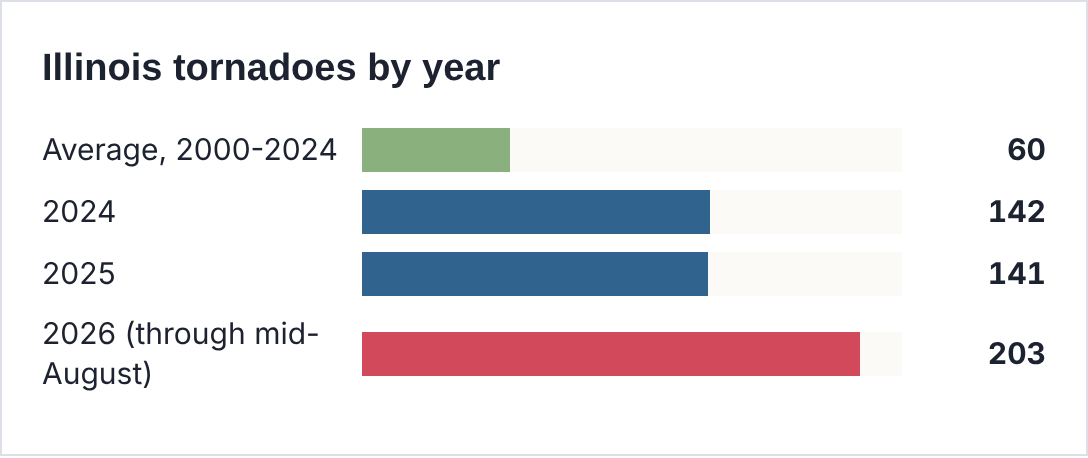
Illinois State Climatologist; KWQC; Northern Public Radio (August 18, 2026). 2026 count is preliminary.
Mobile and manufactured homes provide inadequate protection during a tornado, even when tied down. The National Weather Service recommends arranging shelter in a sturdy building in advance and leaving before the storm reaches the park; a tornado watch can be the time to activate that plan rather than waiting until travel is unsafe. Anchors help reduce some wind damage but do not turn a mobile home into a tornado shelter. Historical Illinois tornado examples in the table illustrate the risk, not the likelihood of a claim at your address.
Recent Illinois tornadoes
| Date | Where | What happened |
|---|---|---|
| December 1, 2018 | Taylorville | EF3; at least 500 homes damaged |
| December 10, 2021 | Edwardsville | EF3; 6 deaths at an Amazon warehouse |
| March 31, 2023 | Robinson | EF3; 3 deaths, 2 in mobile homes |
| July 15, 2024 | Chicago area | 32 tornadoes in one derecho |
| May 16, 2025 | Marion | EF4, 190 mph; mobile homes damaged |
| June 21, 2026 | Jefferson County | 2 deaths in separate mobile homes |
National Weather Service; Illinois State Climatologist; ABC7 Chicago; storm summaries.
PRO TIP #3
Ask a qualified installer to inspect anchors and tie-downs, but do not rely on them for personal tornado safety. Identify a designated community storm shelter or substantial nearby building, arrange how to reach it while conditions are still safe, and make an accessible plan for children, older residents and pets. Check the policy’s wind/hail deductible and replacement-cost provisions separately.
Hail, floods, and earthquakes
Illinois has experienced exceptionally large hail and severe rainfall, including a state-record hailstone reported in 2026. Unlike ordinary storm or burst-pipe water damage, flooding from rising water is usually excluded by standard manufactured-home policies. Where eligible, NFIP flood insurance can cover a properly anchored manufactured home up to the program’s residential limits, generally $250,000 for the building and $100,000 for contents, with a typical 30-day waiting period and important exceptions. Check that any flood policy covers your home’s construction and foundation.
Parts of southern Illinois are exposed to earthquake hazards associated with regional seismic zones. Standard manufactured-home policies often exclude earthquake losses; ask whether a separate endorsement is available, what its deductible is, and whether your anchoring, foundation and structure qualify. A precise 100-year probability for individual towns should not be assumed without a site-specific geological study.
Mine subsidence coverage in Illinois
Abandoned underground mines create a risk of ground settlement in parts of Illinois. Under state law, insurers include mine-subsidence coverage in property policies for buildings within 34 designated counties, subject to statutory provisions and waiver rules; different options apply elsewhere. Do not assume every manufactured-home policy automatically offers the same endorsement, building coverage limit, or deductible as an ordinary homeowners policy. Ask the agent to identify the relevant form and coverage for your exact address and home type; the Illinois Mine Subsidence Insurance Fund explains how to check risk.
Illinois mine subsidence coverage
| Item | Details |
|---|---|
| Program | Illinois Mine Subsidence Insurance Fund |
| Required in | 34 counties |
| Maximum coverage | Depends on residential coverage and policy form; confirm with agent |
| Example cost | Quote required; no verified Illinois manufactured-home rate |
| Mobile homes | Ask your agent about eligibility |
Sources: Illinois Mine Subsidence Insurance Fund and 215 ILCS 5/805.1. The often-cited $750,000 maximum in secondary sources should not be assumed to apply to a particular residential mobile-home policy.
Illinois park residents’ rights
The Illinois Mobile Home Landlord and Tenant Rights Act generally requires covered parks to offer a written lease lasting at least 24 months unless the resident agrees otherwise. Rent increases generally require at least 90 days’ notice under the applicable rules, and park closure generally calls for at least 12 months’ notice. Specific procedures for responding to lease offers and rent increases depend on the type of tenancy; do not assume every tenant has the same 30-day deadline in every situation.
Illinois park resident protections
| Protection | Details |
|---|---|
| Lease length | Must offer at least 24 months |
| Rent increase notice | 90 days |
| Time to decide | Varies with tenancy, notice and lease; request written terms |
| Park closure notice | At least 12 months |
| Park inspections | Yearly, by the Illinois Department of Public Health |
765 ILCS 745; 210 ILCS 115; Illinois Department of Public Health.
Illinois laws every mobile home owner should know
- We found no Illinois law requiring mobile home insurance, but lenders do, and many parks require it in the lease.
- Installers must be licensed by the Department of Public Health, at $150 a year, plus $50 per home and $395 per state inspection.
- Homes moved since 1980 must be tied down to state standards.
- Manufactured-home treatment as real property depends on the property and statutory conditions; confirm the specific process with the county and Secretary of State rather than assuming an affidavit alone changes the tax status.
- Manufactured-home wind and roof-load classifications must be checked against the HUD map and the home’s data plate for the exact location; do not infer that every local hazard or private policy is covered by a minimum construction designation.
Illinois mobile home rules at a glance
| Item | Rule |
|---|---|
| Installer | IDPH license; $150 a year plus fees |
| Tie-downs | Required to state standards for homes moved since 1980 |
| Real property | Depends on land ownership and statutory classification |
| Tax | Local services or real-property tax depending on status |
| Senior tax help | 80% privilege tax rate at 65+; Senior Freeze for real property |
| Wind and roof zones | Check the HUD map and home data plate for exact location |
Illinois Department of Public Health; 765 ILCS 170; 35 ILCS 515; 24 CFR 3280.305.
The Illinois FAIR Plan and new rate rules
Illinois FAIR Plan Association documentation expressly lists “mobile homes at a fixed location” as potentially eligible for its Dwelling Property program. The listed form is Basic DP-1, actual-cash-value coverage for limited named perils; theft and liability coverage are not available through that specific dwelling-property form. Eligibility, inspection, available limits and premium require review by a participating producer. It is a fallback when standard insurance is not available—not a substitute for comparing broader manufactured-home policies. Source: Illinois FAIR Plan Producer Summary.
Illinois conventional homeowners insurance costs increased sharply in the first half of the decade, based on published market studies. On August 4, 2026, the governor signed House Bill 4273, adding property-insurance rate review standards and 60-day advance notice when qualifying renewal premiums increase by more than 10%. The rate-review provisions begin July 1, 2027; their application to a specific manufactured-home policy depends on the statute and policy category. The law does not set a general 10% cap or guarantee that rates will fall.
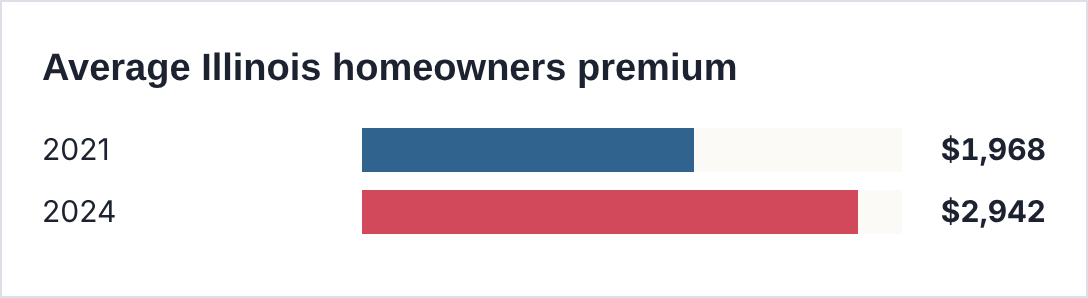
WGLT (April 2, 2025), citing a national insurance study.
Chicago-area mobile home insurance
Chicago has the highest homeowners premiums in Illinois, with averages of $2,772 to $3,745 a year in 2026 studies, although Allstate was cheapest in the city in Study B, at $1,074. Mobile home parks in the region sit mostly in the suburbs and collar counties, around towns such as Elgin, Grayslake, Monee, and Joliet.
Chicago-area owners comparing home-auto bundles can also consult Chicago auto insurance options in Spanish before calculating their combined premium.
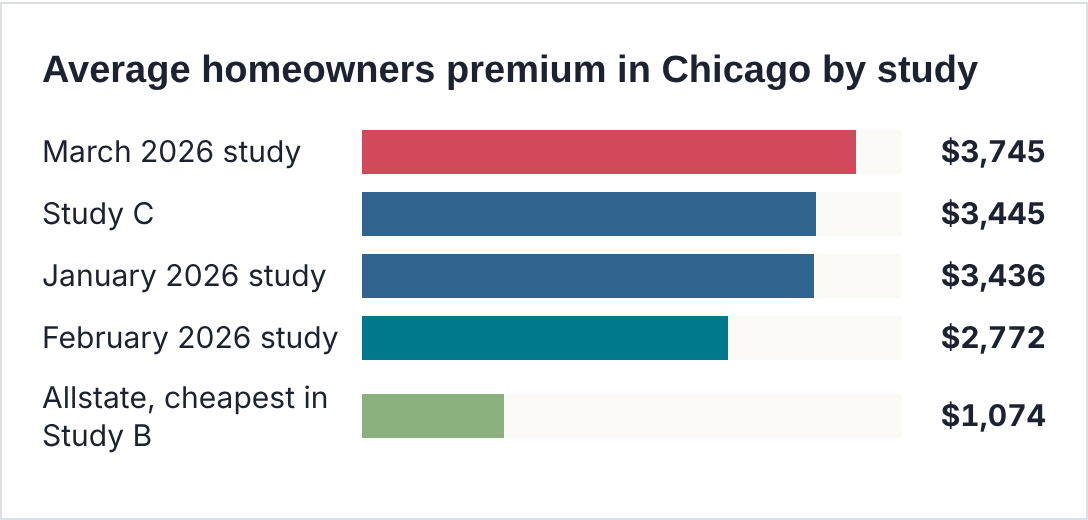
2026 Illinois homeowners studies; Study B; Study C. Standard homes, not mobile homes. Averages, not quotes.
The biggest Chicago-area risks are hail, derechos, and flash floods. The July 15, 2024, derecho produced 32 tornadoes in the Chicago area, and the July 2023 storm flooded basements and streets across the western suburbs. Check your wind and hail deductible, and price flood insurance even if your lender does not require it.
Central and southern Illinois mobile home insurance
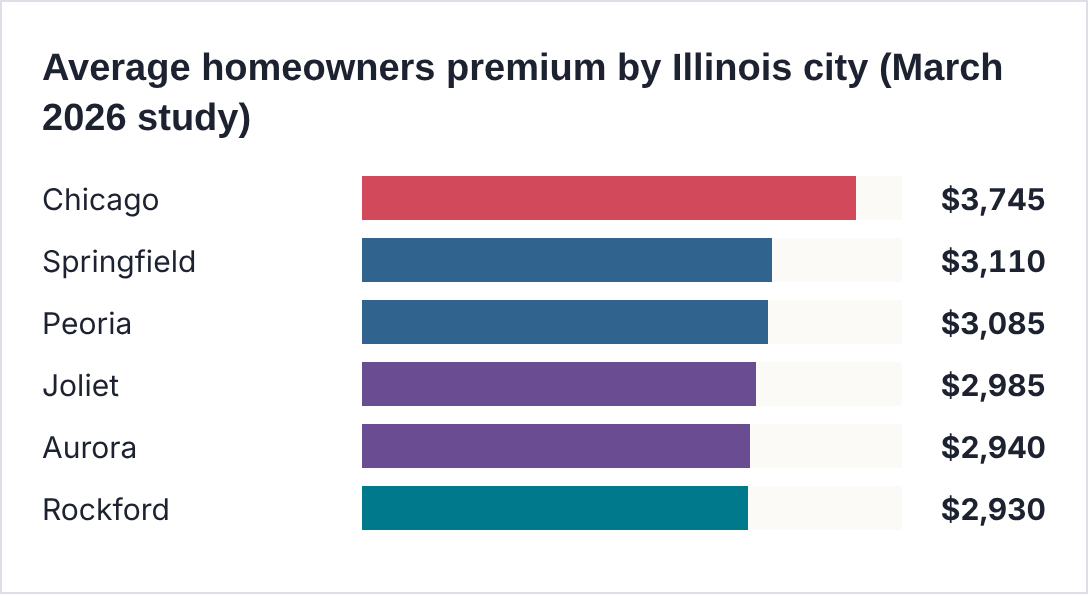
Homeowners pay less outside Chicago, with 2026 averages of about $2,292 to $2,930 in Rockford, $2,388 to $3,110 in Springfield, and $2,400 to $3,085 in Peoria. Many mobile homes downstate sit on private land, which can mean larger claims for sheds, garages, and outbuildings.
Average homeowners premium in other Illinois cities
| City | March 2026 study | Study C |
|---|---|---|
| Springfield | $3,110 | $3,055 |
| Peoria | $3,085 | $3,039 |
| Joliet | $2,985 | $2,910 |
| Aurora | $2,940 | $2,920 |
| Rockford | $2,930 | $2,874 |
March 2026 national homeowners study; Study C (October 2026). Standard homes, not mobile homes.
Downstate risks differ from the city. Central Illinois has the most tornadoes and much of the state’s mine subsidence risk, while far southern Illinois, around Marion, Carbondale, and Cairo, faces both strong tornadoes and earthquake risk from the New Madrid zone.
Common reasons mobile home claims are denied
- The home was not tied down or anchored as the policy required.
- The damage came from flooding, which a standard policy excludes.
- The damage built up over time, such as a slow leak or rot.
- Ground movement from an earthquake or old mine was not covered.
- The policy paid actual cash value, so an older roof or home was depreciated.
Mobile home insurance vs. homeowners insurance in Illinois
How Illinois mobile home and homeowners policies compare
| Feature | Mobile home policy | Homeowners policy |
|---|---|---|
| Typical yearly cost | ~$1,231 in unverified Study E state estimate | Different construction and coverage profiles; not comparable |
| Main insurers | Foremost, American Modern, Assurant, American Family | State Farm, Allstate, Country Financial |
| Tax | Tax category depends on classification and location | Property tax |
| Biggest risk factor | Tie-downs and anchoring | Roof age and construction |
| Flood coverage | Separate policy | Separate policy |
Study B; Study E; 2026 homeowners studies; 35 ILCS 515.
What Illinois mobile home insurance covers
Main coverage parts of an Illinois mobile home policy
For a general introduction to dwelling, belongings and liability sections, see home insurance coverage fundamentals; manufactured-home policies may differ.
| Coverage | What it pays for |
|---|---|
| Dwelling | Repairs or replacement of the home |
| Other structures | Carports, decks, sheds, and skirting |
| Personal property | Furniture, clothes, and belongings |
| Loss of use | Living costs after a covered loss |
| Personal liability | Injuries or damage you cause to others |
| Not usually covered | Flood, earthquake, and mine subsidence |
Company policy descriptions; coverage varies by insurer.
Illinois mobile home insurance by region
Main risks and coverage needs by Illinois region
| Region | Main risk | What to check |
|---|---|---|
| Chicago area | Hail, derechos, and flash floods | Wind and hail deductible, flood insurance |
| Central Illinois (Springfield, Peoria, Champaign) | Tornadoes and mine subsidence | Tie-downs, mine subsidence coverage |
| Southern Illinois (Marion, Carbondale) | Tornadoes and earthquakes | Earthquake add-on, tie-downs |
| Northern Illinois (Rockford) | Severe storms and winter weather | Roof and frozen pipe coverage |
Our assessment, based on National Weather Service, Illinois State Climatologist, and IMSIF information.
How to check an insurer’s service record
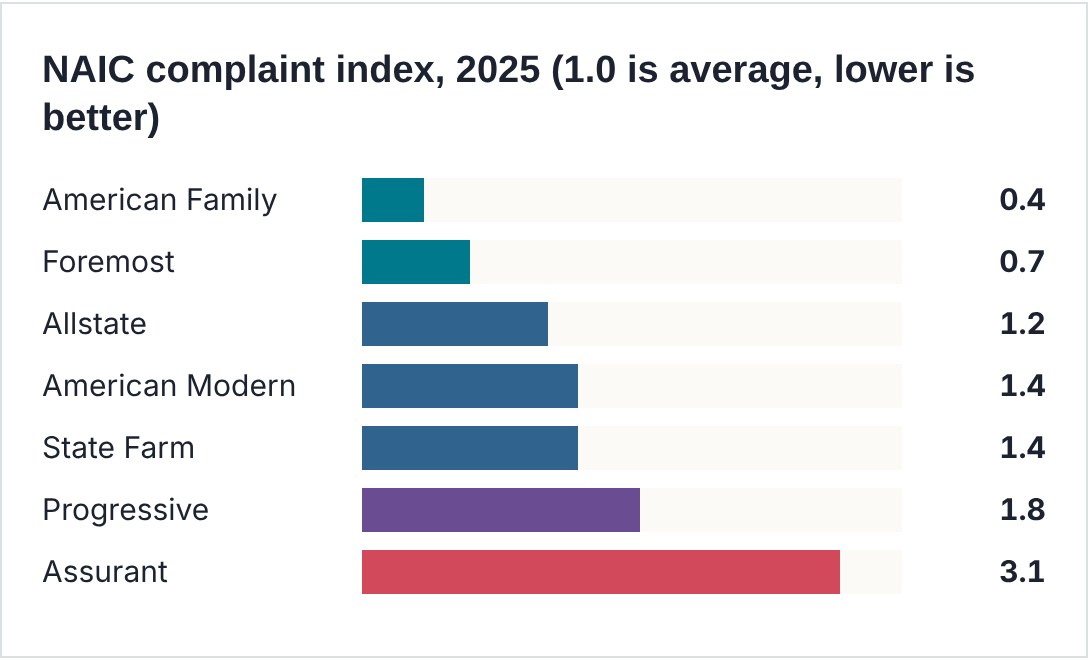
NAIC complaint index for 2025, as reported in a national mobile home review updated September 15, 2026.
Bundling mobile home and auto insurance in Illinois
We did not identify a reliable Illinois study measuring manufactured-home plus auto bundle savings. Studies cited here concern conventional house insurance. A bundling percentage is not proof of the lowest total price: compare bundled and separate insurer quotes that include the same limits, deductibles, loss settlement and all fees.
When a bundle is offered, compare the auto side against other car insurance companies instead of assuming the bundled price is the lowest total.
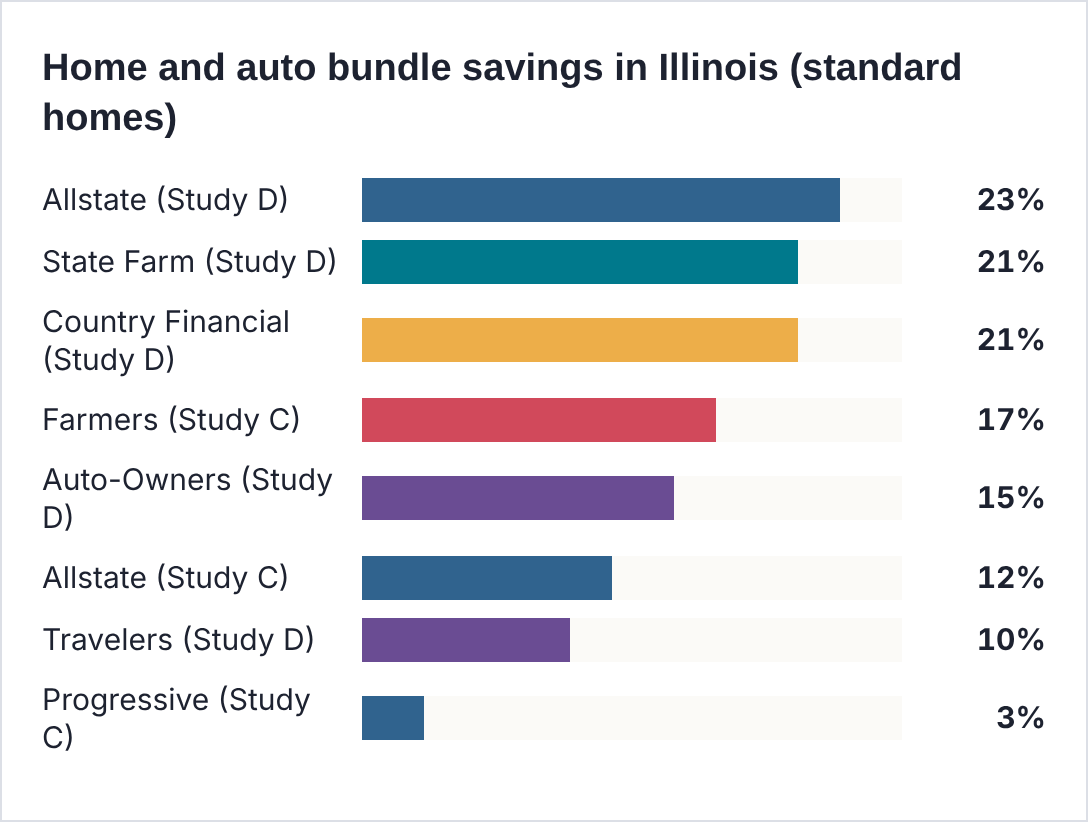
Study C: Illinois bundle study updated August 5, 2026; Study D: Illinois bundle study updated April 20, 2026. Figures are for standard homes, not mobile homes.
Conventional-home bundle figures for Nationwide or other insurers cannot establish a manufactured-home price or even eligibility. Ask each company whether it underwrites your construction type, whether an auto bundle is actually offered for it, and which legal company issues the property policy. Compare the total combined premium against separately purchased coverage.
Mobile home insurance discounts in Illinois
Discounts to ask for in Illinois
| Discount | Who offers it |
|---|---|
| Age 50+ or retired 55+ | Foremost (50+), Allstate (retired, over 55) |
| Newer home | Foremost, State Farm |
| Approved park | Foremost |
| Tie-downs and full skirting | GEICO |
| Home alarms | State Farm |
| Long-time customer | State Farm |
| Multi-policy | Most insurers |
Company websites (2025 to 2026). Discount amounts vary.
Insuring older and pre-1976 mobile homes in Illinois
Homes built before the federal manufactured-housing standards took effect in June 1976 may be harder to insure, but eligibility varies by condition, upgrades, anchoring, age and insurer. Specialty companies such as Foremost and American Modern may be worth asking about. Do not assume a carrier insures every pre-1976 home. Illinois’s FAIR Plan lists eligible mobile homes at fixed locations for limited DP-1 dwelling coverage, subject to underwriting.
Park homes vs. homes on private land
Approved-park status and anchoring may affect a manufactured-home quote; some specialist carriers offer related discounts subject to underwriting. Residents of covered Illinois parks also have lease and notice protections, but those legal rights do not guarantee lower insurance prices. Homes on private land may need additional protection for outbuildings, liability exposures, and possible mine-subsidence hazards.
How much coverage you need
Ask an insurer or knowledgeable manufactured-home contractor to estimate the cost of a comparable replacement home including delivery, installation, anchoring, site preparation, and debris removal where covered. Land value is not dwelling insurance. Choose a policy limit and settlement method based on what the insurer will actually pay; check personal-property, additional-living-expense and liability limits and whether you can afford the deductible after a tornado.
Tips to save money on mobile home insurance in Illinois
- Get at least three quotes, starting with Assurant, American Modern, and Foremost.
- Add American Family and Country Financial for comparison.
- Make sure your quotes come from different underlying insurers.
- Ask for age, park, newer-home, and tie-down discounts.
- Apply for the 20% senior privilege tax reduction if you are 65 or older.
- Buy flood insurance if you live near a river or in a low area.
- Check mine subsidence coverage in coal-country counties.
- Shop again every year, since Illinois rates have risen fast.
How to compare Illinois mobile home insurance quotes
- Use the same dwelling limit, liability limit, and deductibles for every quote.
- Check whether there is a separate wind and hail deductible.
- Check whether each quote pays replacement cost or actual cash value.
- Ask which discounts are already applied.
- Add flood and earthquake costs when you compare totals.
Use a home insurance policy comparison checklist to match perils and deductibles, without substituting conventional-home rates for mobile-home quotes.
Questions to ask before you buy
- Is there a separate wind and hail deductible, and how is it calculated?
- Does the policy pay replacement cost or actual cash value?
- Is mine subsidence coverage included in my county?
- Are carports, decks, skirting, and sheds covered?
- Which insurer will actually handle my claims?
What to do after a tornado or hailstorm
- Get to safety, then call your insurer or agent as soon as you can.
- Take photos and video of all damage before cleaning up.
- Make temporary repairs and keep the receipts.
- Be wary of door-to-door contractors after a storm.
- If you have a problem, call the Illinois Department of Insurance at 866-445-5364.
Illinois mobile home insurance at a glance
The following original illustration summarizes the older article. Several price or ranking claims printed inside the image are not validated for Illinois mobile homes; rely on this corrected article’s methodology and comparison table instead.
Editorial warning: This original image shows prices or a numbered “cheapest” ranking not validated with comparable Illinois manufactured-home quotes. The corrected text and tables take precedence.
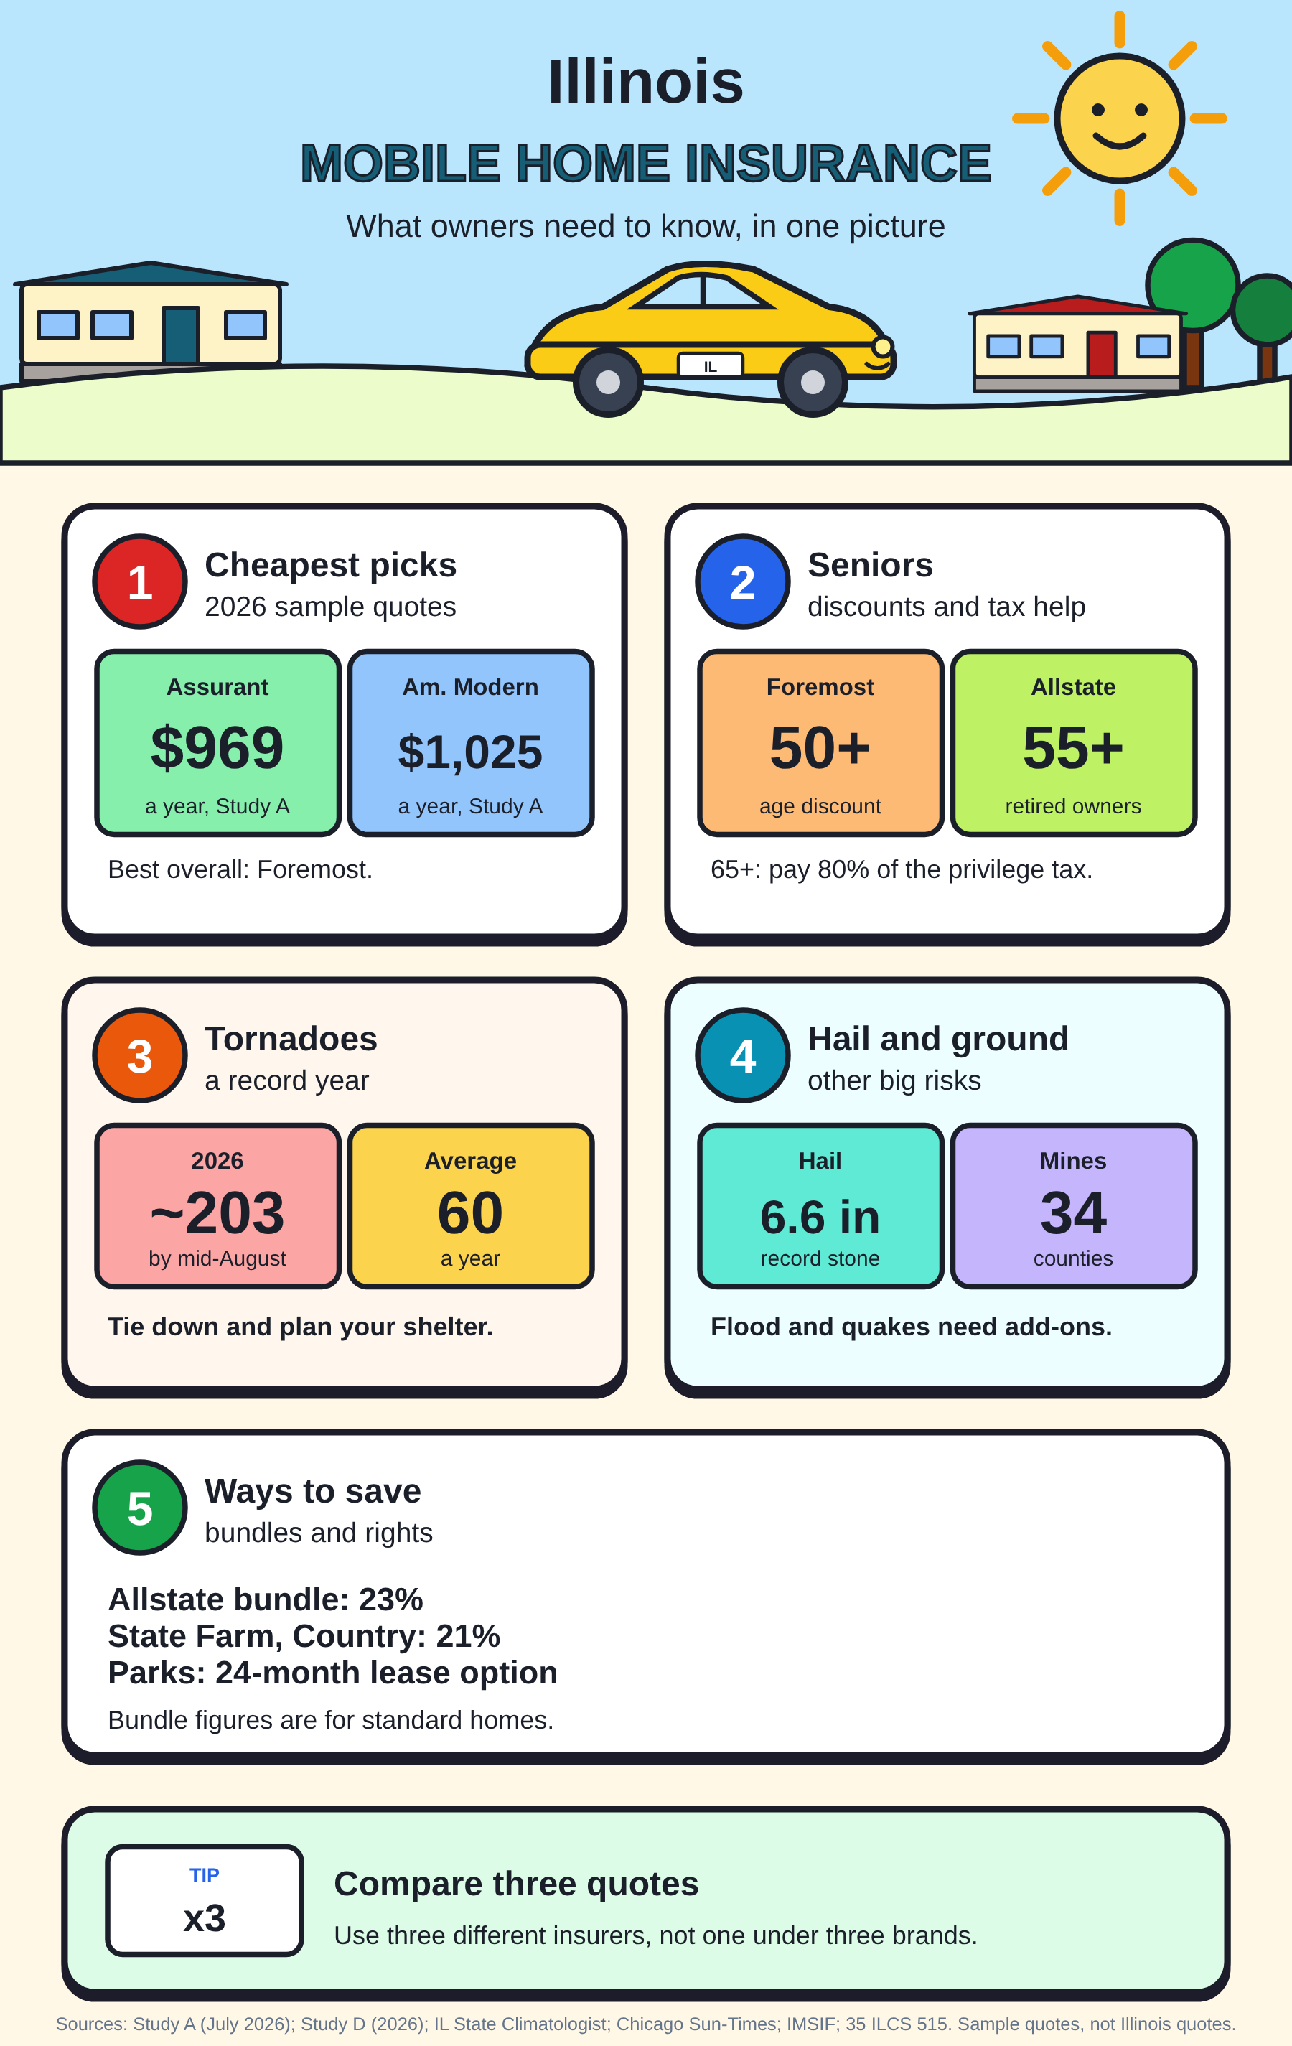
Illinois mobile home insurance at a glance. Sources: Study A; Study D; Illinois State Climatologist; IMSIF; 35 ILCS 515.
Frequently asked questions about Illinois mobile home insurance
How much is mobile home insurance in Illinois?
A third-party state table lists about $1,231 annually, but does not disclose enough underwriting and sampling data to validate that as a statewide average. Actual premiums vary by Illinois address, home age, replacement value, tie-downs, covered perils and deductibles.
Who has the cheapest mobile home insurance in Illinois?
No statewide company winner is established by the studies cited. Assurant’s $969 sample rate and American Modern’s $1,025 sample rate were obtained outside Illinois. Compare Illinois quotes for the same manufactured home, liability limit, deductible and settlement type.
What is the best mobile home insurance company in Illinois?
There is no independently validated universal best carrier for Illinois manufactured homes in the cited sources. Foremost and American Modern are relevant specialist options, while American Family and other insurers may also qualify; your home, quote, policy exclusions and claim-service record determine the practical choice.
What is the best mobile home insurance for seniors in Illinois?
Foremost offers a discount at 50, and Allstate offers one for retired owners over 55. Owners 65 and older also pay only 80% of the mobile home privilege tax.
What is the Illinois mobile home privilege tax?
It is a yearly tax most mobile homes pay instead of property tax, based on square footage times a rate of 7.5 to 15 cents depending on the home’s age.
Does mobile home insurance cover tornado damage in Illinois?
Many manufactured-home policies cover tornado wind damage, but it depends on the policy form, exclusions, settlement terms and any separate wind/hail deductible. Flooding, earthquake and mine subsidence generally need additional or specifically included coverage. Verify the declarations and endorsements.
Is mobile home insurance required in Illinois?
We found no state law requiring it, but lenders do, and many parks require it in the lease. After a record tornado year, coverage is strongly recommended.
The final word on Illinois mobile home insurance
Illinois manufactured-home insurance deserves a comparison of actual policies rather than an unsupported statewide “cheapest insurer” ranking. Assurant, American Modern and Foremost have published sample prices from other states; other options, including American Family, Allstate, State Farm and local agency partners, may offer a suitable Illinois quote depending on the home. The Illinois FAIR Plan can be considered for eligible fixed-site mobile homes when the standard market is unavailable, but its DP-1 protection is limited.
Severe wind, hail, flooding and ground-movement hazards differ by Illinois county. Compare three distinct underlying insurers using matching dwelling limits, deductibles, loss-settlement terms and exclusions. Ask about tornado wind damage, flood insurance, mine subsidence, replacement costs and any bundle discount before buying; plan a sturdy off-site tornado shelter separately from your insurance policy.
Sources
- Study A: ValuePenguin, mobile home insurance (July 6, 2026).
- Study B: ValuePenguin, cheap homeowners insurance in Illinois (2026).
- Study C: MoneyGeek, best home and auto bundle in Illinois (August 5, 2026), and average cost of home insurance in Illinois (October 29, 2026).
- Study D: Insurance.com, cheapest home and auto bundle in Illinois (April 20, 2026).
- Study E: Insuranceopedia, mobile home insurance by state (October 18, 2026).
- LendingTree, best mobile home insurance companies (September 15, 2026); Illinois homeowners insurance; home insurance for seniors; and NerdWallet, Illinois homeowners insurance (March 2026).
- NerdWallet, Country Financial review; State Farm, manufactured homes; SuperMoney, Allstate mobile home; SuperMoney, Erie mobile home; GEICO, mobile home insurance; and Jerry, Nationwide and mobile homes.
- Insurance Business, State Farm Illinois rates and market share (July 2025); St. Louis Public Radio, State Farm 8% increase (October 2026); Capitol News Illinois, rate review law (2026); and WGLT, 50% price increase (April 2025).
- HomeSnacks, mobile homes by state (2024 Census data); MHVillage, Illinois homes; Illinois Department of Public Health, manufactured homes; and CU-CitizenAccess, Champaign park inspections (October 2025).
- Illinois State Climatologist, 2024 weather; KWQC, 2025 tornado count; Northern Public Radio, 2026 severe weather; and ABC7 Chicago, Jefferson County tornadoes (June 2026).
- 2023 Robinson-Sullivan tornado; National Weather Service, Crawford County tornado; 2025 Marion tornado; WILL, Taylorville tornado; and National Weather Service, mobile home safety.
- Chicago Sun-Times, record hailstone (September 2026); National Weather Service, July 2023 flooding; Illinois DNR, flood insurance; FEMA, manufactured homes flood coverage; and NBC Chicago, earthquake risk.
- Illinois Mine Subsidence Insurance Fund, FAQ.
- 765 ILCS 745/6, leases and rent increases; 765 ILCS 745/8.5, park closures; Manufactured Home Quality Assurance Act; and 765 ILCS 170, conversion to real property.
- 35 ILCS 515/3, privilege tax rates; 35 ILCS 515/7, senior reduction; Rock Island County, privilege tax; and Kane County, Senior Freeze.
- Public Act 104-0645, FAIR Plan; Illinois Department of Insurance, contact; and 24 CFR 3280.305.
- Illinois FAIR Plan Association, Producer Summary—eligible fixed-location mobile homes under basic DP-1
- Illinois General Assembly, 35 ILCS 515/7—reduction of local services tax to 80% for eligible owners
- Illinois State Climatologist, Illinois Severe Weather Update (September 8, 2026)—210 preliminary tornadoes
- Illinois General Assembly, Mobile Home Landlord and Tenant Rights Act (765 ILCS 745)
- Illinois Mine Subsidence Insurance Fund, Am I at Risk?
- Illinois governor, August 4, 2026 insurance reforms and July 1, 2027 implementation
- National Weather Service, Tornado safety in mobile homes
Disclaimer
This website provides independent reviews and comparisons. It is not affiliated with, endorsed by, sponsored by, or connected to Assurant, American Modern, Foremost, Farmers, American Family, Country Financial, Allstate, State Farm, Erie, Progressive, GEICO, USAA, Travelers, Auto-Owners, Nationwide, the Illinois FAIR Plan, the Illinois Mine Subsidence Insurance Fund, or any of their affiliates.
All company names, brand names, trademarks, and logos are the property of their respective owners and are used here only to identify the companies being reviewed. Their use does not imply any affiliation or endorsement.
The information on this page is provided for general informational and educational purposes only. It is not insurance, legal, tax, or financial advice, and it is not an offer, quote, or solicitation to buy or sell insurance. We are not an insurance company, insurance agency, or licensed insurance producer, and we cannot bind coverage, change a policy, or handle claims.
Prices, discounts, ratings, and company details are drawn from public sources and third-party studies that use specific home profiles, and they can change at any time. They are estimates and averages, not guarantees of what you will pay. Coverage, eligibility, and discounts vary by location, home, and owner, and are subject to each insurer’s underwriting rules and policy terms.
While we make reasonable efforts to keep this guide accurate and current, we make no representations or warranties, express or implied, about its completeness, accuracy, or reliability. Opinions here are our own. Always confirm details directly with the insurer, read your policy documents, and consult the Illinois Department of Insurance or a licensed professional before making a decision. Your use of this information is at your own risk, and we are not liable for any loss or damage arising from reliance on it.