
Cheapest Toyota GR Corolla Insurance: Costs, Coverage & Companies
Buyers chasing the cheapest Toyota GR Corolla insurance quickly find that a 300-horsepower hatchback costs more to cover than the Corolla it is based on. Study A’s October 2026 average for a 40-year-old driver is $3,346 a year, or $279 a month, while Study C estimates $2,627 a year for a 40-year-old with good credit.
The GR Corolla arrived for the 2023 model year as Toyota’s rally-inspired hot hatch. It uses a turbocharged 1.6-liter three-cylinder making 300 horsepower and 295 pound-feet of torque, with all-wheel drive on every car. A six-speed manual is standard, and an eight-speed automatic costs $2,000 more. For 2026, the lineup was trimmed to two versions, priced from $41,115 to $47,160 with destination.
This guide compares GR Corolla sample premiums, a shortlist of insurers based on related Toyota vehicles, and coverage options. It also covers model years, the 2026 limited-run GRMN, recall checks, modifications, track-day exclusions, state comparisons and discounts. Since insurer-specific GR Corolla prices are unavailable in the sources reviewed, our shortlist is not a GR Corolla price ranking.
Toyota GR Corolla insurance at a glance
| Measure | Figure | Source |
| Average full coverage, 40-year-old driver | $3,346 a year ($279 a month) | Study A, Oct 2026 |
| Average liability-only (50/100/50) | $1,123 a year | Study A, Oct 2026 |
| Average for a 40-year-old with good credit | $2,627 a year | Study C |
| Average for an 18-year-old male driver | $10,895 a year | Study B, Mar 2026 |
| Cheapest company for Toyota owners | Travelers, $1,901 a year | Study B, Mar 2026 |
| Five-year insurance estimate, 2026 model | $14,240 | Study D |
| Five-year insurance estimate, 2025 model | $13,190 | Study C |
Each study prices its own sample driver, limits, and deductible, so compare figures within one study. The Sources section names each study in full.
10 insurers to quote: Toyota-wide and GR86 comparison data
No source in this review provides verified GR Corolla premiums by insurance company. The following ten insurers are quote candidates, not a cheapest-to-most-expensive GR Corolla ranking. To help shortlist insurers, we show two separate proxy datasets: Study B averages across Toyota models and Study A sample premiums for the different Toyota GR86 sports car. Neither dataset predicts what a GR Corolla owner will pay. Do not rank one company against another across the two studies.
Insurer quote shortlist: Toyota-wide and GR86 sample premiums (not GR Corolla quotes)
| Insurer | Study B, Toyota average | Study A, 2025 GR86 |
| Travelers | $1,901 | $2,631 |
| USAA* | $1,990 | $1,903 |
| GEICO | $2,241 | $2,669 |
| State Farm | $2,346 | $2,624 |
| Progressive | $2,474 | $3,426 |
| Nationwide | $2,501 | $3,054 |
| Erie | — | $2,000 |
| American Family | — | $2,956 |
| Auto-Owners | — | $3,226 |
| Allstate | $3,540 | $4,154 |
Full coverage. Study B: average across Toyota models, March 2026. Study A: 2025 GR86, 40-year-old driver, 100/300/100 with a $500 deductible, October 2026; Erie, American Family, and Auto-Owners come from its broader company list. Neither is a GR Corolla-specific price. *USAA sells only to military families.
1. Travelers
Travelers has the lowest Toyota-wide average in Study B, at $1,901 annually. Its GR86 premium is also competitive in Study A, but these do not establish that Travelers is cheapest for a GR Corolla. Consider including it among several quotes for the exact VIN.
2. USAA
USAA averages $1,990 a year for Toyota owners in Study B and has the lowest GR86 price in Study A, $1,903. Only military members, veterans, and their families can buy it.
3. GEICO
GEICO averages $2,241 a year for Toyota owners in Study B and charges $2,669 for a GR86 in Study A, close to the leaders in both.
4. State Farm
State Farm averages $2,346 a year in Study B and is the cheapest national company for a GR86 in Study A, at $2,624.
5. Progressive
Progressive averages $2,474 a year for Toyota owners in Study B, though it charges more for a GR86 in Study A, at $3,426.
6. Nationwide
Nationwide averages $2,501 a year in Study B and charges $3,054 for a GR86 in Study A. It also placed second in J.D. Power’s October 2026 claims study.
7. Erie
Erie charges just $2,000 a year for a GR86 in Study A’s company list, one of the lowest prices there, and it leads three regions in J.D. Power’s 2026 satisfaction study. It sells in a limited number of states.
8. American Family
American Family charges $2,956 a year for a GR86 in Study A’s list, and it has the lowest complaint index among the companies we compared.
9. Auto-Owners
Auto-Owners charges $3,226 a year for a GR86 in Study A’s list and gave military members a lower price than civilians in Study B.
10. Allstate
Allstate averages $3,540 a year for Toyota owners in Study B and $4,154 for a GR86 in Study A, so use its quote as a comparison point.
PRO TIP #1
Because no study prices the GR Corolla across every major insurer, get at least four quotes. Start with Travelers, GEICO, and State Farm, add Erie where it sells, and include USAA if you qualify.
GR Corolla insurers compared on service
A crash in a performance car can bring a large repair bill, so a company’s claims record matters. We compared J.D. Power’s 2026 satisfaction scores, AM Best financial strength ratings, and NAIC complaint indexes, where 1.00 is the expected number of complaints for a company’s size. For more context, see insurer customer-service and claims experience.
Service ratings for GR Corolla insurers
| Insurer | J.D. Power 2026 (regional range) | AM Best rating | NAIC complaint index |
| Travelers | 584 to 657 | A++ | 0.52 |
| USAA* | 707 to 763 | A++ | 1.18 |
| GEICO | 631 to 668 | A++ | 0.69 |
| State Farm | 632 to 669 | A+ | 0.79 |
| Progressive | 604 to 645 | A+ | 0.71 |
| Nationwide | 612 to 685 | A | 0.63 |
| Erie | 652 to 704 | A | 0.89 |
| American Family | 632 to 649 | A | 0.33 |
| Allstate | 612 to 660 | A+ | 1.10 |
J.D. Power figures are regional satisfaction scores, not GR Corolla claim handling ratings. These regional results should not be compared as one national ranking. AM Best financial-strength ratings shown for State Farm (A+) and Erie (A) reflect later AM Best actions in November and September 2025, respectively. Other ratings and national NAIC indexes are from the dated studies listed below and should be checked for updates. USAA has restricted eligibility and is not rank-eligible in the J.D. Power study.
Toyota-wide pricing reference: Travelers
Travelers has a competitive Toyota-wide sample average in Study B and an A++ AM Best rating. Neither establishes the best overall value for a GR Corolla without model-specific quotes.
Quote option for eligible military families: USAA
USAA scored 707 to 763 across J.D. Power’s regions, the best in each, and has the lowest GR86 price in Study A.
Regional quote option: Erie
Erie scored 652 to 704 in J.D. Power’s regional rankings and charges $2,000 a year for a GR86 in Study A’s company list.
Best claims experience: Amica and Nationwide
Amica ranked first in J.D. Power’s October 2026 claims study with 775 points, and Nationwide second with 743, against an average of 700.
Lowest reported national complaint index among these entries: American Family
American Family has the lowest national NAIC complaint index shown in this table, 0.33. The figure is not a GR Corolla-specific claims or satisfaction measure.
PRO TIP #2
Ask each insurer whether it pays for original Toyota parts on a GR Corolla. The GR model uses its own engine, drivetrain, and styling parts, so get the parts policy in writing.
Which insurer could be cheapest for your GR Corolla?
There is no verified cheapest insurer for a GR Corolla in the sources reviewed. As a general Toyota-wide reference, Study B reports $1,901 for Travelers, $1,990 for eligible USAA customers, and $2,241 for GEICO. These are NOT GR Corolla premiums. Each applicant needs quotes for their own GR Corolla VIN, address, drivers and coverage.
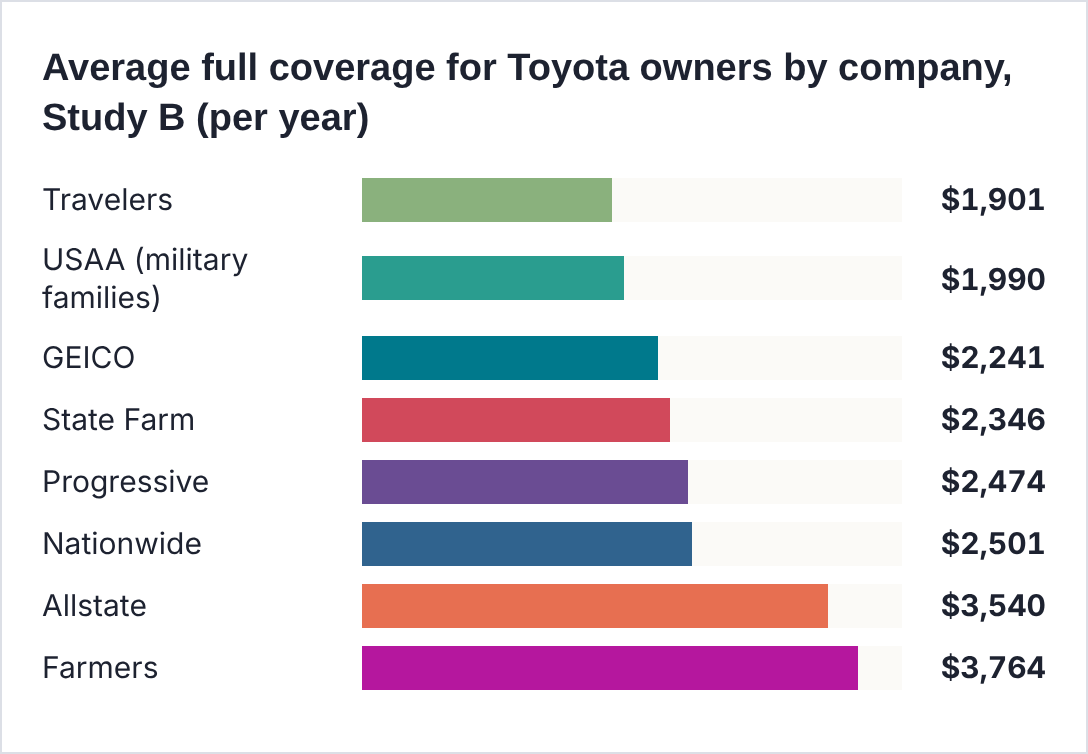
Average across Toyota models, not a GR Corolla-specific figure. Source: Study B, Toyota car insurance cost, March 23, 2026.
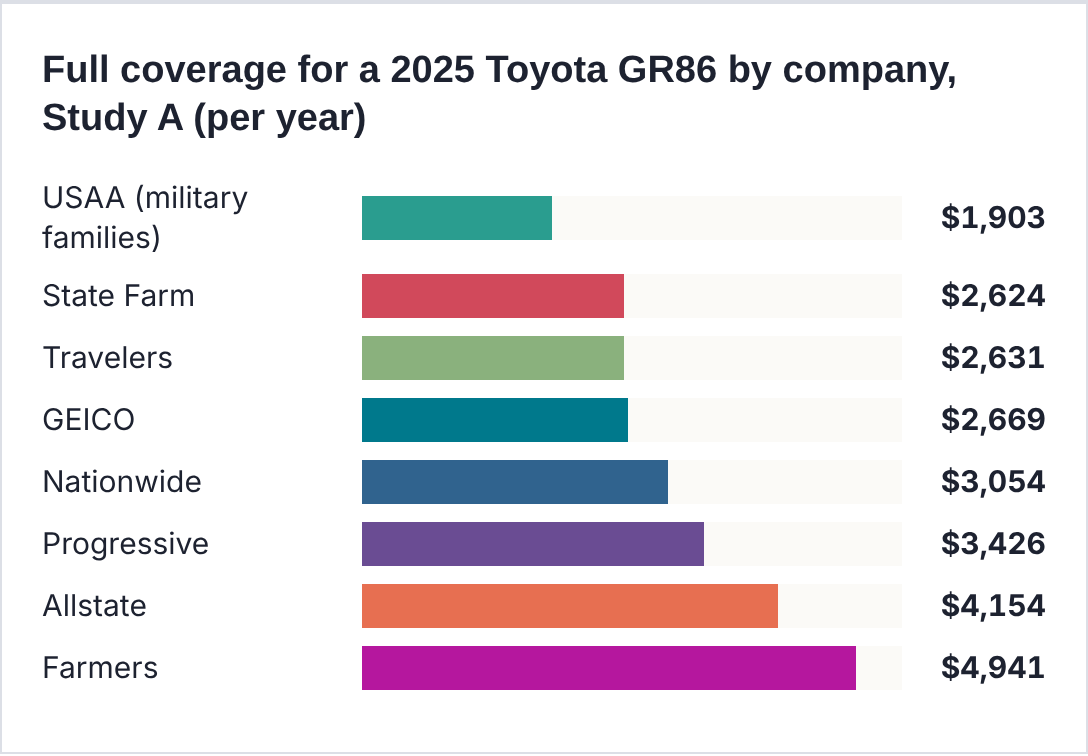
40-year-old driver, 100/300/100 with a $500 deductible. Source: Study A, Toyota GR86 car insurance, October 26, 2026.
The GR86 data shows how performance models can reshuffle the rankings. Progressive is a mid-pack choice for Toyota owners in general but costs $802 more than State Farm for a GR86 in Study A, so quote it rather than assume.
How to get your lowest GR Corolla quote
- Note your model year, trim, and transmission, and whether the car has any modifications.
- List every driver in the household and their records.
- Quote Travelers, GEICO, State Farm, and Nationwide, plus Erie where it sells and USAA if you qualify. See our guide to how to request and compare online car insurance quotes.
- Compare the same coverage with a $500 deductible and with a $1,000 deductible.
- Ask about telematics, multi-car, and bundle discounts. See our guide to car insurance discounts and eligibility.
How we built this list
We assembled GR Corolla sample averages, Toyota-wide insurer averages and separate GR86 insurer estimates from four published sources. Because no source supplies GR Corolla prices insurer by insurer, the comparison table is a shopping shortlist, not a data-backed insurer ranking for this model. Studies A through D are identified in the Sources section.
Toyota Auto Insurance
Toyota Insurance Management Solutions sells Toyota Auto Insurance, with claims support from Toggle, a Farmers company. Its last announced expansion, in 2023, reached 12 states, including Arizona, California, Colorado, Georgia, Illinois, Ohio, and Texas, and it can cover other brands in your household. Include it in your comparison if it is available where you live.
GR Corolla vs. other Toyotas
In Study A, the GR Corolla costs $3,346 a year to insure for a 40-year-old, $587 more than a regular Corolla and $457 more than a Camry. It is the cheapest of Toyota’s three GR models, $159 below the GR86 and $218 below the GR Supra.
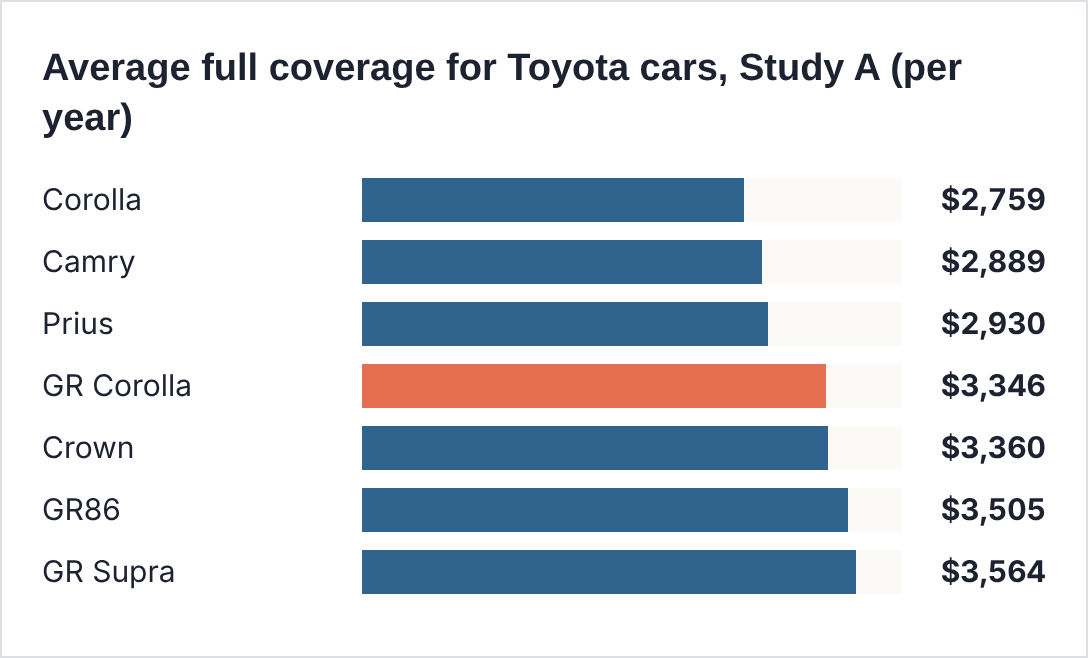
40-year-old driver, clean record, 100/300/100 with a $500 deductible. Source: Study A, Toyota insurance, October 26, 2026.
Study C tells a different story. Its estimate for a 40-year-old with good credit is $2,627 a year for the GR Corolla, slightly less than its $2,642 figure for a regular Corolla. The two studies use different methods, which is a good reminder to get real quotes.
Why the GR Corolla usually costs more to insure
- Performance. Its 300-horsepower turbo engine and all-wheel drive put it in a different class from a standard Corolla.
- Price. A 2026 GR Corolla costs $41,115 to $47,160 with destination, so collision and comprehensive coverage protect more value.
- Specialized parts. The turbocharged three-cylinder and all-wheel-drive system are not shared with the regular Corolla.
- Young drivers. Study B puts an 18-year-old male at $10,895 a year, $1,834 more than for a regular Corolla.
Liability-only coverage on a GR Corolla
Liability-only coverage pays for injuries and damage you cause to others, but nothing for your own car. Study A prices 50/100/50 liability on a GR Corolla at $1,123 a year, about $94 a month, compared with $3,346 for full coverage. For more context, see liability, collision and comprehensive coverage.
Liability-only vs. full coverage for Toyota cars, Study A (per year)
| Model | Liability only | Full coverage | Sample premium gap as % of full coverage |
| Corolla | $1,186 | $2,759 | 57% |
| Camry | $1,170 | $2,889 | 60% |
| GR Corolla | $1,123 | $3,346 | 66% |
| GR86 | $1,148 | $3,505 | 67% |
| GR Supra | $1,046 | $3,564 | 71% |
Study A, October 26, 2026, 40-year-old clean-record sample. Liability-only uses 50/100/50 limits; full coverage includes 100/300/100 liability plus collision and comprehensive with $500 deductibles. The percentage is (full-coverage sample premium minus liability-only sample premium) divided by the full-coverage premium. Because liability limits differ, it must NOT be interpreted as the share paid solely for collision and comprehensive.
The GR Corolla liability-only sample is slightly below the regular Corolla in this dataset. The difference between its two quoted packages is $2,223 per year (about 66% of the full-coverage price), but the packages also have different liability limits. The exact incremental cost of collision and comprehensive cannot be isolated from these figures.
Should you consider liability-only?
The GR Corolla started with the 2023 model year. Study D estimates a $31,100 resale value for a sampled 2024 car after a reported 11% decline; real values vary by condition and trim. Collision and comprehensive may be sensible when the owner cannot absorb the car’s loss, and lenders commonly require both. Request the individual coverage costs and weigh them against the car’s current value and your deductible.
PRO TIP #3
Ask for separate collision and comprehensive premium components before changing coverage. Comprehensive typically addresses covered theft, vandalism, fire and weather events, subject to exclusions and deductibles; neither its price nor suitability can be assumed from the combined full-coverage premium.
Full coverage prices for a GR Corolla
Full coverage combines liability, collision, and comprehensive. The studies below price different drivers, so the figures range from $2,627 to $3,346 a year.
GR Corolla full coverage by study
| Study | Full coverage | Sample driver and model |
| Study A (Oct 2026) | $3,346 a year | 40-year-old, 100/300/100, $500 deductible |
| Study B (Mar 2026) | $3,346 a year | 40-year-old male, 100/300/100 |
| Study D, 2025 and 2026 models | $2,848 a year | Five-year estimate of $14,240, divided by five |
| Study C, 2025 model | $2,638 a year | Five-year estimate of $13,190, divided by five |
| Study C | $2,627 a year | 40-year-old, good credit, about 13,000 miles a year |
Per-year figures from five-year totals are our division. Sources: Studies A through D.
Five-year GR Corolla costs
Insurance is one of the biggest costs of GR Corolla ownership. Study D’s five-year estimate for a 2026 model puts insurance at $14,240, more than its $9,085 for fuel and close to its $16,773 for depreciation.
Study D: five-year cost estimates for the GR Corolla
| Cost | 2025 model | 2026 model |
| Insurance | $14,240 | $14,240 |
| Fuel | $9,085 | $9,085 |
| Depreciation | $18,814 | $16,773 |
| Total cost to own | $59,232 | $57,697 |
Source: Study D, 2025 and 2026 Toyota GR Corolla cost to own.
Study C’s five-year estimate for a 2025 model is lower overall, at $45,889, but insurance still makes up 29% of the total at $13,190, nearly as much as its $14,474 depreciation figure. In both estimates, insurance is one of the two highest costs of owning a GR Corolla.
GR Corolla trims and transmissions
Toyota lists two U.S. 2026 GR Corolla grades: GR Corolla and GR Corolla Premium Plus. No study cited here compares insurance premiums by trim, so the $6,045 difference in sticker price must not be treated as a measured collision or comprehensive premium difference.
2026 Toyota GR Corolla prices by trim
| Trim | Price with destination | Notes |
| GR Corolla | $41,115 | 300-hp turbo three-cylinder, all-wheel drive, six-speed manual standard |
| Premium Plus | $47,160 | Top trim with added equipment |
| Eight-speed automatic | $2,000 extra | Available on both trims |
Prices as of September 2025, including a $1,195 destination fee, from the vehicle sources listed in Sources.
Base GR Corolla
The base trim has the lower purchase price and the same 300-hp engine and all-wheel-drive system. However, no source reviewed establishes which trim has the lower insurance premium; get quotes on both VINs before assuming a saving.
Premium Plus
The Premium Plus has a $6,045 higher MSRP in the cited 2026 comparison and additional equipment. The effect on insurance is not quantified here; insurers consider repairability, claims, and model coding as well as value.
Manual or automatic
The six-speed manual is standard, and the eight-speed automatic adds $2,000. The EPA rates the manual at 24 mpg combined and the automatic at 22 mpg. No study separates insurance prices by transmission, so tell your insurer which one you have.
What changed for 2026
Toyota added more structural adhesive to the body for better rigidity and a secondary air intake duct to manage underhood temperatures. The exterior and safety equipment carried over from 2025.
PRO TIP #4
Quote the exact trim and transmission before you sign. The Premium Plus automatic lists for $8,045 more than the base manual in the referenced MSRP schedule, but the resulting insurance difference has not been measured.
The 2026 GRMN Corolla: limited-run model
Manufacturer confirmation: Toyota’s July 2026 GRMN announcement.
Toyota announced the 2026 GRMN Corolla on July 29, 2026. Production is limited to 730 units worldwide, with a U.S. starting MSRP of $64,360 before delivery and other charges. The limited-run car includes a carbon-fiber hood, adjustable rear wing, dedicated suspension, Michelin Pilot Sport Cup 2 tires, specialized seating, and increased torque. The announcement describes it as a 2026 model, not a 2026 GRMN.
Owners of an unusually valuable limited-production GRMN may wish to compare agreed-value coverage with an ordinary actual-cash-value policy, subject to eligibility, mileage, usage and track exclusions. We found no verified insurer-by-insurer GRMN premiums or 2027 GR Corolla rates; request a VIN-specific quote instead.
Safety, recalls, and theft
Verify open safety recalls at NHTSA’s official VIN recall lookup. The 2025 instrument-panel recall affects certain 2023–2025 GR Corollas, not every vehicle.
We did not find GR Corolla-specific IIHS crash ratings in the sources we reviewed, so get a quote by VIN rather than relying on crash scores. Toyota did not add new active safety features for 2026, according to coverage of the update.
Recalls to check
- September 2025: some GR Corollas were included in a recall because a software error at startup could keep the instrument panel from showing the speed, brake warning, and tire pressure lights. Dealers update the software free of charge, often over the air.
- July 2024: Some GR Corollas with Gulf States Toyota accessories received a corrected load capacity label by mail.
A recall does not automatically establish a specific insurance surcharge, and any premium effect cannot be inferred from a campaign notice. Confirm whether your particular VIN is included and whether a remedy is complete using the official NHTSA recall lookup.
Protecting a desirable car
If your GR Corolla is parked outside or in public lots, theft and vandalism are risks worth covering. Comprehensive coverage pays for theft and vandalism, so keep it, park in a garage when you can, and ask whether your insurer gives a discount for anti-theft devices.
Modifications and track days
If you modify your GR Corolla or drive it at enthusiast events, both choices can affect your insurance:
- Declare every modification. Wheels, exhausts, tunes, and suspension parts may not be covered unless your insurer knows about them, and policies differ on how much add-on equipment they cover.
- Check track-day exclusions. Many personal auto policies exclude racing and timed events, so consider single-event track insurance before an autocross or track day.
- Keep receipts. Records of what you paid for upgrades help support a claim after a theft or total loss.
GR Corolla insurance by model year
The GR Corolla has been sold since the 2023 model year, and none of the studies we found publish insurance prices for each year. Value is the best guide. Study D reports that a 2024 GR Corolla declined by $3,901 (about 11%) in its sample valuation, which is not a guarantee of resale value for every car, so older cars are still worth a lot to insure.
2024 GR Corolla value over time, Study D
| Point in time | Private party resale value | Trade-in value |
| 2024 (new) | $35,001 | $32,802 |
| 2025 | $32,248 | $30,093 |
| Now | $31,100 | $27,600 |
Values for a car in good condition, national averages. Source: Study D, 2024 Toyota GR Corolla values.
Because the GR Corolla holds its value well, collision and comprehensive coverage still protect a lot of money on a used one. Quote the exact car by VIN to see how much a 2023 or 2024 saves over a 2026.
PRO TIP #5
Buying a used GR Corolla? Ask for receipts on any modifications, confirm open recalls are fixed, and tell your insurer about any changes before you drive it home.
GR Corolla vs. other performance cars
The national data we found compares the GR Corolla most directly with Toyota’s other GR models. In both Study A and Study B, it is the cheapest of the three to insure.
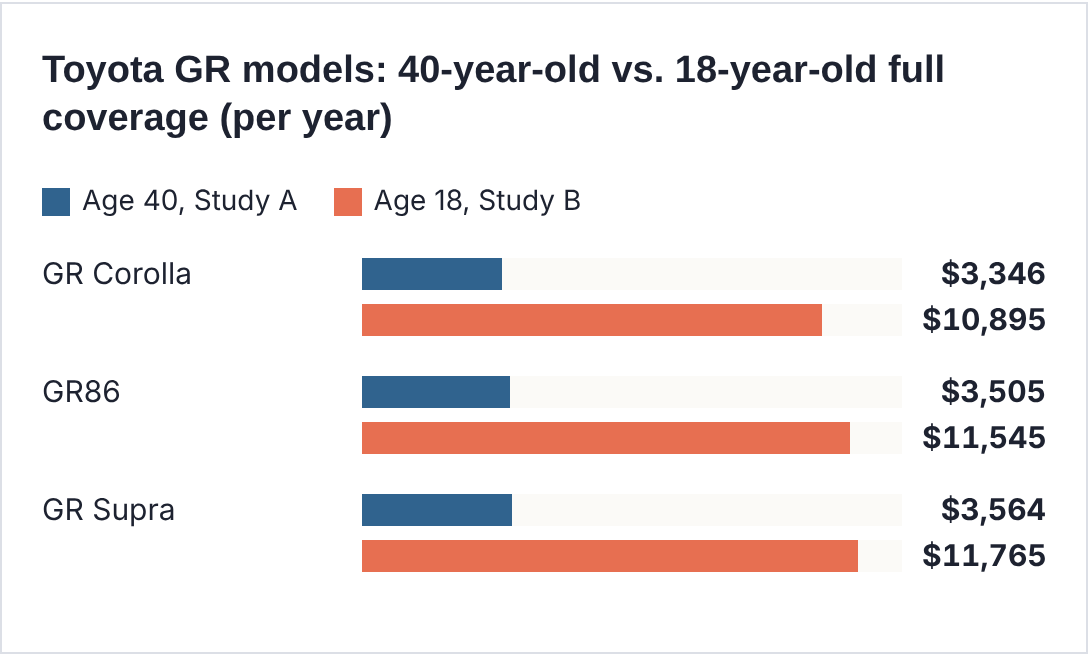
Study A: 40-year-old, 100/300/100, $500 deductible, October 2026. Study B: 18-year-old male, 100/300/100, March 2026.
For an 18-year-old, the GR Corolla costs $650 a year less than a GR86 and $870 less than a GR Supra in Study B. Study C ranks the GR86 slightly cheaper than the GR Corolla, at $2,389 against $2,627, so the order can change by study.
GR Corolla vs. rival hot hatches
None of the studies we used published prices for the GR Corolla’s closest rivals, such as the Honda Civic Type R, Volkswagen Golf R, or Subaru WRX, on the same basis. If you are cross-shopping, quote each car with the same company, limits, and deductible.
GR Corolla insurance by state
Your state can change your premium by more than $2,500 a year. Among the 15 states in Study C, a 40-year-old with a clean record and good credit pays from $1,216 a year in Hawaii to $3,788 in Connecticut.
GR Corolla insurance in 15 states, Study C (per year)
| State | Good driver | Recent at-fault accident | Poor credit |
| Alabama | $2,783 | $4,042 | $5,145 |
| Alaska | $2,302 | $3,191 | $3,102 |
| Arizona | $2,602 | $3,762 | $5,543 |
| Arkansas | $2,853 | $4,483 | $4,936 |
| California | $3,177 | $5,618 | $3,177 |
| Colorado | $2,965 | $4,149 | $5,264 |
| Connecticut | $3,788 | $5,874 | $7,457 |
| Delaware | $3,136 | $4,179 | $5,368 |
| Florida | $3,734 | $5,165 | $6,731 |
| Georgia | $3,044 | $4,551 | $4,589 |
| Hawaii | $1,216 | $1,651 | $1,216 |
| Idaho | $2,112 | $2,800 | $3,404 |
| Illinois | $2,211 | $3,342 | $3,811 |
| Indiana | $2,272 | $3,473 | $3,897 |
| Iowa | $1,799 | $2,467 | $2,902 |
40-year-old driver, full coverage, good credit unless noted. California and Hawaii do not allow credit-based pricing, so their good-driver and poor-credit figures match. Source: Study C, Toyota GR Corolla insurance.
An at-fault accident adds the most in California, $2,441 a year. Poor credit more than doubles the Arizona price, from $2,602 to $5,543.
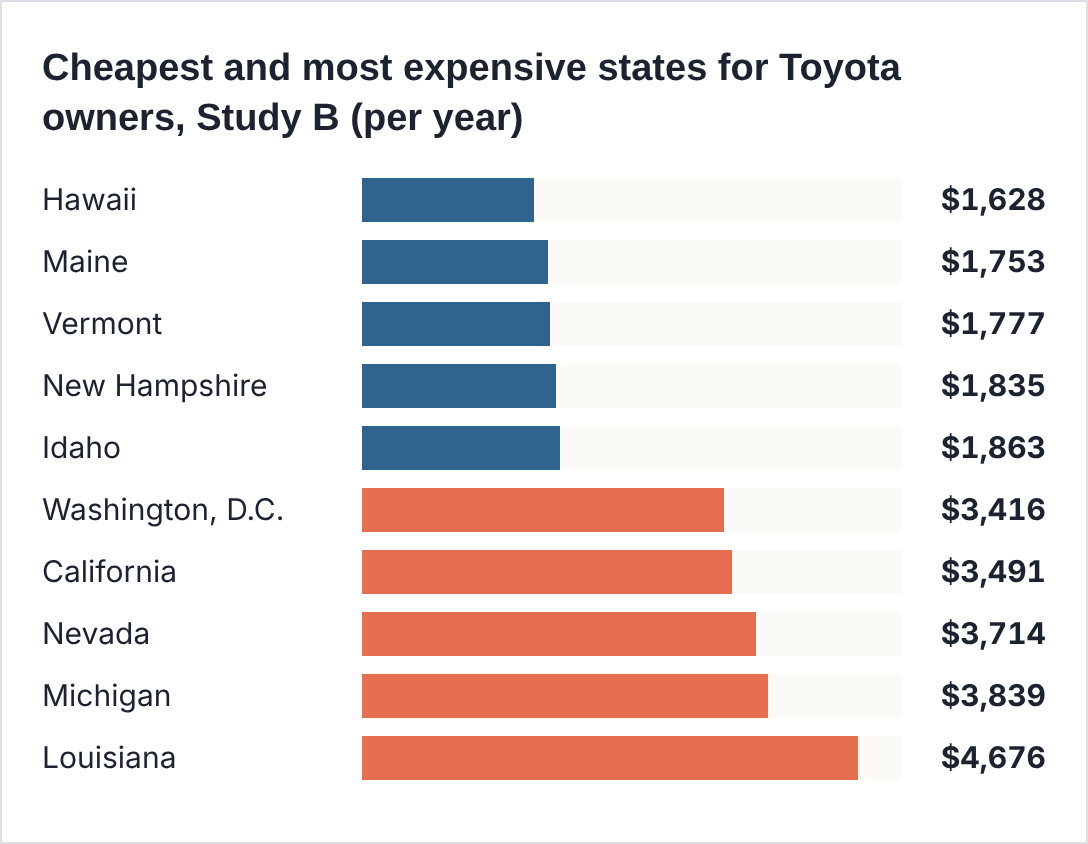
Average across Toyota models, not a GR Corolla-specific figure. Source: Study B, Toyota car insurance cost, March 23, 2026.
Study B’s statewide Toyota averages follow a similar pattern, from $1,628 in Hawaii to $4,676 in Louisiana.
GR Corolla insurance in Florida
Florida is one of the costlier states in Study C, at $3,734 a year for a good driver, $1,107 above the 40-year-old national figure. An accident raises that to $5,165, and poor credit to $6,731. Study B’s Toyota average for Florida is $3,299.
PRO TIP #6
Moving with your GR Corolla? Get quotes at the new address before you register the car, because the cheapest company can change from one state to the next.
What your age, record, and credit do to a GR Corolla rate
Study C prices the same GR Corolla for drivers with different profiles. A 40-year-old with a clean record and good credit pays $2,627 a year. One at-fault accident raises that to $3,857, and poor credit to $4,512, about 72% more.
GR Corolla insurance by age and driver profile, Study C (per year)
| Age | Good driver and credit | Recent at-fault accident | Poor credit |
| 18 | $8,292 | $12,176 | $14,244 |
| 25 | $3,743 | $5,497 | $6,431 |
| 30 | $2,916 | $4,282 | $5,009 |
| 40 | $2,627 | $3,857 | $4,512 |
| 55 | $2,344 | $3,442 | $4,027 |
Full coverage on a new GR Corolla, about 13,000 miles a year, single-vehicle policy. Source: Study C, Toyota GR Corolla insurance.
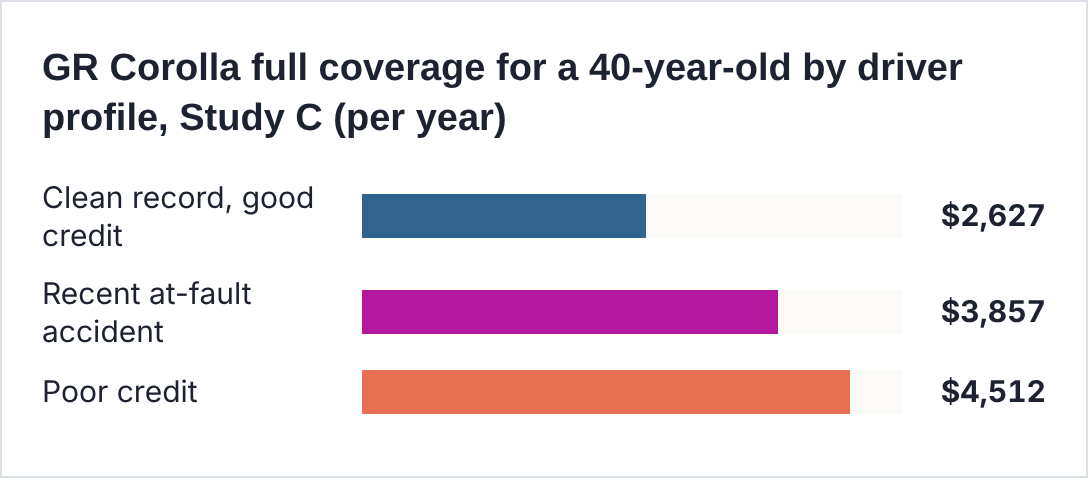
Source: Study C, Toyota GR Corolla insurance.
A clean 18-year-old pays $8,292 a year in Study C, more than three times the 40-year-old price. That falls to $3,743 at 25 and $2,344 at 55. Where credit can be used, poor credit adds $1,885 a year for a 40-year-old, more than the $1,230 added by an at-fault accident.
Rebuilding after an accident
- Compare quotes at renewal, since insurers treat accidents differently.
- Ask about accident forgiveness for future claims.
- Take a defensive driving course if your state offers a discount for it.
- Use a telematics program to show safer habits.
Coverage choices for a hot hatch
A GR Corolla owner has different needs from a commuter in a base Corolla. Consider these options:
- Liability limits of 100/300/100 or higher, the level most studies in this guide use, so a serious crash does not reach your savings.
- Custom parts and equipment coverage for wheels, exhausts, tunes, and suspension upgrades.
- Gap insurance on a new loan with a small down payment.
- Uninsured and underinsured motorist coverage for your own injuries.
- Rental reimbursement with a daily limit that covers a comparable car during repairs.
PRO TIP #7
If the GR Corolla is your fun car rather than your commuter, insure it on the same policy as your daily driver and report its lower annual mileage.
Insuring a financed or leased GR Corolla
If you finance or lease your GR Corolla, the contract shapes your coverage. Lenders and leasing companies require collision and comprehensive coverage, and some cap the deductible you can choose, so check your contract before raising it. Some leases also set minimum liability limits above your state’s requirement.
Gap coverage is worth a look in the first years of a loan with a small down payment, even though the GR Corolla has held its value well so far. Some lenders include gap protection in the contract, so check before buying it twice.
Five GR Corolla insurance mistakes
- Getting one quote. Study B’s Toyota averages range from $1,901 to $3,764 a year across eight companies.
- Not declaring upgrades. A tune or new wheels left off the policy may not be covered after a loss.
- Assuming track days are covered. Many personal policies exclude racing and timed events.
- Letting credit slide. Poor credit adds $1,885 a year for a 40-year-old in Study C.
- Putting a teen in the GR Corolla by default. Study B prices an 18-year-old at $10,895 a year as its main driver.
10 discounts GR Corolla owners can request
Every discount below comes from the insurer’s own website. Availability varies by state, and the amounts are maximums or averages, not guarantees.
1. Multiple cars
GEICO offers up to 25% for insuring more than one vehicle, and Progressive says multi-car customers save 12% on average.
2. Home and auto bundle
Progressive says bundling customers save more than $1,000 a year on average; Nationwide cites $1,032, and The Hartford $963. Farmers lists 10% or more.
3. Telematics
State Farm’s Drive Safe & Save and Liberty Mutual’s RightTrack offer up to 30%. USAA’s SafePilot gives 10% for joining and up to 30% at renewal; Nationwide’s SmartRide 10%, and Progressive says Snapshot users save $328 a year on average.
4. New car
Travelers offers a discount for vehicles less than three years old in most states, though not in California.
5. Clean record
GEICO lists up to 22% for five years without an accident, and Travelers has a safe driver discount for households without recent accidents or violations.
6. Good student
State Farm offers up to 25% for students with good grades, GEICO up to 15%, and Progressive about 5%. Travelers asks for a B average or better.
7. Driver training
Travelers offers a discount for young drivers who complete an approved driver education course.
8. Safety equipment
State Farm offers up to 40% off certain medical coverages for factory airbags, and GEICO lists 5% for anti-lock brakes.
9. Online and early quotes
Progressive offers about 7% for an online quote and about 10% for signing online; The Hartford lists 8% for an online quote, and Travelers rewards quoting before your current policy ends.
10. Military and AARP
GEICO offers up to 15% for military members, and The Hartford takes 10% off for AARP members. The senior and military sections below have more.
PRO TIP #8
Ask each company to list every discount on your quote. A driver with a clean record, a bundle, and a telematics program can qualify for three discounts at once.
GR Corolla insurance for teens and young drivers
A 300-horsepower hatchback is a costly car for a new driver to insure. Study B prices an 18-year-old male as the main driver at $10,895 a year, about 3.3 times the 40-year-old price. In Study C, a clean 18-year-old with good credit pays $8,292, and one at-fault accident raises that by $3,884, to $12,176.
No cited study provides GR Corolla premiums for each age and each insurer. The following sections combine model-specific estimates for some driver ages with separate national family-policy averages that do not use a GR Corolla as the test vehicle.
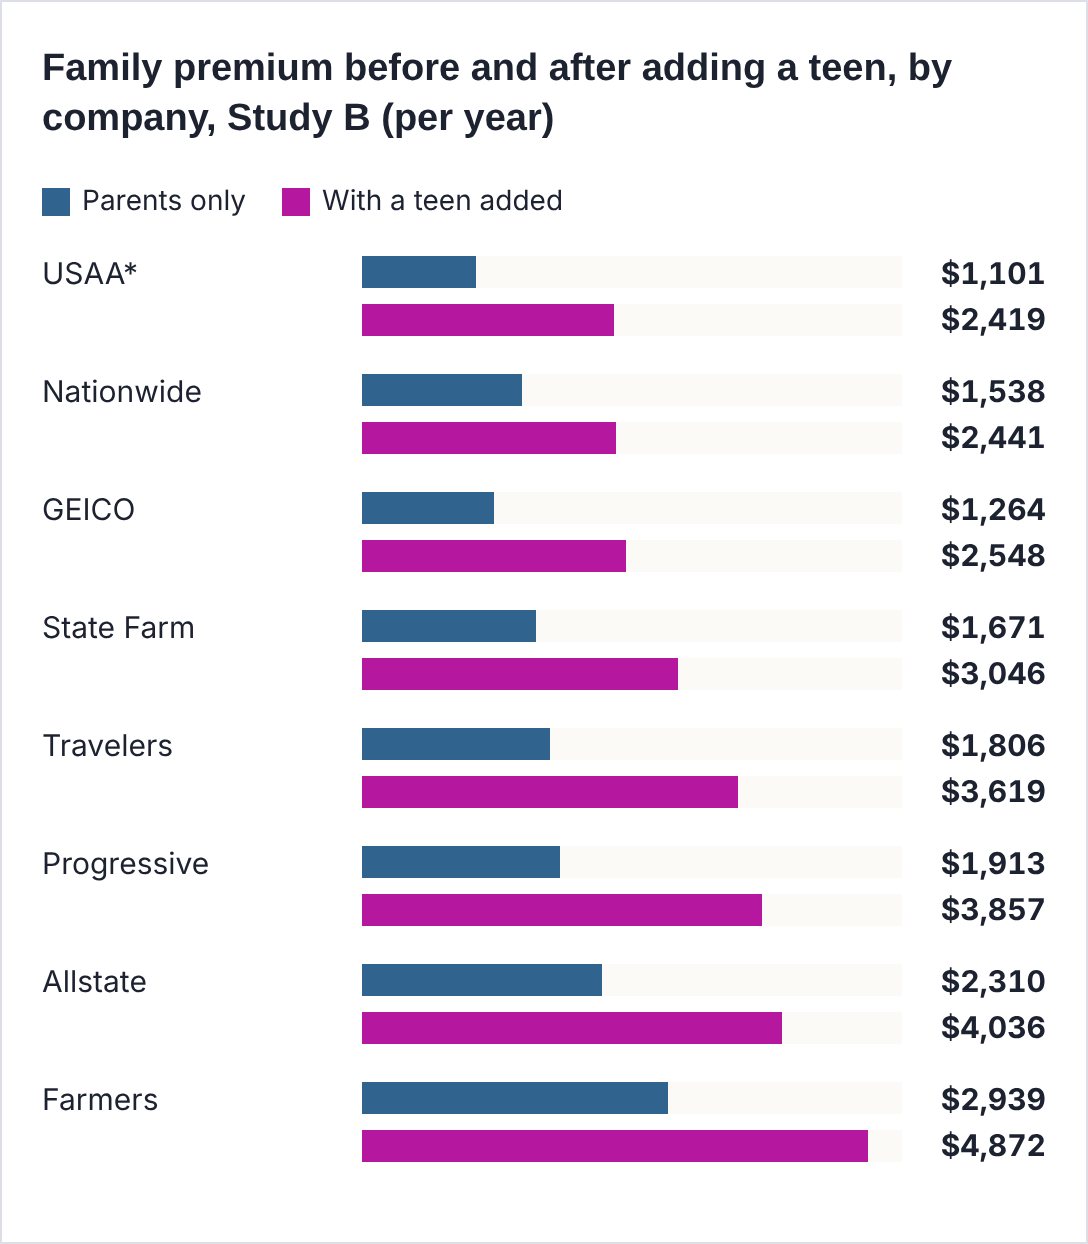
Full-coverage family premium; national data, no specific test vehicle. *USAA sells only to military families. Source: Study B.
In Study B’s national household example—not a GR Corolla-specific quote—Nationwide showed the smallest additional sampled premium, $903 annually, and the GEICO family total was $2,548. These figures do not establish either insurer as cheapest for a teenager who drives a GR Corolla.
Cheapest Toyota GR Corolla insurance for a 16-year-old
Study B puts the cost of adding a 16-year-old to a parent’s policy at about $4,050 a year, the highest of any teen age. On a separate policy, GEICO was the cheapest national company for a 16-year-old in Study A’s teen data, at $8,436 a year.
Cheapest Toyota GR Corolla insurance for a 17-year-old
At 17, the added cost falls to about $3,740 a year in Study B, and GEICO is again cheapest on a separate policy in Study A, at $6,937.
Cheapest Toyota GR Corolla insurance for an 18-year-old
Adding an 18-year-old costs about $3,478 a year in Study B, roughly a third of the $10,895 GR Corolla price for an 18-year-old main driver. Travelers was cheapest for an 18-year-old with a separate policy in Study A, at $5,566.
Cheapest Toyota GR Corolla insurance for a 19-year-old
By 19, the added cost is about $3,105 a year in Study B, and Travelers stays cheapest on a separate policy in Study A, at $4,465.
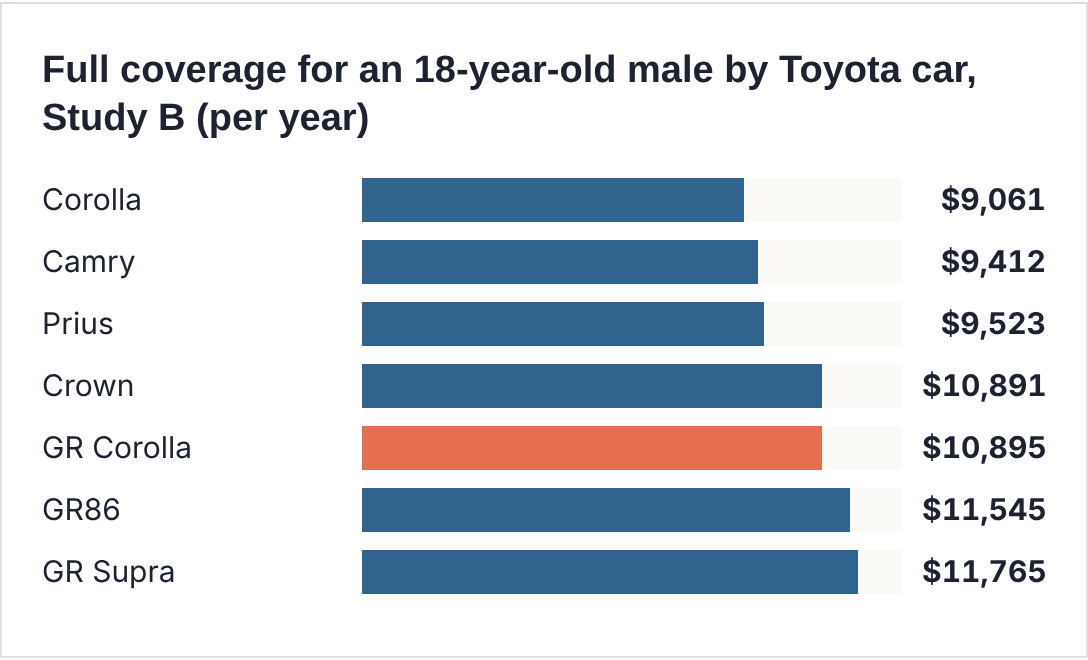
100/300/100 full coverage. Source: Study B, Toyota car insurance cost, March 23, 2026.
A regular Corolla saves $1,834 a year over a GR Corolla for an 18-year-old in Study B, and a Camry saves $1,483. If a teen needs a car of their own, a standard Corolla is far cheaper to insure.
Lowering a young driver’s GR Corolla premium
- Compare a family policy and an eligible separate policy, and disclose all household drivers accurately.
- Tell the insurer which vehicles the teen actually drives; do not select a cheaper rating assignment that misstates their use.
- Claim good student discounts of up to 25% at State Farm or 15% at GEICO.
- Complete an approved driver education course, which Travelers rewards.
- Hold off on modifications, and requote each year until 25.
PRO TIP #9
Age brings the fastest savings. In Study C, a clean GR Corolla driver pays $8,292 at 18 but $3,743 at 25, less than half as much.
GR Corolla insurance for seniors
Older enthusiasts get the best GR Corolla prices. In Study C, a 55-year-old with a clean record and good credit pays $2,344 a year, $283 less than a 40-year-old. Study B’s national senior figures, which use no specific test vehicle, rise gradually from $2,353 a year at 65 to $2,498 at 70 and $2,742 at 75. For more context, see car insurance for mature drivers.
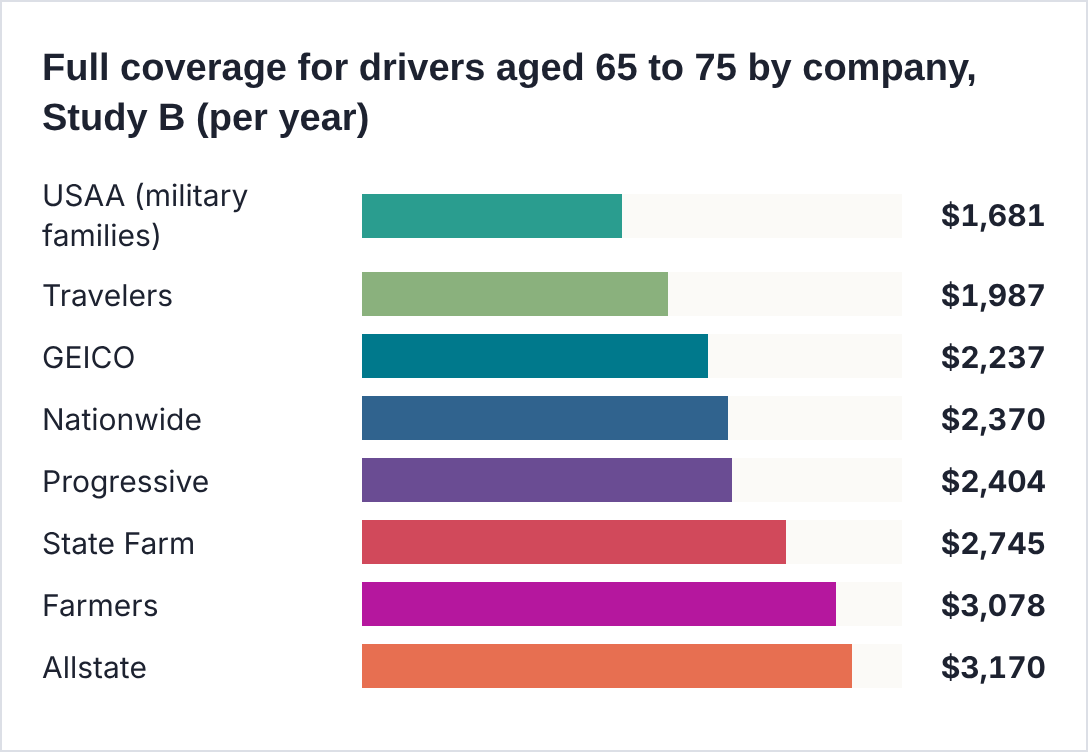
100/300/100 with a $500 deductible; no test vehicle named. Source: Study B, car insurance for seniors, April 16, 2026.
Travelers has the lowest published figure among broadly eligible companies for the national senior driver sample in Study B, at $1,987 annually. That study did not test a GR Corolla.
Savings for mature drivers
- Complete a mature driver course. AARP says 33 states and Washington, D.C., require insurers to give a discount for one, and Kiplinger reports savings of up to 10%.
- Get a quote from The Hartford’s AARP program, which lists 10% for members, 5% for defensive driving, and up to 15% through its TrueLane app.
- Report reduced mileage if the GR Corolla is a weekend car.
- Keep receipts for any upgrades so they are covered at full value.
PRO TIP #10
Storing your GR Corolla for the winter? Ask whether you can drop collision while it is parked and keep comprehensive to protect against theft, fire, and flood.
Pay-per-mile for a weekend GR Corolla
A GR Corolla driven infrequently might benefit from a genuine per-mile policy or a conventional low-mileage discount. Availability, eligible vehicles, daily-mile caps and rates change by state and insurer. Check eligibility for a performance model before assuming a program such as Nationwide SmartMiles will be cheaper. For more context, see pay-per-mile insurance for low-mileage drivers.
Per-mile offers may combine a fixed base premium with a charge for each mile driven. Published illustrations are not binding quotes and may exclude fees or state-specific conditions. Compare a full year of estimated driving with a standard policy and confirm coverage while parked.
GR Corolla insurance for military families
USAA has the lowest GR86 price in Study A, $1,903 a year, and averages $1,990 for Toyota owners in Study B, making it the first quote for eligible families. It also earned the top J.D. Power score in every region in 2026.
Full coverage for military members vs. civilians, Study B (per year)
| Insurer | Military | Civilian | Military savings |
| USAA | $1,465 | $1,572 | $107 |
| Travelers | $1,818 | $2,103 | $285 |
| Auto-Owners | $1,908 | $2,051 | $143 |
| GEICO | $1,951 | $2,148 | $197 |
| Nationwide | $2,210 | $2,463 | $253 |
| Progressive | $2,382 | $2,675 | $293 |
| State Farm | $2,575 | $2,874 | $299 |
| Farmers | $2,676 | $3,085 | $409 |
| Allstate | $2,698 | $3,205 | $507 |
Full coverage; no test vehicle named. Savings are our subtraction. Source: Study B, best car insurance for military members, August 13, 2026.
Each insurer in Study B’s national sample showed lower average military-category premiums than the comparison civilian category. The groups may differ in characteristics; the difference does not prove a uniform military discount or predict the premium for an actual GR Corolla. Travelers’ sample categories differed by $285 annually.
Military discounts to ask about
- USAA advertises up to 60% off for a vehicle in storage, except in North Carolina and Virginia, and up to 15% off comprehensive coverage for a vehicle garaged on a base.
- GEICO offers up to 15% for active-duty, retired, Guard, and Reserve members and up to 25% during deployment.
- Armed Forces Insurance can arrange auto coverage for military families through partner insurers.
PRO TIP #11
Deploying? Store your GR Corolla with comprehensive-only coverage if your insurer allows it, and ask USAA about its storage discount.
The GR Corolla insurance playbook in five cartoon panels
Questions on the cheapest Toyota GR Corolla insurance
Who has the cheapest Toyota GR Corolla insurance?
No verified insurer-by-insurer GR Corolla comparison was found. Travelers leads the Toyota-wide sample in Study B, while USAA (restricted eligibility) and State Farm have competitive GR86 samples in Study A. These are only starting points for GR Corolla quotes.
How much is GR Corolla insurance per month?
Study A’s full-coverage average is $279 a month for a 40-year-old, and Study C’s works out to about $219 a month for a driver with good credit. Liability-only averages about $94 a month in Study A.
Is the GR Corolla more expensive to insure than a regular Corolla?
In Study A, yes, by $587 a year. Study C puts the two within $15 of each other, so get quotes on both if you are deciding.
Is the GR Corolla cheaper to insure than a GR86?
In Study A, yes, at $3,346 against $3,505. Study C has the GR86 slightly cheaper, at $2,389 against $2,627.
Does the automatic GR Corolla cost more to insure?
No study separates the two. The automatic adds $2,000 to the price, which may add a little to collision and comprehensive costs.
How much will insurance cost on a GRMN Corolla?
No study had published GRMN rates when we checked. Toyota announced the 2026 GRMN with a $64,360 starting U.S. MSRP before extra charges and 730 units worldwide. Compare standard and specialty policies by VIN if eligible.
Will my insurance cover an autocross or track day?
Often not. Many personal auto policies exclude racing and timed events, so ask in writing and consider single-event track insurance.
Has the GR Corolla been recalled?
Yes. It was included in a September 2025 recall for an instrument panel software error and a 2024 load label recall for some cars with Gulf States Toyota accessories. Check your VIN at nhtsa.gov.
Does the GR Corolla hold its value?
So far, yes. Study D reports that a 2024 GR Corolla lost $3,901, or 11%, of its value in two years, which keeps full coverage worthwhile on used cars.
Is liability-only coverage a good idea for a GR Corolla?
Rarely. Study A prices liability-only at $1,123 a year, but it pays nothing toward your own car, and even a 2024 model is worth about $31,100 in Study D.
Is GR Corolla insurance cheaper for military families?
Eligibility for USAA is restricted, and national sample averages for military households differ from civilian averages in Study B. There is no measured GR Corolla-specific military-versus-civilian premium comparison here; compare actual quotes.
What is the cheapest trim to insure?
No source reviewed verifies the cheapest GR Corolla trim to insure. The 2026 base trim starts at $41,115 including the stated delivery charge, versus $47,160 for Premium Plus manual; compare quotes by VIN.
Which state has the cheapest GR Corolla insurance?
Hawaii, among the 15 states in Study C, at $1,216 a year for a good driver, followed by Iowa at $1,799.
How much is GR Corolla insurance for an 18-year-old?
Study B puts an 18-year-old male as the main driver at $10,895 a year, and Study C’s clean 18-year-old pays $8,292. Adding a teen to a family policy usually costs much less.
Are 2027 GR Corolla insurance rates available?
Not yet. Toyota announced the 2026 GRMN Corolla, but no study had published 2027 GR Corolla insurance rates when we checked. Get a quote by VIN before you buy.
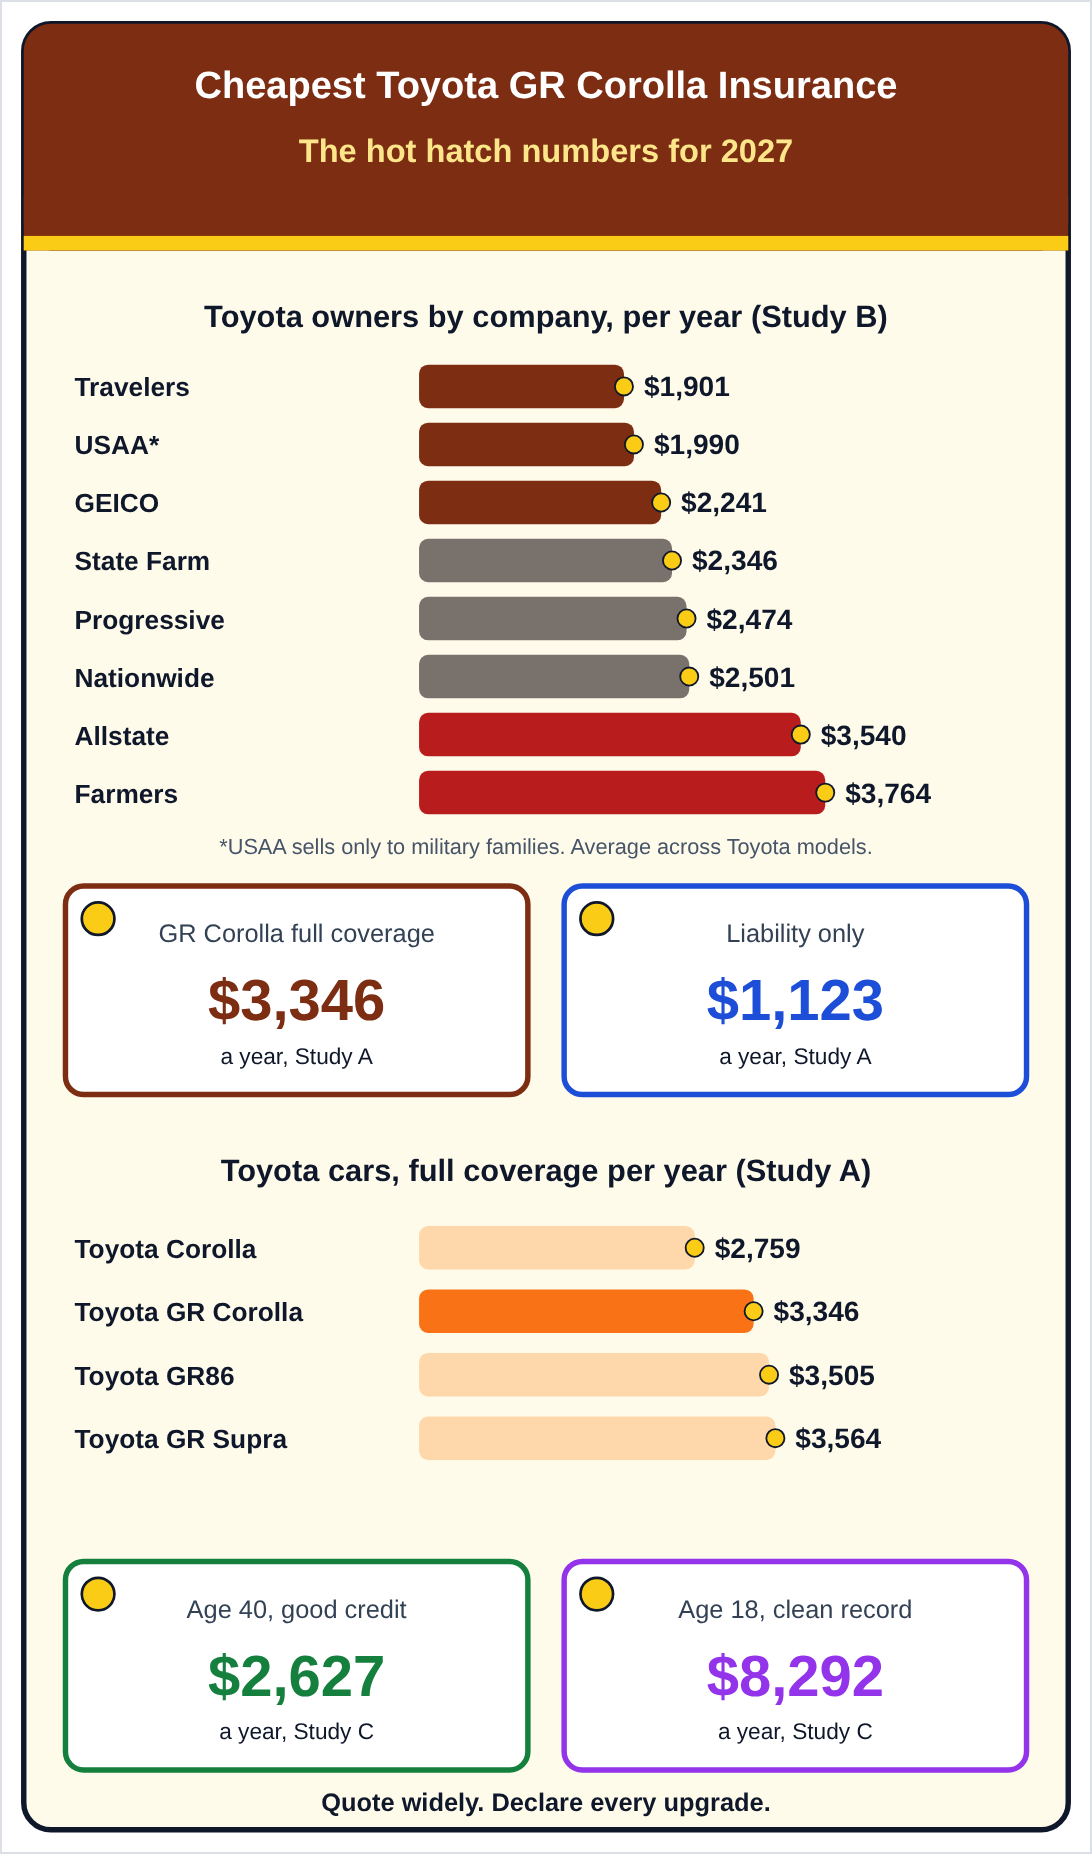
GR Corolla insurance in one picture.
The final word on the cheapest Toyota GR Corolla insurance
Study A reports a higher sample premium for the GR Corolla than for a regular Corolla; other studies differ in their assumptions and results. Its relatively high resale value can strengthen the case for collision and comprehensive coverage, but owners should compare the incremental premium, deductible and potential loss before deciding. Teen-driver samples are much more costly than mature-driver samples.
Because the cited sources do not report GR Corolla premiums by insurer, request several VIN-specific quotes with matched liability limits, deductibles and drivers. Travelers, GEICO, State Farm and eligible regional carriers are potential candidates, not documented winners. Declare modifications, check track-event exclusions and ask about multi-car and low-mileage discounts. For a limited-run GRMN, discuss valuation and eligibility before selecting a specialty policy.
Sources
- Study A: Insurance.com, Toyota insurance (October 26, 2026); Toyota GR86 car insurance (October 26, 2026); and teen car insurance costs (August 13, 2026).
- Study B: CarInsurance.com, Toyota car insurance cost (March 23, 2026); cost of adding a teen driver (August 4, 2026); car insurance for seniors (April 16, 2026); best car insurance for military members (August 13, 2026); top financially rated insurers (December 16, 2025); and insurers ranked by NAIC complaint data (August 13, 2026).
- Study C: CarEdge, Toyota GR Corolla insurance, Toyota GR Corolla ownership costs, and Toyota GR86 insurance.
- Study D: Kelley Blue Book, 2026 Toyota GR Corolla cost to own, 2025 Toyota GR Corolla cost to own, and 2024 Toyota GR Corolla values.
- Service ratings: J.D. Power 2026 U.S. Auto Insurance Study coverage (June 9, 2026); J.D. Power 2026 regional scores; Amica, J.D. Power 2026 results; and J.D. Power 2026 Auto Claims Satisfaction Study coverage (October 27, 2026).
- Insurer pages: Travelers discounts; Progressive discounts; GEICO discounts; GEICO military discounts; State Farm discounts; Nationwide discounts; Nationwide SmartMiles; Lemonade, pay-per-mile car insurance (June 25, 2026); Liberty Mutual RightTrack; Farmers discounts; USAA discounts; The Hartford AARP discounts; Armed Forces Insurance, auto; and Toyota, Toyota Auto Insurance.
- Vehicle and safety data: Cars.com, how much is the 2026 Toyota GR Corolla (September 25, 2025); TFLcar, Toyota GRMN Corolla pricing (July 30, 2026); ForCar, Toyota GR Corolla insurance cost; and Cars.com, Toyota GR Corolla recalls.
- Other sources: AARP, auto insurance discounts; and Kiplinger, ways seniors save on car insurance (September 3, 2026).
Disclaimer
This guide summarizes published GR Corolla sample estimates, Toyota-wide rates, separate GR86 prices, satisfaction studies, financial ratings and recall information. The company examples are proxy datasets—not GR Corolla insurer quotes and not a verified cheapest-company ranking. This is educational information, not insurance, legal or financial advice.
The price you pay will reflect your location, age, driving and claims history, credit where state law permits it, the drivers in your household, your mileage, your GR Corolla’s model year, trim, and transmission, any modifications, and the limits and deductible you choose. Coverage for aftermarket parts, track events, and agreed value differs between insurers, so get the terms in writing.
This publication is independent and has no affiliation with Toyota Motor North America, Inc., NHTSA, J.D. Power, AM Best, or any insurer mentioned, including Travelers, USAA, GEICO, State Farm, Progressive, Nationwide, Erie, American Family, Auto-Owners, Allstate, Farmers, Amica, Liberty Mutual, Lemonade, The Hartford, and Armed Forces Insurance. No insurer reviewed this article or paid for inclusion. The insurer names form an editorial shortlist based on related-vehicle datasets, not a model-specific GR Corolla price ranking.
Toyota, GR Corolla, GRMN, GR86, GR Supra, and other names mentioned are trademarks of their respective owners.