
The Best and Cheapest Mobile Home Insurance in North Carolina
Shopping for the best and cheapest mobile home insurance in North Carolina works differently than in most states, because every insurer starts from the same base rates set by the North Carolina Rate Bureau. The savings come from the discounts each company files, and those discounts can cut your bill by 5% to 30% or more.
North Carolina has about 525,544 mobile homes, the third most of any state, and they make up 10.4% of all housing. This guide explains how mobile home prices are set, what the April 2025 rate settlement means for your bill in 2026, and which 10 companies are most likely to be cheapest. It also covers coastal costs, the Beach Plan and FAIR Plan, lessons from Hurricane Helene, the best options for seniors, bundling with auto, and tips to save.
KEY TAKEAWAYS
- North Carolina mobile home rates rose 11% (broad MH-F form) or 8% (MH-C form) on September 1, 2025, with a second step in late summer 2026, and no new increase can be requested before September 1, 2027.
- NC Farm Bureau is our top pick for most owners, Assurant had the lowest sample quote in Study A at $969, and National General's filed credit of 5% to 30% for owners 50 and older makes it the best pick for seniors.
- Coastal mobile homes averaged about $1,735 a year for full coverage in 2024 state data, and the North Carolina Department of Insurance says both mobile home programs include flood coverage.
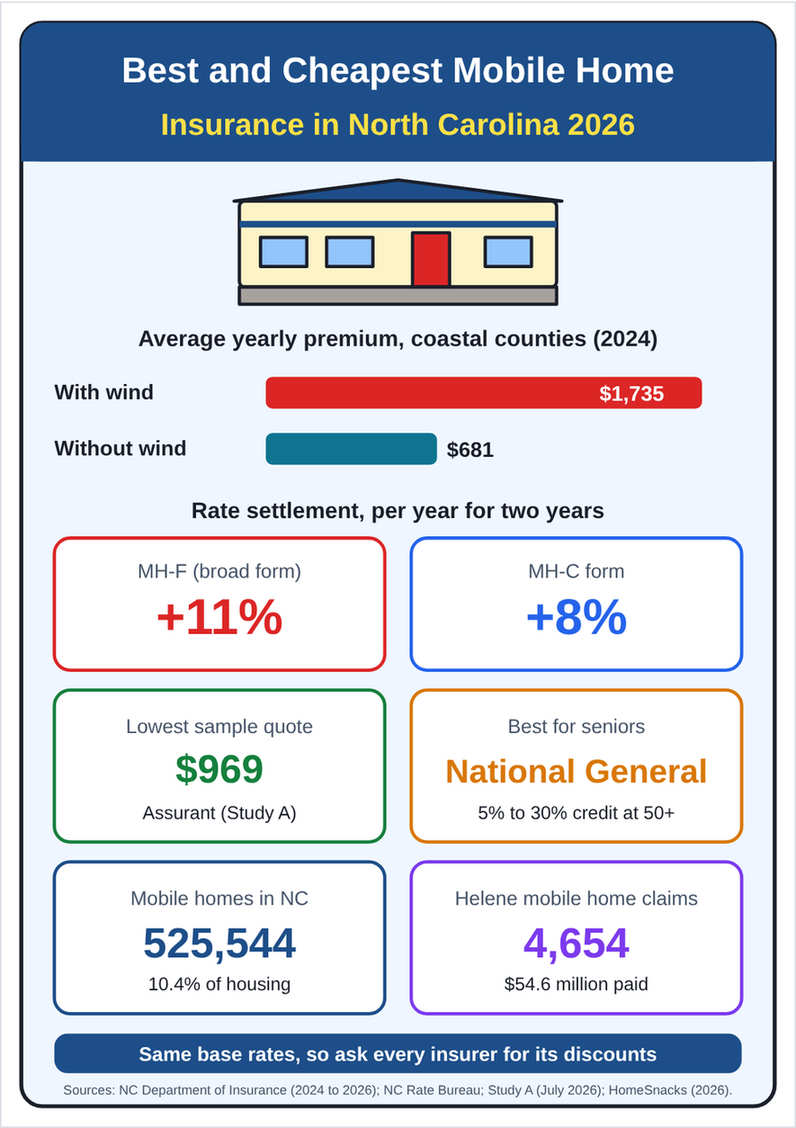
North Carolina mobile home insurance at a glance. Coastal averages from North Carolina Department of Insurance 2024 data; sample quotes from Study A, gathered outside North Carolina. Averages, not quotes.
How mobile home insurance prices are set in North Carolina
North Carolina has one of the most regulated insurance markets in the country. The North Carolina Rate Bureau, which represents the insurers that sell in the state, files base rates with the Department of Insurance for two mobile home programs, called MH-F and MH-C. The commissioner can approve, reject, or settle those requests.
Every insurer starts from the same Rate Bureau rates. Companies then file deviations, which are discounts or credits for things like a newer home, tie-downs, an older owner, or bundling. That is why North Carolina has no simple price list by company. The cheapest insurer for you is the one whose filed discounts best match your home and situation.
The two North Carolina mobile home programs
| Program | What it is | 2025 settlement |
|---|---|---|
| MH-F | The broader form, covering more perils | +11% on September 1, 2025, and +11% in late summer 2026 |
| MH-C | A narrower form at a lower price | +8% on September 1, 2025, and +8% in late summer 2026 |
| Both | Include flood coverage, according to the Department of Insurance | No new increase before September 1, 2027 |
North Carolina Department of Insurance (April 1, 2025); North Carolina Rate Bureau Circular P-25-2. The department dates the second step August 31, 2026, and the Rate Bureau September 1, 2026.
Insurers can also charge more than the standard rate through consent to rate, but only if you sign a form agreeing to it. North Carolina law allows up to 250% of the standard rate this way. If you are ever asked to sign a consent-to-rate form, shop other companies first.
The 2025 mobile home rate settlement
On April 8, 2024, the Rate Bureau asked for average increases of 82.9% for MH-F and 49.9% for MH-C over three years. Insurance Commissioner Mike Causey negotiated a settlement instead, announced April 1, 2025, that cancelled the scheduled hearing. About 148,000 policyholders are affected, and the department estimated they will save more than $10 million a year compared with the original request.
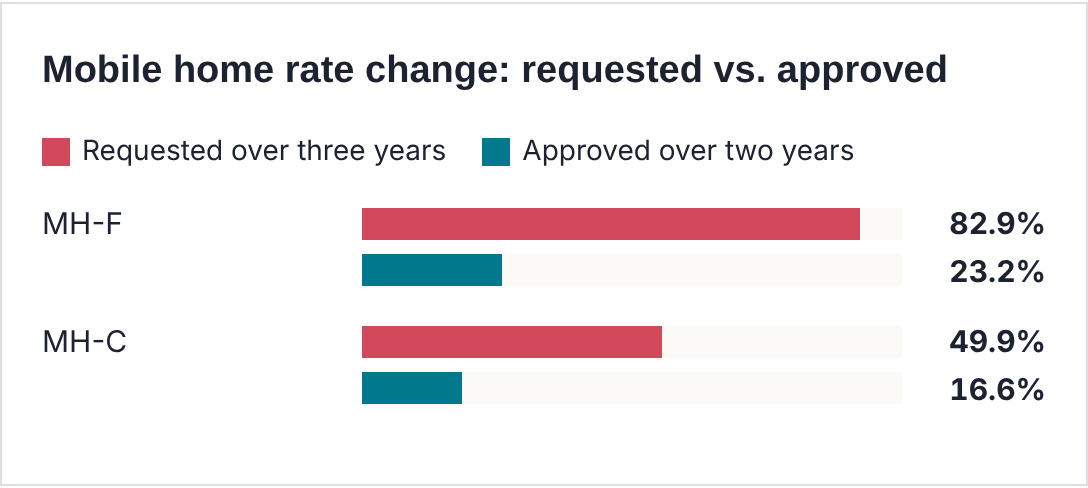
North Carolina Department of Insurance (April 1, 2025). Approved totals are our calculation from two annual increases of 11% and 8%.
Some coastal areas pay more. Under the settlement, MH-F rates rise 15% a year in Currituck, Dare, and Hyde counties and 13% a year in Camden, Pasquotank, Perquimans, Chowan, Tyrrell, and Washington counties, according to the Island Free Press. MH-C rates rise 12.9% a year in Outer Banks counties and 9.1% in nearby inland counties.
How much mobile home insurance costs in North Carolina
The best North Carolina price data comes from a 2024 Department of Insurance study of coastal and beach homes. It found that mobile homes in coastal counties averaged about $1,735 a year for full coverage including wind, and about $681 without wind, with wind bought separately. In beach areas, full coverage averaged $1,888 to $2,181.
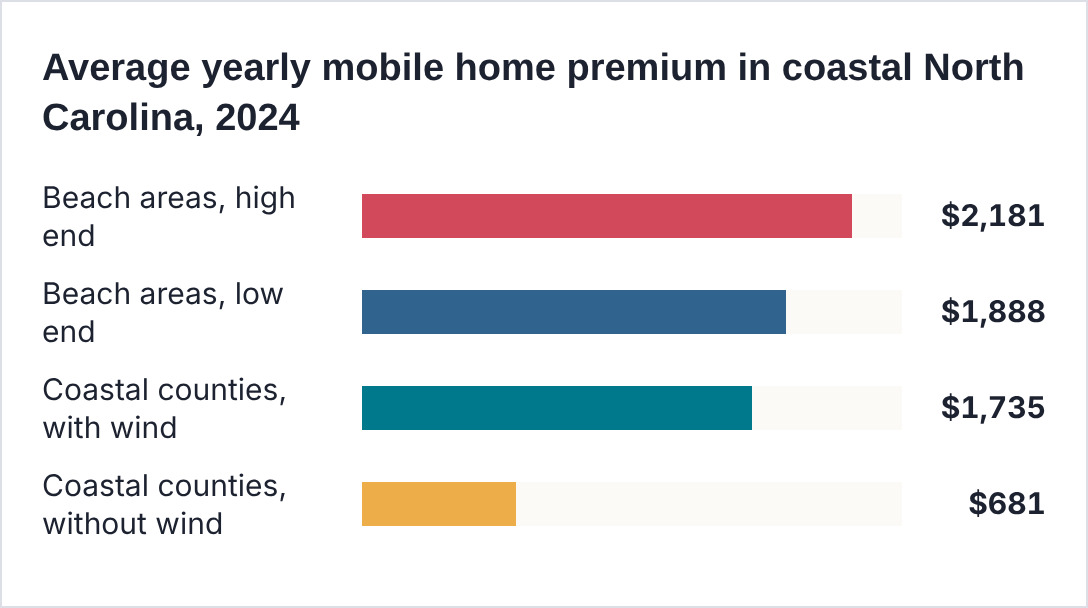
North Carolina Department of Insurance 2024 beach and coastal area homeowners data call. Averages, not quotes.
Statewide prices are lower, because most of the state faces less hurricane risk. The Rate Bureau's own 2024 filings suggest an average of roughly $1,100 to $1,200 a year before the settlement. After both increases, a typical policy is likely to cost roughly $1,300 to $1,400 a year in 2026, before discounts (our estimate). Your exact price depends on your county, form, home age, and the discounts your insurer has filed.
Mobile homes cost far less to insure than regular homes. A 2026 national study put the average North Carolina homeowners premium at $3,025 a year, compared with $2,490 nationally.
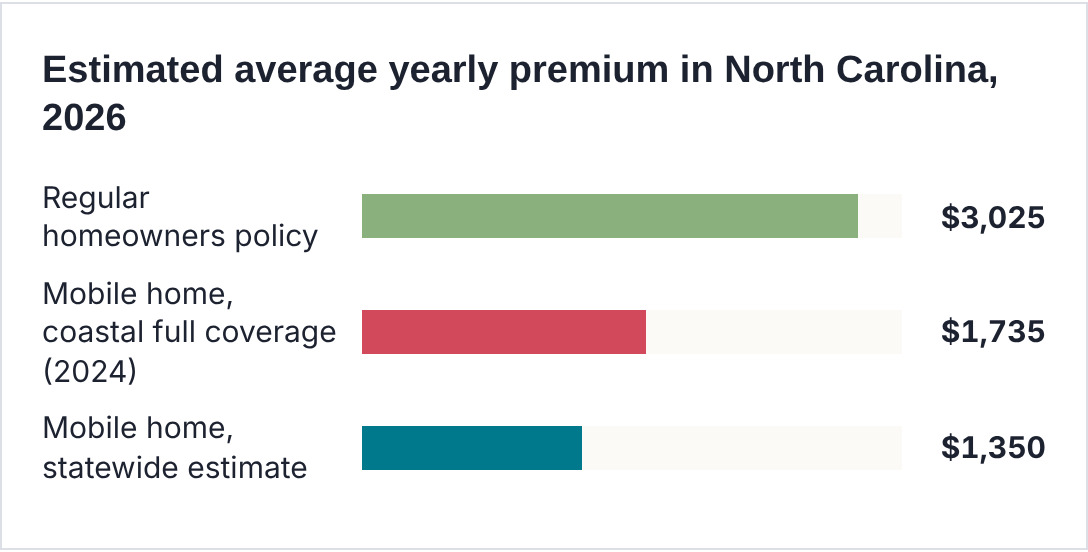
National homeowners study (2026); North Carolina Department of Insurance (2024 coastal data); statewide figure is our estimate from Rate Bureau filings and the 2025 settlement. Averages, not quotes.
North Carolina mobile homes by the numbers
North Carolina has about 525,544 mobile homes, according to 2024 Census data, making up 10.4% of all housing. That is the third-largest count in the country, behind Florida and Texas, and the ninth-highest share. A listing site shows about 2,869 mobile home parks across the state, and in some rural eastern counties, such as Tyrrell, Bertie, and Gates, more than 30% of homes were mobile homes in a 2018 study.
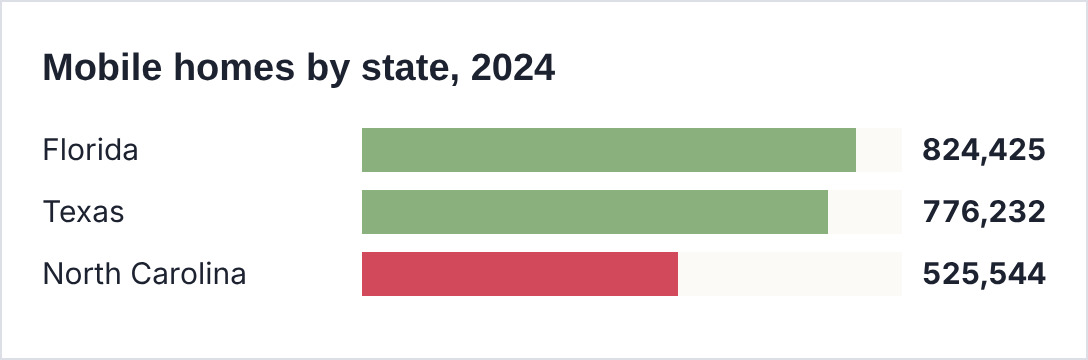
Census American Community Survey 2024, as reported July 18, 2026.
The top 10 cheapest mobile home insurance companies in North Carolina
Because every company starts from the same Rate Bureau rates, we ranked insurers by the size and range of the discounts they have filed with the Rate Bureau, backed by Study A, a 2026 national quote study that priced the same single-wide home at Assurant, American Modern, and Foremost. Study A's quotes came from other states, so use them to compare companies, not as North Carolina prices.
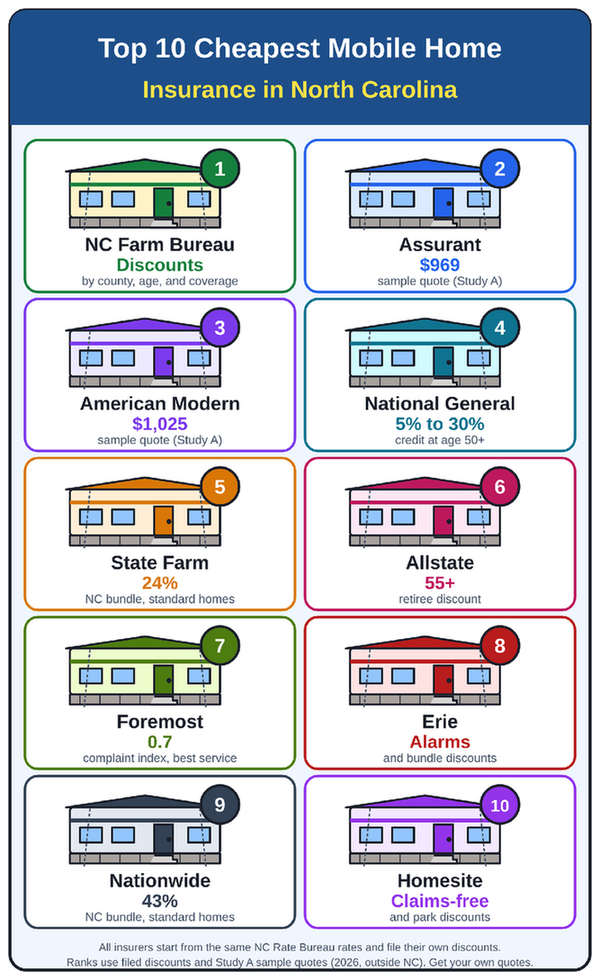
The 10 cheapest mobile home insurance companies in North Carolina, ranked by filed discounts and Study A sample quotes. Get your own quotes.
Top 10 cheapest mobile home insurance companies in North Carolina
| Rank | Company | Price evidence | Rating | Complaint index |
|---|---|---|---|---|
| 1 | NC Farm Bureau | Discounts filed by county, home age, and coverage | Not confirmed | Not reported |
| 2 | Assurant | $969 sample quote (Study A) | AM Best A+ | 3.1 |
| 3 | American Modern | $1,025 sample quote (Study A) | AM Best A+ | 1.4 |
| 4 | National General | 5% to 30% credit at age 50+; 22% for new tied-down homes | Not confirmed | Not reported |
| 5 | State Farm | Cheapest for standard NC homes in two studies | AM Best A+ | 1.4 |
| 6 | Allstate | Retiree 55+, original owner, and park discounts | AM Best A+ | 1.2 |
| 7 | Foremost | $1,607 sample quote; most NC discounts | AM Best A | 0.7 |
| 8 | Erie | Bundle, alarm, and rating tier discounts | Not confirmed | Not reported |
| 9 | Nationwide | Home age and owner age discounts | Not confirmed | Not reported |
| 10 | Homesite | Claims-free and park discounts | Not confirmed | Not reported |
North Carolina Rate Bureau deviation lists (MH-F as of March 31, 2025; MH-C as of June 30, 2024); Study A: national mobile home quote study updated July 6, 2026; Study B: national mobile home insurance review updated September 15, 2026, for AM Best ratings and the 2025 NAIC complaint index (1.0 is average, lower is better).
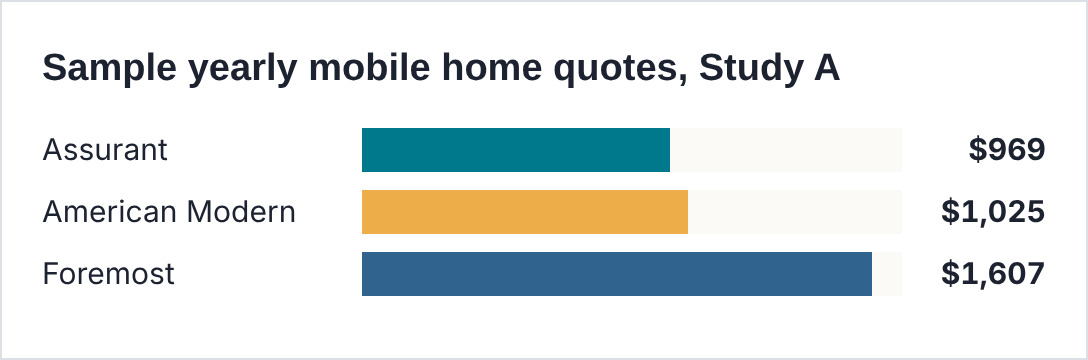
Study A: national quote study updated July 6, 2026, for a 2016 single-wide in a park with $51,000 to $63,000 of dwelling coverage, quoted in Texas, Indiana, and Arizona. Not North Carolina prices.
1. NC Farm Bureau: best overall for most owners
North Carolina Farm Bureau Insurance has filed mobile home discounts based on the amount of insurance, the county, and the year the home was built, which gives it room to price many homes below the Rate Bureau base. For standard homes, it ranked as the second-cheapest North Carolina insurer in two 2026 rate studies, and one called it the cheapest for coastal homes. It also sells auto insurance, so most members can bundle. A Farm Bureau membership is required.
2. Assurant: lowest sample quote
Assurant had the lowest price in Study A, at $969 a year, and AM Best rates it A+. Its service record is the weakness: its 2025 complaint index of 3.1 means about three times the expected number of complaints. Assurant policies are also sold through GEICO, so you may see it under that name.
3. American Modern: strong price and rating
American Modern quoted $1,025 a year in Study A, only $56 more than Assurant, and carries an A+ rating from AM Best. It has filed North Carolina discounts for homes in parks and sells through independent agents and partners such as Progressive. Its complaint index of 1.4 is somewhat above average.
4. National General: best for seniors
National General, an Allstate company that writes through Integon, has some of the largest filed mobile home discounts in the state. Its filings include a credit of 5% to 30% for policyholders aged 50 and older, while its New South company gives 22% for tied-down primary homes up to six years old and 5% for older ones. Integon General has filed a 10% tie-down discount.
5. State Farm: best for bundling with a local agent
State Farm was the cheapest insurer for standard North Carolina homes in two 2026 rate studies, and a third found its home and auto bundle saved 24% in North Carolina. It has not filed mobile home price discounts with the Rate Bureau, so its mobile home price starts near the base rate, but its auto savings can make the total package cheap. AM Best rates it A+.
6. Allstate: discounts for retirees
Allstate has filed North Carolina mobile home discounts for retirees aged 55 and older, original owners, and homes in larger parks. Its complaint index of 1.2 is close to average, and AM Best rates it A+.
7. Foremost: best for service and older homes
Foremost had the highest sample quote in Study A, at $1,607, but it has filed more North Carolina mobile home discounts than most companies and has the lowest complaint index on our list, at 0.7. It insures homes of any age and offers discounts for owners 50 and older, AARP members, and homes in approved parks. AM Best rates it A. Farmers, GEICO, Progressive, and USAA also sell Foremost policies.
8. Erie: bundle and alarm discounts
Erie has filed mobile home discounts for bundling, alarms, and its rating tiers. For standard North Carolina homes, Erie's home and auto bundle saved 18% in a 2026 study. It sells through local independent agents.
9. Nationwide: biggest bundle savings
Nationwide has filed North Carolina mobile home discounts based on the age of the home and the age of the oldest policyholder. For standard homes, its home and auto bundle saved 43% in a 2026 North Carolina study, the largest of any company tested.
10. Homesite: claims-free savings
Homesite has filed claims-free and park discounts for North Carolina mobile homes. Other smaller companies with filed discounts include Northland, a Travelers company, Horace Mann, which offers a 10% claims-free discount for educators, and Windsor-Mount Joy.
PRO TIP #1
Because every North Carolina insurer starts from the same base rate, ask each company which discounts it has filed for mobile homes. A company with a large age, tie-down, or newer-home discount can beat a better-known name by hundreds of dollars.
The overall cheapest mobile home insurance in North Carolina
No public study lists North Carolina mobile home prices by company, so no one can name a single cheapest insurer with certainty. Based on filed discounts and price studies, NC Farm Bureau is likely the cheapest for most North Carolinians, especially if you bundle auto. Assurant had the lowest sample quote in Study A, and seniors should check National General, whose 5% to 30% credit for owners 50 and older is one of the largest discounts on file.
Get quotes from all three, then add one company with strong service, such as Foremost. Compare the totals for the same form, coverage limits, and deductibles.
The best mobile home insurance in North Carolina by need
Best mobile home insurance in North Carolina, by need
| Need | Best pick | Why |
|---|---|---|
| Most owners | NC Farm Bureau | Filed discounts by county, age, and coverage |
| Lowest sample quote | Assurant | $969 in Study A |
| Seniors | National General | 5% to 30% credit at age 50+ |
| Service | Foremost | Lowest complaint index, 0.7 |
| Bundling with an agent | State Farm | 24% NC bundle on standard homes |
| Biggest bundle | Nationwide | 43% NC bundle on standard homes |
| Newer tied-down homes | National General (New South) | 22% discount |
| Coastal wind | Beach Plan | Wind coverage in 18 coastal counties |
| Last resort | NC FAIR Plan | For homes private insurers decline |
Our assessment, based on North Carolina Rate Bureau filings, Study A, Study B, and 2026 North Carolina rate studies.
Cheapest mobile home insurance for seniors in North Carolina
Seniors have the best discounts in North Carolina's filings. National General's credit of 5% to 30% for owners 50 and older is the largest age discount on file, Allstate offers a discount for retirees 55 and older, and Foremost offers one for owners 50 and older and AARP members.
Mobile home insurance options for North Carolina seniors
| Company | Senior benefit | Other savings |
|---|---|---|
| National General | 5% to 30% credit at age 50+ | 22% for newer tied-down homes (New South) |
| Foremost | Discount at 50+; AARP program | Lowest complaint index |
| Allstate | Discount for retirees 55+ | Original owner and park discounts |
| Nationwide | Discount based on the oldest policyholder's age | Home age discount |
| NC Farm Bureau | No age discount found | County and home age discounts; bundling |
North Carolina Rate Bureau deviation lists (2024 and 2025); company websites.
Seniors can also lower property taxes. North Carolina's homestead exclusion names manufactured homes and covers owners 65 or older, or disabled, with incomes up to $38,800 in 2026. It excludes the greater of $25,000 or 50% of the home's value from property taxes. A separate circuit breaker program has a 2026 income limit of $58,200.
PRO TIP #2
If you are 65 or older and your income is under $38,800, apply for the homestead exclusion with your county tax office. Paired with a 50+ insurance credit, it can cut your yearly housing costs by hundreds of dollars.
The Beach Plan and the FAIR Plan for mobile homes
North Carolina has two insurers of last resort, both run by the same association. The Beach Plan, officially the Coastal Property Insurance Pool, sells wind coverage in the 18 coastal counties. The NC FAIR Plan sells property coverage across the state for homes private insurers will not cover. Both accept mobile homes.
Beach Plan and FAIR Plan rules for mobile homes
| Rule | Details |
|---|---|
| Age | Built after June 15, 1976 |
| Setup | Tied down; coastal homes must meet North Carolina wind zone rules |
| Replacement cost | Owner-occupied, permanent foundation, titled as real property, wheels removed |
| Actual cash value form | Requires continuous skirting |
| Older homes | Homes over 20 years old must be in good condition |
| Limits | Up to $1 million per building; contents up to 40% |
| Deductibles | From $500; 1% named-storm deductible on the coast |
North Carolina Joint Underwriting Association and Insurance Underwriting Association rule manuals (January 2025).
If you live on the coast and your private insurer excludes wind, a Beach Plan wind policy plus a no-wind mobile home policy can be cheaper. In 2024 state data, coastal mobile homes without wind averaged about $681 a year, before the cost of separate wind coverage.
North Carolina wind zones
North Carolina uses its own wind zones for mobile home installation. Carteret, Dare, and Hyde counties are in Wind Zone III, 16 more coastal-plain counties, including Columbus, are in Wind Zone II, and the rest of the state is in Wind Zone I. A home cannot be placed in a higher wind zone than its data plate allows unless an engineer certifies it. The Office of State Fire Marshal, not the Department of Insurance, now oversees manufactured home installation.
Lessons from Hurricane Helene
Hurricane Helene devastated western North Carolina in September 2024. By March 2025, insurers had received 4,654 mobile home claims and paid $54.6 million, about $11,700 per claim (our calculation). The state budget office counted 151,000 homes reporting damage and $9.6 billion in uninsured residential losses, and 94% of households that applied for FEMA aid had no flood insurance.
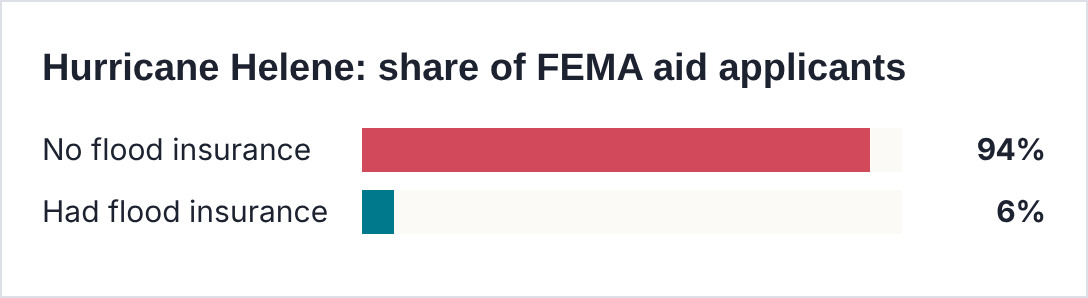
North Carolina Office of State Budget and Management, Hurricane Helene assessment (based on October 2024 data). The 6% figure is our calculation.
Recovery has been slow. As of July 15, 2026, the state's Renew NC program had completed 89 homes, with 71 more under construction. Tropical Storm Chantal also destroyed mobile homes in Lee County in July 2025, and a September 2026 nor'easter brought major flooding to the Outer Banks. Storms reach every part of the state, not just the coast.
Flood coverage for North Carolina mobile homes
North Carolina is unusual. The Department of Insurance says both Rate Bureau mobile home programs, MH-F and MH-C, include flood coverage, unlike standard homeowners policies. Read your own policy to see the flood limit and conditions, because the coverage may not be enough after a major flood.
For more protection, the National Flood Insurance Program covers manufactured homes anchored to a permanent foundation, with up to $250,000 for the home and $100,000 for contents. North Carolina had 130,393 NFIP policies in force in April 2026. NFIP coverage usually starts after a 30-day wait.
PRO TIP #3
Ask your agent to show you the flood section of your mobile home policy. If its limit is low, or you live in the mountains or near a river, add an NFIP policy at least 30 days before storm season.
North Carolina laws every mobile home owner should know
- North Carolina law does not require mobile home insurance, but lenders and many parks do.
- A mobile home is taxed as personal property unless it sits on a permanent foundation, has its wheels and axles removed, and is on land the owner owns or leases for at least 20 years.
- Owners can record a declaration with the county Register of Deeds to treat the home as real property, under G.S. 47-20.7.
- Insurers can charge up to 250% of the standard rate only if you sign a consent-to-rate form.
- The homestead exclusion for owners 65 and older, or disabled, specifically includes manufactured homes.
- The Office of State Fire Marshal oversees manufactured home installation and wind zone rules.
What North Carolina mobile home insurance covers
Main coverage parts of a North Carolina mobile home policy
| Coverage | What it pays for |
|---|---|
| Dwelling | Repairs or replacement of the home |
| Other structures | Carports, decks, sheds, and skirting |
| Personal property | Furniture, clothes, and belongings |
| Loss of use | Living costs after a covered loss |
| Personal liability | Injuries or damage you cause to others |
| Flood | Included in MH-F and MH-C programs, subject to policy limits |
| Wind | Included, or bought from the Beach Plan on the coast |
North Carolina Department of Insurance; company policy descriptions. Coverage varies by form and insurer.
The main choice is between the broader MH-F form and the cheaper MH-C form. MH-F covers more perils and costs more, while MH-C trades some protection for a lower price. Also ask whether your policy pays replacement cost or actual cash value, since actual cash value subtracts depreciation and can leave you short after a total loss.
What sets your mobile home insurance price in North Carolina
Main factors in your North Carolina mobile home premium
| Factor | Why it matters |
|---|---|
| Form | MH-F covers more and costs more than MH-C |
| County | Coastal and Outer Banks counties face higher rates |
| Wind coverage | Excluding wind on the coast cuts the premium but needs separate coverage |
| Year built | Newer homes earn discounts at several insurers |
| Tie-downs | Tied-down homes earn up to 22% at New South |
| Owner age | Credits from 50 or 55 at several insurers |
| Filed discounts | Each insurer files its own discounts against the same base rate |
| Claims history | Claims-free discounts at Horace Mann, Homesite, and others |
North Carolina Rate Bureau deviation lists (2024 and 2025); North Carolina Department of Insurance.
Mobile home insurance vs. homeowners insurance in North Carolina
How North Carolina mobile home and homeowners policies compare
| Feature | Mobile home policy | Homeowners policy |
|---|---|---|
| Typical yearly cost | About $1,300 to $1,400 statewide (estimate) | About $3,025 |
| 2025 settlement | +11% (MH-F) or +8% (MH-C) a year for two years | +7.5% a year for two years |
| Flood | Included in both Rate Bureau programs | Not included |
| Next increase allowed | Not before September 1, 2027 | Set by later filings |
North Carolina Department of Insurance (January 17 and April 1, 2025); national homeowners study (2026). Statewide mobile home figure is our estimate.
Park homes vs. homes on private land
Homes in parks can earn discounts at Foremost, Allstate, and American Modern, and many parks require insurance in the lease. Read your park rules for any required liability limits.
Homes on land you own often need more coverage for sheds, carports, decks, and fences, and you are responsible for liability on the whole lot. If the home sits on a permanent foundation on your land, you may be able to record it as real property, which can open up replacement-cost coverage through the FAIR Plan and the homestead exclusion.
Bundling mobile home and auto insurance in North Carolina
Bundling is one of the best ways to save in North Carolina, because auto discounts can be large. The only published North Carolina bundle figures are for standard homes, but they show which companies reward bundling most.
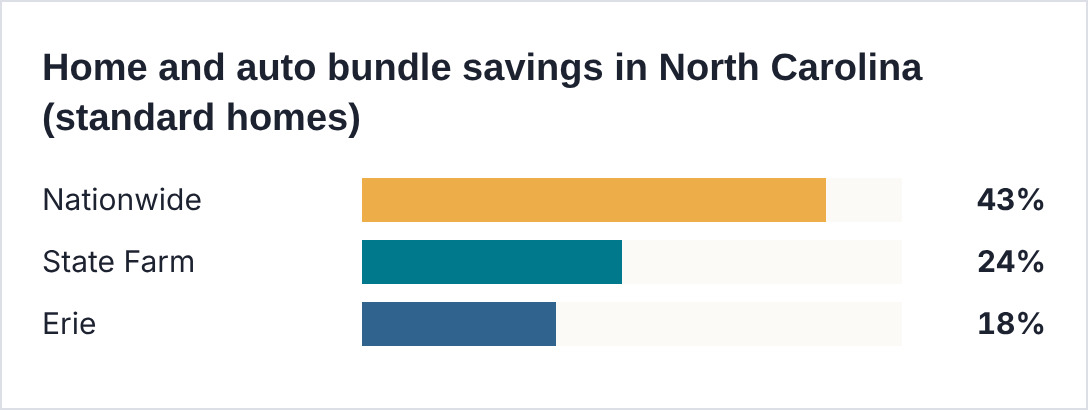
Study C: North Carolina home and auto bundle study (April 2026). Figures are for standard homes, not mobile homes.
Bundling options for North Carolina mobile home owners
| Company | How bundling works | Notes |
|---|---|---|
| NC Farm Bureau | Home and auto under one membership | Percentage not published |
| State Farm | Bundle through a local agent | 24% for standard NC homes |
| Nationwide | Multi-policy discount | 43% for standard NC homes |
| Erie | Filed mobile home bundle discount | 18% for standard NC homes |
| Foremost | Multi-policy discount | Also covers boats, ATVs, and RVs |
| Progressive | Average 5% on auto nationally | Places mobile homes with partners |
Study C (April 2026); North Carolina Rate Bureau deviation lists; company websites.
Compare a bundle from NC Farm Bureau, State Farm, or Nationwide against a lower-priced mobile home policy from Assurant or American Modern paired with your cheapest car insurer. Pick whichever total is lower for the coverage you need.
Mobile home insurance discounts in North Carolina
Discounts filed by North Carolina mobile home insurers
| Discount | Who has filed it |
|---|---|
| Age 50+ or 55+ retiree | National General (5% to 30%), Foremost, Allstate, Nationwide |
| Tied-down newer home | New South (22% up to six years old; 5% older), Integon General (10%) |
| Mobile home park | Foremost, Allstate, American Modern, Homesite |
| Newer home | NC Farm Bureau, Nationwide, Foremost |
| Alarms | State Farm, Erie |
| Claims-free | Horace Mann (10%), Homesite |
| Bundling | Erie, Foremost, and most agents |
| Original owner | Allstate |
| Paid in full | Several insurers |
North Carolina Rate Bureau deviation lists (MH-F as of March 31, 2025; MH-C as of June 30, 2024). The state's FORTIFIED wind credits apply to standard homes; we found no evidence they apply to mobile homes.
Tips to save money on mobile home insurance in North Carolina
- Get at least three quotes, starting with NC Farm Bureau, Assurant, and National General.
- Ask each company which mobile home discounts it has filed with the Rate Bureau.
- Compare the MH-F and MH-C forms, and choose the one that fits your budget and risk.
- Make sure your home is properly tied down, and ask for a tie-down discount.
- Ask for age 50+ or retiree credits if you qualify.
- Bundle with auto through NC Farm Bureau, State Farm, Nationwide, or Erie.
- On the coast, compare a full policy with a no-wind policy plus Beach Plan wind coverage.
- Do not sign a consent-to-rate form until you have shopped other companies.
- Check the flood limit in your policy, and add NFIP coverage if you need more.
- Apply for the homestead exclusion if you are 65 or older and qualify.
- Recheck prices before the next rate step and every year after.
How to compare North Carolina mobile home insurance quotes
- Ask every company for the same form, MH-F or MH-C, and the same limits and deductibles.
- Check whether each quote pays actual cash value or replacement cost.
- Confirm whether wind is included, and how flood coverage works.
- Ask which filed discounts are already applied.
- Check each insurer's AM Best rating and complaint index.
The North Carolina Department of Insurance publishes a consumer guide to manufactured homeowners insurance and runs a consumer helpline if you have a problem with an insurer.
North Carolina mobile home insurance by region
The biggest risk to your home depends on where you live in North Carolina, and that should shape the coverage you buy.
Main risks and coverage needs by North Carolina region
| Region | Main risk | What to check |
|---|---|---|
| Outer Banks and coast | Hurricanes and storm surge | Wind coverage or Beach Plan, flood limits, higher coastal rates |
| Coastal plain | Hurricanes and river flooding | Wind Zone II rules, flood coverage, tie-downs |
| Piedmont | Severe storms and tornadoes | Tie-downs, wind and hail coverage, park discounts |
| Mountains | Flash floods and landslides | Flood limits, NFIP coverage, loss of use |
Our assessment, based on North Carolina Department of Insurance, Rate Bureau, and storm data.
Insuring older and pre-1976 mobile homes in North Carolina
Homes built before June 15, 1976, when the federal HUD code took effect, are harder to insure. The Beach Plan and FAIR Plan accept only homes built after that date, and homes over 20 years old must be in good condition. Foremost insures homes of any age, so it is a good first call for an older home.
If your home is older, keep records of updates to the roof, wiring, plumbing, and heating, make sure it is properly tied down, and add continuous skirting. Those steps make your home safer in a storm and can help you qualify for coverage and discounts.
Questions to ask before you buy
- Is this quote for the MH-F or MH-C form, and what perils does it cover?
- Does the policy pay replacement cost or actual cash value?
- Is wind included, and what is the named-storm deductible?
- What is the flood limit, and what conditions apply?
- Which filed discounts are already applied, and which could I still add?
- Are carports, decks, skirting, and sheds covered, and up to what limit?
- Am I being asked to sign a consent-to-rate form?
Write down the answers for each company. Because every insurer starts from the same base rate, these answers usually explain why one quote is cheaper than another.
What to do after a storm
- Get to safety, then call your insurer or agent as soon as you can.
- Take photos and video of all damage before cleaning up.
- Make temporary repairs, such as tarps, and keep the receipts.
- Ask about loss-of-use coverage for living costs.
- File wind claims with the Beach Plan if it insures your wind risk, and flood claims under your policy's flood coverage or your NFIP policy.
- Get your adjuster's name and contact details, and keep notes of every call.
- If you disagree with the settlement, contact the Department of Insurance consumer helpline.
North Carolina mobile home insurance at a glance
This illustrated summary pulls together the main points of this guide.
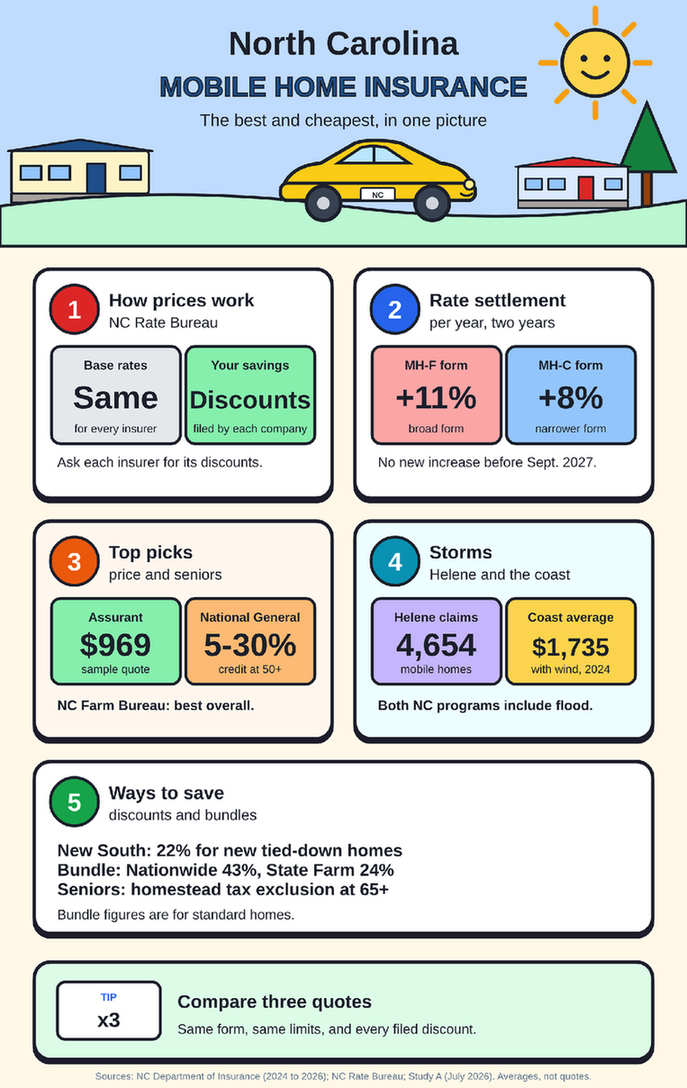
The best and cheapest mobile home insurance in North Carolina at a glance. Sources: North Carolina Department of Insurance; North Carolina Rate Bureau; Study A.
Frequently asked questions about North Carolina Mobile Home Insurance
How much is mobile home insurance in North Carolina?
Coastal mobile homes averaged about $1,735 a year for full coverage in 2024 state data. Statewide prices are lower, likely around $1,300 to $1,400 in 2026 before discounts, based on Rate Bureau filings and the 2025 settlement. Your county, form, and discounts set your price.
Who has the cheapest mobile home insurance in North Carolina?
No study lists North Carolina prices by company. NC Farm Bureau is likely cheapest for most owners, Assurant had the lowest sample quote in Study A at $969, and National General has filed a 5% to 30% credit for owners 50 and older.
Why do North Carolina insurers charge similar prices?
The North Carolina Rate Bureau files base mobile home rates for all insurers. Each company then files its own discounts, so the cheapest insurer for you depends on which discounts match your home, age, and location.
How much did mobile home insurance go up in North Carolina?
Under the April 2025 settlement, MH-F rates rise 11% a year and MH-C rates 8% a year for two years, starting September 1, 2025. Some coastal counties pay more. Insurers cannot ask for another increase before September 1, 2027.
What is the best mobile home insurance for seniors in North Carolina?
National General is our pick, with a filed credit of 5% to 30% for owners 50 and older. Foremost offers a 50+ and AARP discount, and Allstate offers one for retirees 55 and older. Seniors may also qualify for the homestead property tax exclusion.
Does North Carolina mobile home insurance cover floods?
The Department of Insurance says both Rate Bureau mobile home programs include flood coverage, unlike standard homeowners policies. Check your policy's flood limit, and consider an NFIP policy for more protection.
Can I bundle mobile home and auto insurance in North Carolina?
Yes. NC Farm Bureau, State Farm, Nationwide, and Erie all offer bundles. For standard North Carolina homes, Nationwide's bundle saved 43%, State Farm's 24%, and Erie's 18% in a 2026 study.
Is mobile home insurance required in North Carolina?
No state law requires it, but lenders require it on financed homes, and many parks require it in the lease. Because hurricanes, floods, and severe storms reach every region of the state, insurance is strongly recommended even if your home is paid off.
Can I insure an older mobile home in North Carolina?
Yes, but fewer companies will. Foremost insures homes of any age. The Beach Plan and FAIR Plan accept only homes built after June 15, 1976, and homes over 20 years old must be in good condition. Tie-downs and skirting help older homes qualify.
Does the Beach Plan cover mobile homes?
Yes. The Beach Plan sells wind coverage in 18 coastal counties, and the FAIR Plan covers homes statewide. Mobile homes must be built after June 15, 1976, and tied down, and coastal homes must meet North Carolina wind zone rules.
The final word on the best and cheapest mobile home insurance in North Carolina
The best and cheapest mobile home insurance in North Carolina comes down to discounts, because every insurer starts from the same Rate Bureau rates. NC Farm Bureau is the best starting point for most owners, Assurant had the lowest sample quote, National General is the standout for seniors, and Foremost leads on service.
Rates are rising through 2026 under the 2025 settlement, but they are locked in until at least September 2027. Compare at least three quotes on the same form, ask every company for its filed discounts, bundle with auto, and check your flood coverage before the next storm.
Sources
- North Carolina Department of Insurance, mobile home rate settlement (April 1, 2025), and rate request (April 11, 2024).
- North Carolina Rate Bureau, Circular P-25-2 (2025), and mobile home deviation lists (MH-F, March 31, 2025; MH-C, June 30, 2024).
- North Carolina Department of Insurance, manufactured homes and consumer guide to manufactured homeowners insurance.
- North Carolina Department of Insurance, 2024 beach and coastal area data call, and Hurricane Helene data call (data as of March 28, 2025).
- North Carolina Department of Insurance, homeowners rate settlement (January 17, 2025).
- Island Free Press, mobile home rate increases (April 4, 2025).
- North Carolina Joint Underwriting Association and Insurance Underwriting Association, coverage and rule manuals (January 2025).
- Office of State Fire Marshal, manufactured homes.
- Office of State Budget and Management, Hurricane Helene summary, and Renew NC housing program.
- G.S. 105-277.1, homestead exclusion; 2026 homestead income limits memo; and UNC School of Government, mobile homes and property taxes.
- FEMA, manufactured homes flood coverage (August 2025), and NAIC, flood insurance data (May 2026).
- HomeSnacks, mobile homes by state (July 18, 2026), using 2024 Census data, and UNC School of Government, manufactured housing in North Carolina.
- National Weather Service, September 2026 nor'easter.
- Study A: ValuePenguin, mobile home insurance (July 6, 2026).
- Study B: LendingTree, best mobile home insurance companies (September 15, 2026).
- Study C: Insurance.com, cheapest home and auto bundle in North Carolina (April 2026).
- MoneyGeek, cheap homeowners insurance in North Carolina, and ValuePenguin, cheap homeowners insurance in North Carolina (2026).
- Foremost, mobile home insurance.
Disclaimer
This website provides independent reviews and comparisons. It is not affiliated with, endorsed by, sponsored by, or connected to North Carolina Farm Bureau Insurance, Assurant, American Modern, National General, Integon, New South, State Farm, Allstate, Foremost, Farmers, Erie Insurance, Nationwide, Homesite, Horace Mann, the North Carolina Rate Bureau, the Coastal Property Insurance Pool, the NC FAIR Plan, AARP, or any of their affiliates.
All company names, brand names, trademarks, and logos are the property of their respective owners and are used here only to identify the companies being reviewed. Their use does not imply any affiliation or endorsement.
The information on this page is provided for general informational and educational purposes only. It is not insurance, legal, tax, or financial advice, and it is not an offer, quote, or solicitation to buy or sell insurance. We are not an insurance company, insurance agency, or licensed insurance producer, and we cannot bind coverage, change a policy, or handle claims.
Prices, discounts, ratings, and company details are drawn from public sources, state filings, and third-party studies that use specific home profiles, and they can change at any time. They are estimates and averages, not guarantees of what you will pay. Coverage, eligibility, and discounts vary by location, home, and owner, and are subject to each insurer's underwriting rules and policy terms.
While we make reasonable efforts to keep this guide accurate and current, we make no representations or warranties, express or implied, about its completeness, accuracy, or reliability. Opinions here are our own. Always confirm details directly with the insurer, read your policy documents, and consult the North Carolina Department of Insurance or a licensed professional before making a decision. Your use of this information is at your own risk, and we are not liable for any loss or damage arising from reliance on it.