
Best and Cheapest Chevrolet Silverado Insurance: 2027 Guide
QUICK ANSWER
Travelers had the lowest listed rate available to the general public for a 2025 Silverado 1500 in Study A, at $1,865 a year for its sample driver. In that study, USAA was $1,949 for eligible military households, while GEICO led Study E’s different all-model-year sample at $125 a month. State Farm led Study A’s separate Florida example. No one insurer is verified as cheapest for every Silverado owner.
KEY TAKEAWAYS
- For a new Silverado 1500, a 40-year-old pays about $2,546 to $2,928 a year for full coverage across three studies.
- The Silverado 1500 ranked fourth by total U.S. vehicle thefts in 2025. That is a count, not a model-specific theft rate; comprehensive coverage and anti-theft precautions deserve review.
- Trim matters less than you might think: Study D's range from a WT to a High Country is only $291 a year.
- For the same 2025 Silverado 1500, Allstate charges $1,747 a year more than Travelers in Study A.
- About 107,244 2021 to 2024 Silverado 1500s with the 6.2-liter V8 are part of a major engine recall, and NHTSA is now investigating failures after the repair.
For the millions of truck owners who drive one, comparison shopping can reveal price differences of more than $1,700 annually within a published sample. Chevrolet sold 362,909 Silverado 1500s in the United States in 2025, up 1.2%, and GM says the Silverado and its GMC Sierra twin had their best combined sales in 20 years. In Study B, a 40-year-old good driver pays an estimated $2,546 a year to insure a Silverado 1500, $50 above that study's average for popular pickups.
Behind that number sit nine trims, four engines, three cab styles, an electric Silverado EV, and an all-new 2027 model with new V8s. The Silverado also ranks high in absolute theft counts, although those counts do not measure an individual vehicle’s theft probability, and its 6.2-liter V8 has been the subject of one of the biggest engine recalls of recent years. All of these shape what you pay and what you need from your policy.
This guide draws on six rate studies, insurance-loss data, theft rankings, crash-test results, recall records, and insurer discount pages. It covers the light-duty Silverado 1500 and the Silverado EV; the heavy-duty 2500HD and 3500HD will get their own guide. Each study uses its own sample driver, limits, and deductible, so compare figures within one study.
WHAT CHANGED IN THIS UPDATE
- November 4, 2026: Added Study A's October 26, 2026 Silverado 1500 prices by company for 2018 to 2025 and its Florida sample.
- June 2026: Added the next-generation 2027 Silverado 1500, with new 5.7-liter and 6.6-liter V8s.
- May 21, 2026: Added Study E's prices by company, model year, cab, and trim, including the ZR2.
- March 2026: Added NICB's 2025 most-stolen list, with the Silverado 1500 in fourth place.
- January 2026: Added NHTSA's investigation into 6.2-liter V8 engine failures after recall repairs.
IN THIS GUIDE
- The insurer comparisons, the lowest sample rates by model year, and the best for service
- A find-your-price table, example drivers, and the combined price range
- Trim cards from WT to ZR2, engines, cab and bed choices, and the 2027 redesign
- Theft protection, the 6.2-liter V8 recall, safety, and Super Cruise
- Silverado vs. Sierra, F-150, Ram 1500, and Tundra, plus the Silverado EV
- Work trucks, towing, off-roading, and used Silverados by generation
- States where trucks rule, age and record, teens from 16 to 19, families, seniors, military, and 10 discounts
- Jump to your situation: owners worried about theft, go to the theft section; 2021 to 2024 6.2-liter owners, go to the recall section; business owners, go to the work truck section.
Chevrolet Silverado insurance at a glance
| Measure | Figure |
| 40-year-old good driver, Silverado 1500, Study B | $2,546 a year |
| Cheapest company, 2025 Silverado 1500, Study A | Travelers, $1,865 a year |
| Company average, 2025 Silverado 1500, Study A | $2,629 a year |
| Average, all model years, $1,000 deductible, Study E | $158 a month |
| Cheapest company, all model years, Study E | GEICO, $125 a month |
| Silverado EV, 40-year-old, Study B | $2,833 a year |
| Teen driver average, Study D | $8,878 a year |
| Overall loss index, Study C | 101 (about average) |
| NICB 2025 most-stolen rank | No. 4 |
| 2026 starting price, WT | $39,495 with destination |
Full coverage unless noted. Study A prices a 40-year-old with a $500 deductible. The Sources section names every study in full.
Silverado 1500 insurer prices: national and Florida samples
Study A provides eight insurers in its national comparison for a 2025 Silverado 1500. UAIC and Mercury appear only in a separate Florida Silverado Custom sample, so those two companies should not be ranked against the national rates. The study assumes a 40-year-old with 100/300/100 limits and a $500 deductible.
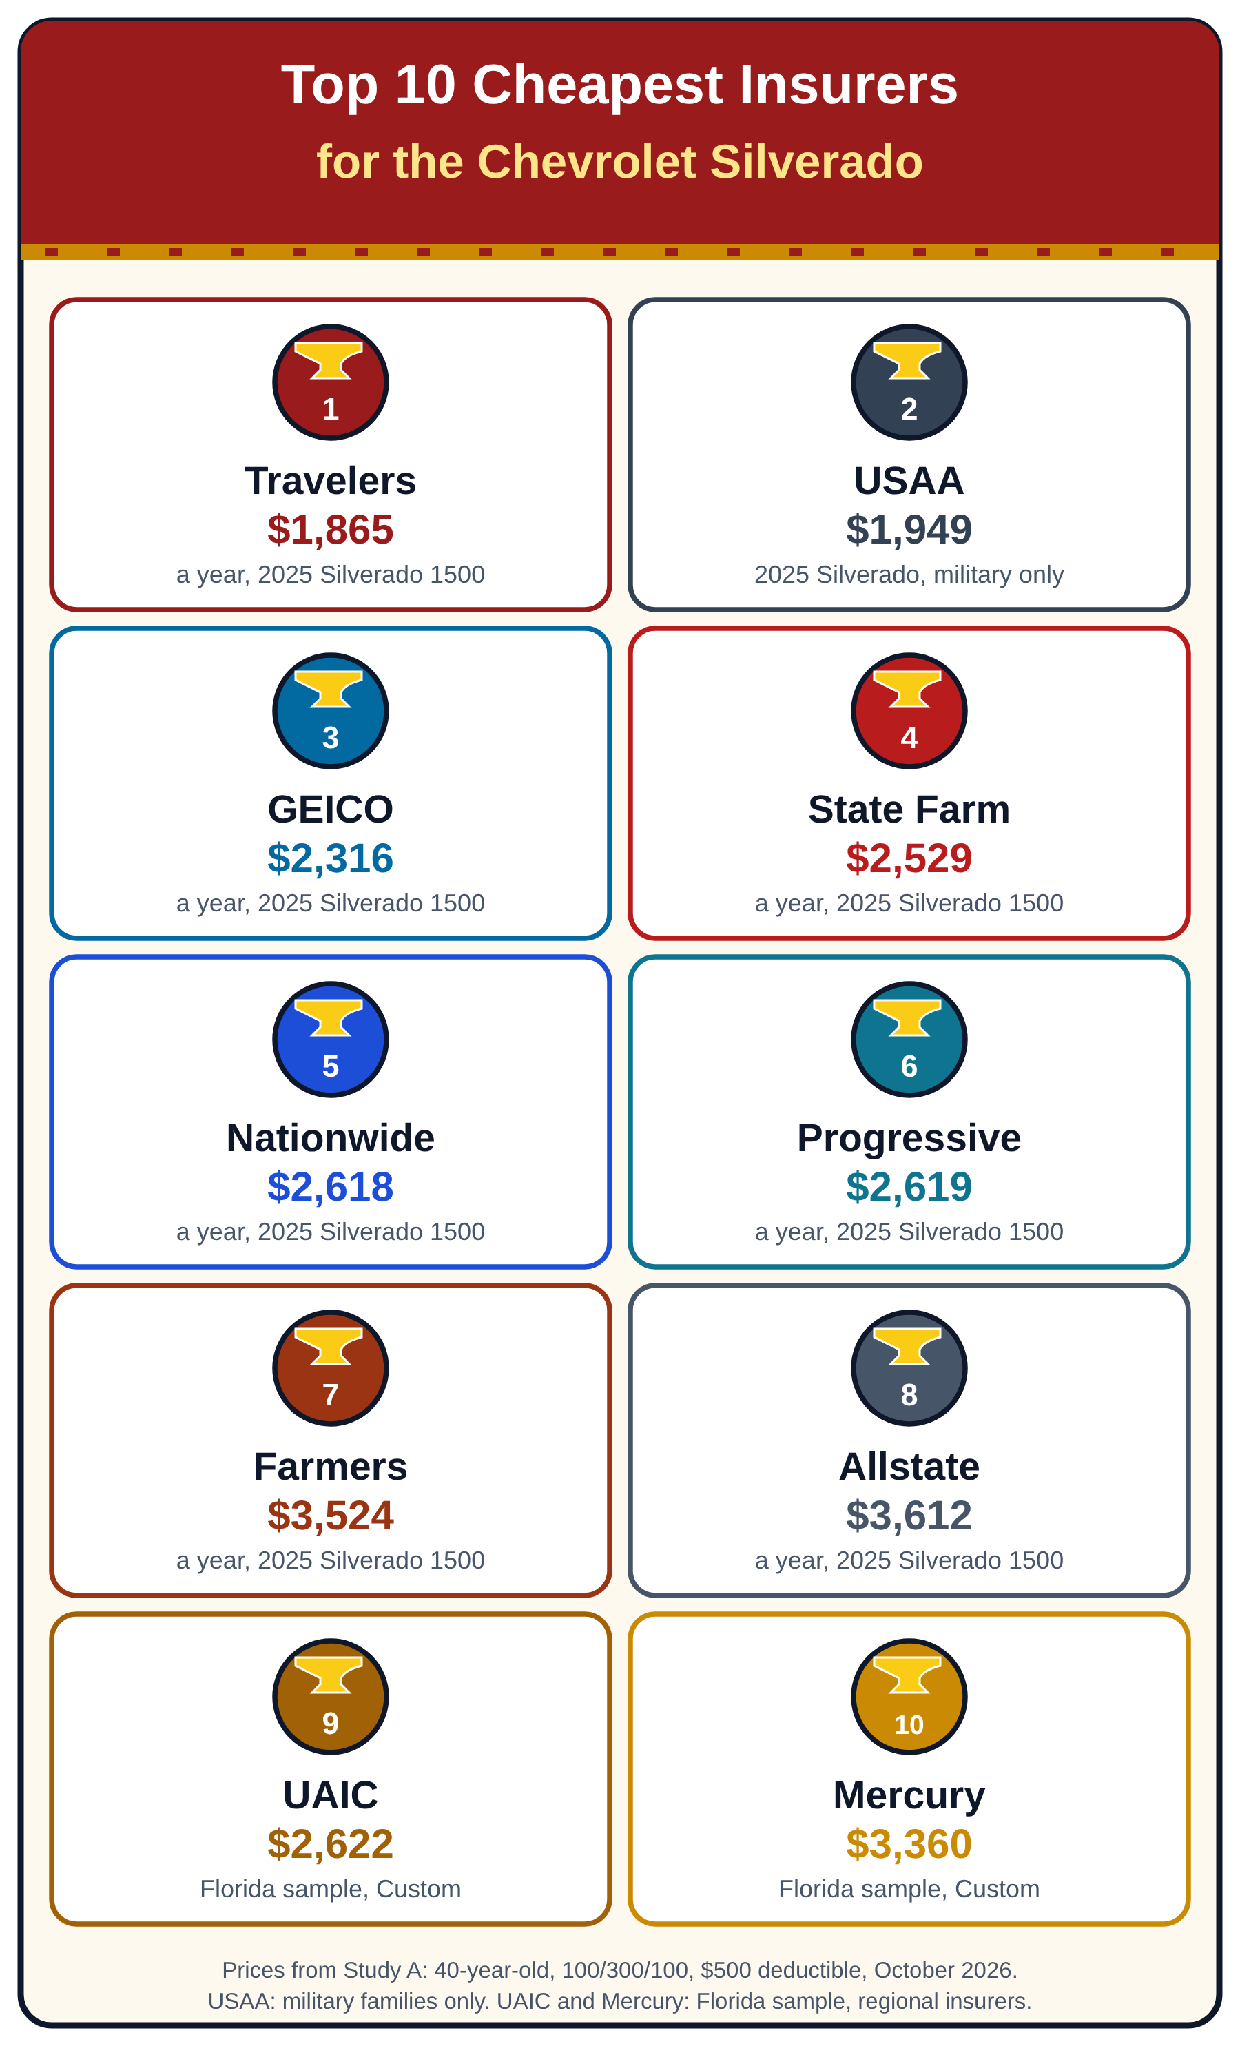
Comparison limitation: The original image is retained for context. Do not treat the national insurer sample and Florida-only companies as a unified ranking; compare quotes within the same study and state.
Original illustration combines eight national-sample insurers with two Florida-only entries. These prices are not a valid unified top-10 ranking.
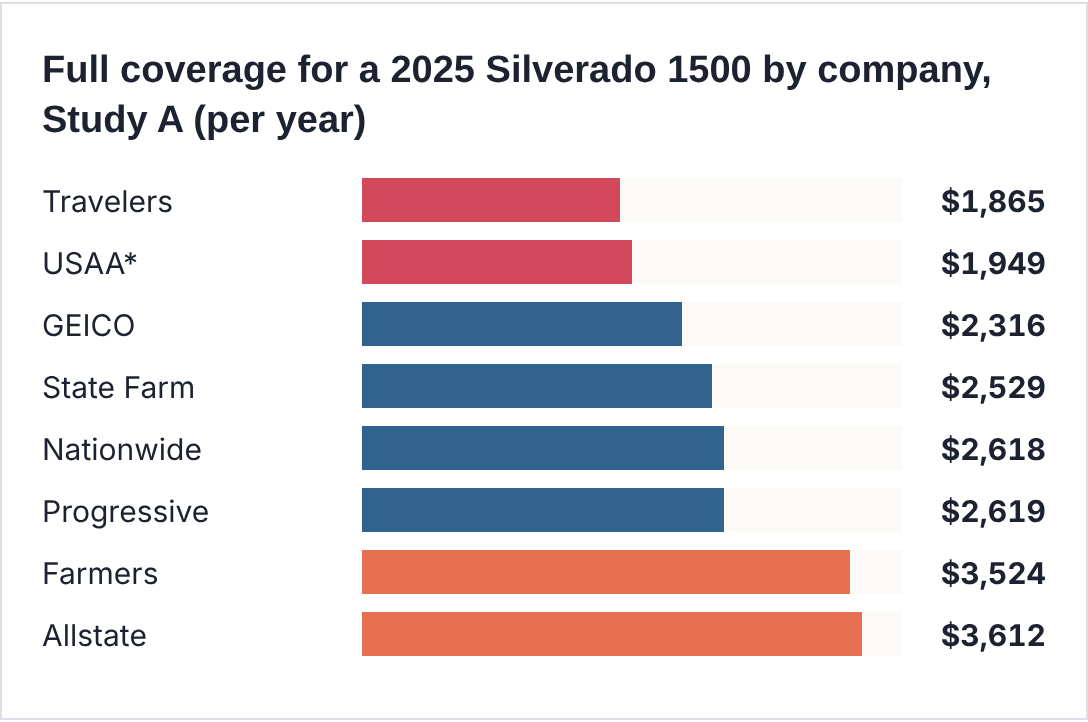
40-year-old, 100/300/100, $500 deductible. *USAA sells only to military families. Source: Study A, Chevrolet Silverado 1500 car insurance, October 26, 2026.
Travelers is $84 below USAA for a 2025 Silverado 1500 in Study A, subject to USAA eligibility. Nationwide and Progressive are a dollar apart, and Farmers and Allstate both charge nearly twice what Travelers does.
1. Travelers
Travelers charges $1,865 a year for a 2025 Silverado 1500, $764 below Study A's company average of $2,629. It is the cheapest company of all for every model year from 2020 to 2025, and second in Study E at $129 a month. In Study E's 2025 prices, it also has the lowest full-coverage rate, at $194 a month.
2. USAA
USAA charges $1,949 for a 2025 Silverado 1500 and is the cheapest company of all for 2018 and 2019 models in Study A. It earned the top J.D. Power satisfaction score in every region in 2026. Only military members, veterans, and their families can buy it.
3. GEICO
GEICO charges $2,316 for a 2025 Silverado 1500 in Study A but is the cheapest company in Study E across all model years, at $125 a month for full coverage and $58 for minimum coverage.
4. State Farm
State Farm charges $2,529 for a 2025 Silverado 1500 and is the cheapest company in Study A's Florida sample at $2,075. For older trucks it stays close to GEICO, at $1,996 for a 2018.
5. Nationwide
Nationwide charges $2,618 for a 2025 Silverado 1500 but is the cheapest company in Study D, at $1,886 a year for a 40-year-old. It placed second in J.D. Power's October 2026 claims study.
6. Progressive
Progressive charges $2,619 for a 2025 Silverado 1500 in Study A but is the cheapest company for a 2025 in Study F, at $1,705 for a 30-year-old. It is also one of the largest commercial auto insurers, useful for work trucks.
7 and 8. Farmers and Allstate
Farmers charges $3,524 and Allstate $3,612 for a 2025 Silverado 1500, the two highest national prices in Study A. Allstate is the most expensive company in every model year of Study F as well.
9 and 10. UAIC and Mercury
UAIC charged $2,622 and Mercury $3,360 in Study A's Florida sample, both cheaper there than Progressive, Allstate, and Farmers.
Florida's order
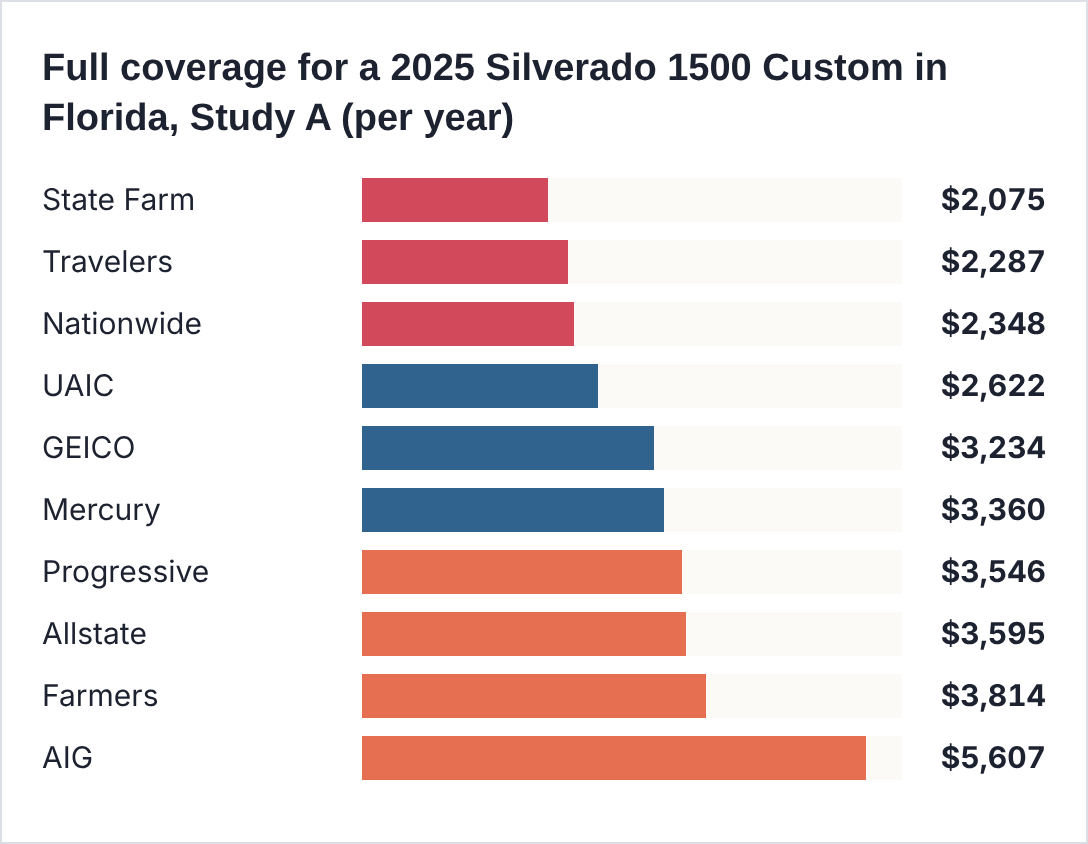
40-year-old, 100/300/100, $500 deductible. Source: Study A, Florida sample, October 26, 2026.
In Florida, State Farm had the lowest rate in this Florida sample, with Travelers second. Florida drivers should also distinguish the annual premium from Florida car insurance initial payment requirements. AIG charges $3,532 more than State Farm for the same Silverado Custom, about 2.7 times as much.
PRO TIP #1
Give every insurer your exact trim, cab, bed length, and engine. A Regular Cab WT and a Crew Cab ZR2 share a name, but Study E prices them $149 a month apart.
Bottom line: Quote Travelers, GEICO, and State Farm first, add USAA if you serve, and add Nationwide for its claims record.
The cheapest company for each Silverado model year
Travelers was the least expensive broadly available company among those shown by Study A for the 2018–2025 model years. USAA was cheaper in 2018 and 2019 for eligible customers; Travelers led the sample from 2020 to 2025.
Silverado 1500 full coverage by company and model year, Study A (per year)
| Insurer | 2025 | 2024 | 2022 | 2020 | 2018 |
| Travelers | $1,865 | $1,895 | $1,841 | $1,709 | $1,701 |
| USAA* | $1,949 | $2,138 | $1,940 | $1,770 | $1,659 |
| GEICO | $2,316 | $2,282 | $2,165 | $2,008 | $1,892 |
| State Farm | $2,529 | $2,324 | $2,166 | $2,051 | $1,996 |
| Nationwide | $2,618 | $2,558 | $2,678 | $2,712 | $2,413 |
| Progressive | $2,619 | $2,625 | $2,552 | $2,401 | $2,314 |
| Farmers | $3,524 | $3,452 | $3,282 | $3,057 | $2,843 |
| Allstate | $3,612 | $3,516 | $3,310 | $2,909 | $2,745 |
| Average | $2,629 | $2,599 | $2,492 | $2,327 | $2,195 |
40-year-old, 100/300/100, $500 deductible. *USAA sells only to military families. Study A's headline table shows higher averages, such as $2,724 for a 2025; we use the averages from its company tables. Source: Study A, October 26, 2026.
State Farm shows the biggest jump for a 2025 truck, $205 above a 2024, so it is relatively better value on older Silverados. Nationwide charges more for a 2020 than for a 2025.
A second view: Study F
Study F prices a 30-year-old man with a clean record across 15 model years. American Family and Progressive lead in most recent years, and Allstate is the most expensive company in every year.
Silverado 1500 full coverage by company, selected years, Study F (per year)
| Insurer | 2025 | 2023 | 2021 | 2019 | 2016 |
| Progressive | $1,705 | $1,679 | $1,594 | $1,425 | $1,501 |
| American Family | $1,754 | $1,556 | $1,532 | $1,454 | $1,370 |
| USAA* | $1,802 | $1,769 | $1,641 | $1,500 | $1,351 |
| Erie | $1,973 | $1,863 | $1,706 | $1,600 | $1,526 |
| Nationwide | $1,975 | $2,034 | $2,327 | $2,265 | $2,311 |
| State Farm | $2,434 | $2,186 | $1,995 | $1,864 | $1,817 |
| GEICO | $2,636 | $2,430 | $2,269 | $2,073 | $1,800 |
| Farmers | $3,319 | $2,991 | $2,703 | $2,536 | $2,163 |
| Allstate | $4,188 | $3,737 | $2,862 | $2,696 | $2,369 |
| Average | $2,508 | $2,341 | $2,145 | $1,997 | $1,850 |
30-year-old man, clean record, full coverage. *USAA sells only to military families. Source: Study F.
The cheapest companies in Studies D and E
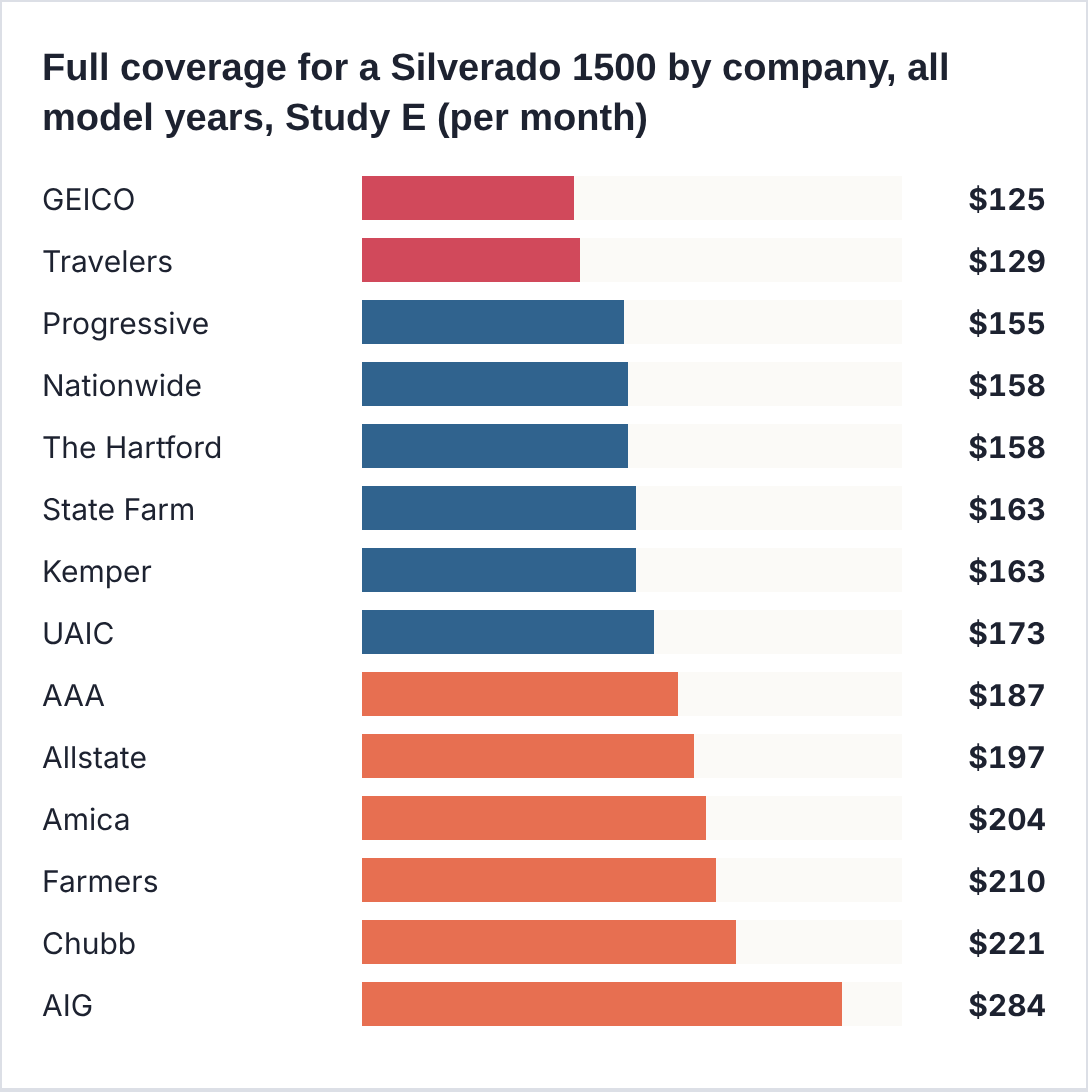
40-year-old, 100/300/100, $1,000 deductible, all model years. Source: Study E, May 21, 2026.
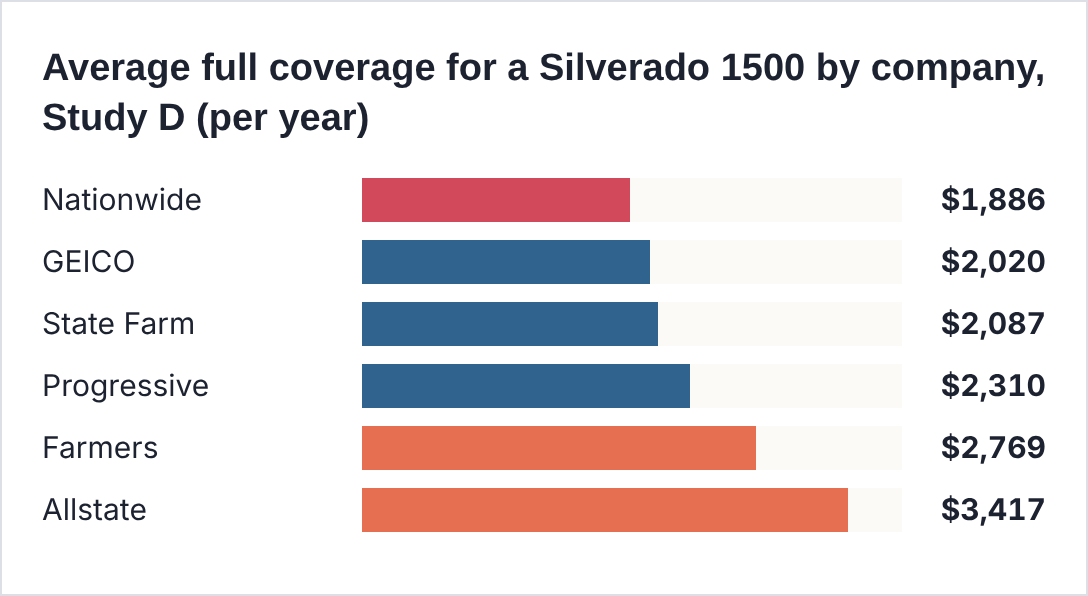
40-year-old, 100/300/100, $500 deductible; six companies published. Source: Study D, Chevrolet Silverado 1500 car insurance cost.
The studies select different low-price insurers because their sample drivers, coverage assumptions and model-year mixes differ. Travelers, GEICO, Nationwide and Progressive are useful quote candidates, but no nationwide order applies to every driver.
The best Silverado insurers for service
Service and financial ratings for Silverado insurers
| Insurer | J.D. Power 2026 range | AM Best | NAIC complaint index |
| USAA* | 707 to 763 | A++ | 1.18 |
| Erie | 652 to 704 | A+ | 0.89 |
| Nationwide | 612 to 685 | A | 0.63 |
| State Farm | 632 to 669 | A++ | 0.79 |
| GEICO | 631 to 668 | A++ | 0.69 |
| American Family | 632 to 649 | A | 0.33 |
| Travelers | 584 to 657 | A++ | 0.52 |
| Progressive | 604 to 645 | A+ | 0.71 |
| Allstate | 612 to 660 | A+ | 1.10 |
| Farmers | 558 to 675 | A | 0.86 |
J.D. Power regional ranges on a 1,000-point scale; the 2026 study average is 644. NAIC index below 1.00 means fewer complaints than expected. *USAA sells only to military families. Sources: J.D. Power 2026 U.S. Auto Insurance Study; Study D.
Travelers pairs the lowest Silverado prices with an A++ rating and a complaint index of 0.52. Nationwide, the cheapest company in Study D, scored 743 in J.D. Power's October 2026 claims study, second only to Amica's 775, against an average of 700. American Family, a leader in Study F, has the lowest complaint index in the table at 0.33.
Best for each kind of Silverado owner
- Lowest price on a 2020 to 2025 truck: Travelers.
- A $1,000 deductible: GEICO.
- Florida drivers: State Farm.
- Military families: USAA.
- Claims service: Nationwide, or Amica where it sells.
- Drivers around 30: Progressive or American Family.
Bottom line: Compare multiple insurers using matching limits and deductibles. Do not rule out Allstate, Farmers or a regional carrier solely because of one modeled sample.
What a Silverado costs to insure across the studies
For a new Silverado 1500 and a 40-year-old driver, three studies range from $2,546 to $2,928 a year. Across all model years, averages fall to $1,899 in Study E and $2,413 in Study D.
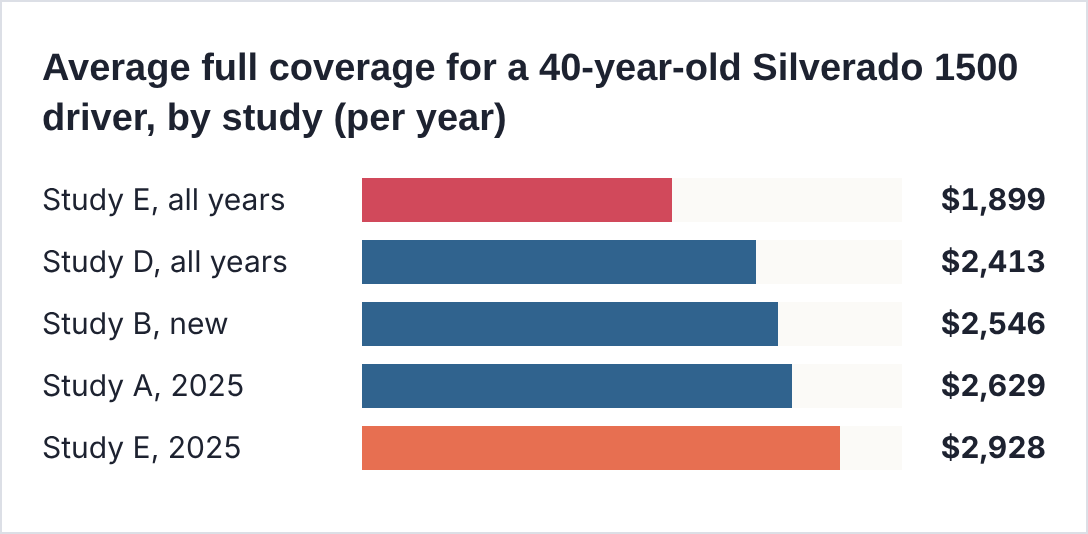
Each study uses its own driver, limits, and deductible. Study E 2025 figure is our multiplication of $244 a month. Sources: Studies A, B, D, and E.
Study C, which applies insurance-loss data to a national average premium rather than pricing a driver, estimates $1,455 a year. Treat that as a way to compare vehicles, not as a quote.
Minimum coverage costs about half as much. Study E puts state-minimum liability at $82 a month, or $980 a year, with GEICO cheapest at $58 a month and Travelers next at $70.
Bottom line: Published samples for a 40-year-old vary substantially; an actual quote can fall outside their ranges. Prices below $2,000 in particular studies are not guaranteed to be available locally.
Find your Silverado insurance price
Chevrolet Silverado insurance price finder
| Your situation | Typical price | Source |
| Age 40, new Silverado 1500, good driver | $2,546 a year | Study B |
| Age 40, 2025 Silverado 1500, cheapest company | Travelers, $1,865 a year | Study A |
| Age 40, 2025 Silverado 1500, military family | USAA, $1,949 a year | Study A |
| Age 40, 2018 Silverado 1500, cheapest open to all | Travelers, $1,701 a year | Study A |
| Age 30, 2025 Silverado 1500, cheapest company | Progressive, $1,705 a year | Study F |
| Age 40, one at-fault accident | $3,739 a year | Study B |
| Age 40, poor credit | $4,374 a year | Study B |
| Age 40, minimum coverage | $82 a month | Study E |
| Age 40, Silverado WT | $2,276 a year | Study D |
| Age 40, Silverado High Country | $2,567 a year | Study D |
| Age 40, Silverado EV | $2,833 a year | Study B |
| Age 25, good driver | $3,629 a year | Study B |
| Age 18, good driver | $8,037 a year | Study B |
| Teen driver average | $8,878 a year | Study D |
| Texas, average | $3,526 a year | Study D |
| Florida, 2025 Custom, cheapest company | State Farm, $2,075 a year | Study A |
Full coverage unless noted. Study A: 40-year-old, $500 deductible. Study B: new vehicle, good credit unless noted. Study D: 40-year-old, $500 deductible. Study E: $1,000 deductible. Study F: 30-year-old man.
Five example Silverado drivers
EXAMPLE DRIVER 1: THE NEW-TRUCK BUYER
A 40-year-old with a clean record buys a 2025 Silverado 1500. In Study A, Travelers charges $1,865 a year and Allstate $3,612, so comparing quotes saves $1,747 a year on the same coverage.
EXAMPLE DRIVER 2: THE HIGH COUNTRY BUYER
The same driver chooses a $65,495 High Country instead of a $50,495 LT. Study D puts the High Country at $2,567 against $2,415 for the LT, only $152 a year more for a truck that costs $15,000 more.
EXAMPLE DRIVER 3: THE TEXAS CONTRACTOR
A Texas owner uses a Silverado WT for personal driving and occasional jobs. Study D's Texas average is $3,526 a year, among the highest in that study. Texas auto insurance payment-plan rules are a separate consideration. If the truck becomes a business vehicle, a commercial policy may be needed.
EXAMPLE DRIVER 4: THE USED-TRUCK BUYER
A 40-year-old buys a 2021 Silverado 1500. Study E's average is $161 a month, the lowest of any year from 2016 to 2025, against $244 for a 2025, and Travelers charges $1,753 a year in Study A.
EXAMPLE DRIVER 5: THE FAMILY ADDING A TEEN
Parents add a 17-year-old who will drive the family Silverado. National data in Study D puts the average cost of adding a 17-year-old to a family policy at $3,740 a year, far below the $8,878 Study D lists as the average teen premium on a Silverado 1500.
Silverado 1500 trim cards: WT to ZR2
Study D prices nine Silverado 1500 trims, and the spread is narrow: from $2,276 a year for a WT to $2,567 for a High Country, just $291 apart even though the trucks differ by more than $25,000 in price.
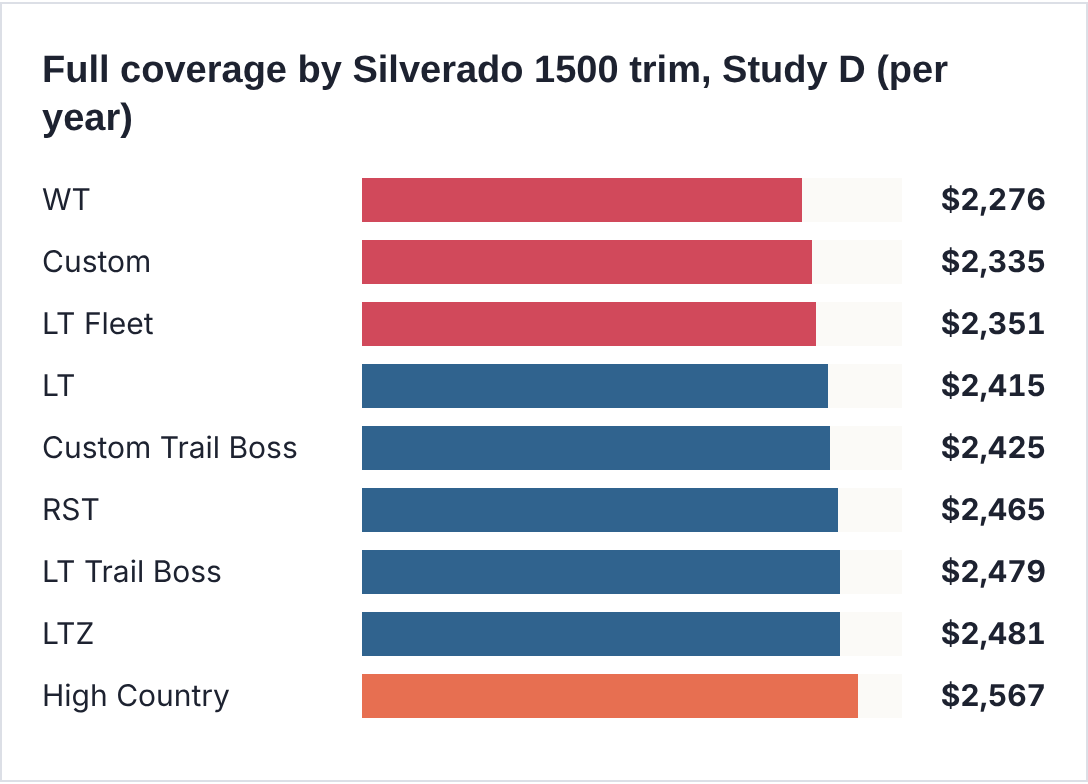
40-year-old, 100/300/100, $500 deductible. The ZR2 is not priced in this study. Source: Study D, Chevrolet Silverado 1500 car insurance cost.
TRIM CARD: WT (WORK TRUCK)
Price: $39,495 with destination for 2026. Insurance: $2,276 a year in Study D, the cheapest trim. The truck for job sites and fleets; if it is used for business, see the work truck section below.
TRIM CARD: CUSTOM
Price: $44,995. Engine: the 2.7-liter TurboMax, 310 horsepower and 430 lb-ft of torque. Insurance: $2,335 a year in Study D, and the trim Study A uses in its Florida sample.
TRIM CARD: LT
Price: $50,495. Insurance: $2,415 a year in Study D. The volume trim for many buyers, and the one the 2027 lineup renames simply "Silverado."
TRIM CARD: RST
Price: $53,895. Insurance: $2,465 a year in Study D. The street-styled trim; the 2026 RST Select package adds 20-inch wheels and all-terrain tires.
TRIM CARD: CUSTOM TRAIL BOSS AND LT TRAIL BOSS
Price: $55,395 and $62,195. Insurance: $2,425 and $2,479 a year in Study D. Off-road trims with a factory lift; tell your insurer about any added accessories.
TRIM CARD: LTZ
Price: $60,595. Insurance: $2,481 a year in Study D, just $2 more than the LT Trail Boss.
TRIM CARD: HIGH COUNTRY
Price: $65,495. Insurance: $2,567 a year in Study D, the most expensive trim it prices. On a loan this size, gap insurance is worth pricing.
TRIM CARD: ZR2
Price: $74,295 for 2026, the most expensive Silverado 1500, with a Multi-Flex tailgate and technology package now standard. Insurance: Study E puts a Crew Cab ZR2 at $326 a month with the short bed, the highest of any configuration it lists. Off-road use and modifications should be disclosed.
2026 prices include $2,595 destination, from a 2026 Silverado pricing report listed in Sources. Study D trim prices cover several model years.
Which engine is cheapest to insure?
The 2026 Silverado 1500 offers four engines: the 2.7-liter TurboMax four-cylinder, a 5.3-liter V8, a 6.2-liter V8, and a 3.0-liter Duramax turbodiesel. No study found prices for them separately, so the engine affects your premium mostly through the trim and price it comes with.
- 2.7-liter TurboMax: standard on lower trims such as the Custom, so it usually comes with the lowest-priced, lowest-premium trucks.
- 5.3-liter V8: the mainstream V8 on many trims.
- 6.2-liter V8: found on upper trims, and the engine behind the 2021 to 2024 recall covered below. An engine failure from a manufacturing defect is a recall repair, not an insurance claim.
- 3.0-liter Duramax diesel: adds to the purchase price, which raises the value collision and comprehensive must cover.
For 2027, the 5.3-liter and 6.2-liter V8s give way to new 5.7-liter and 6.6-liter V8s, while the 2.7-liter TurboMax and 3.0-liter Duramax continue.
Cab and bed: how configuration changes the price
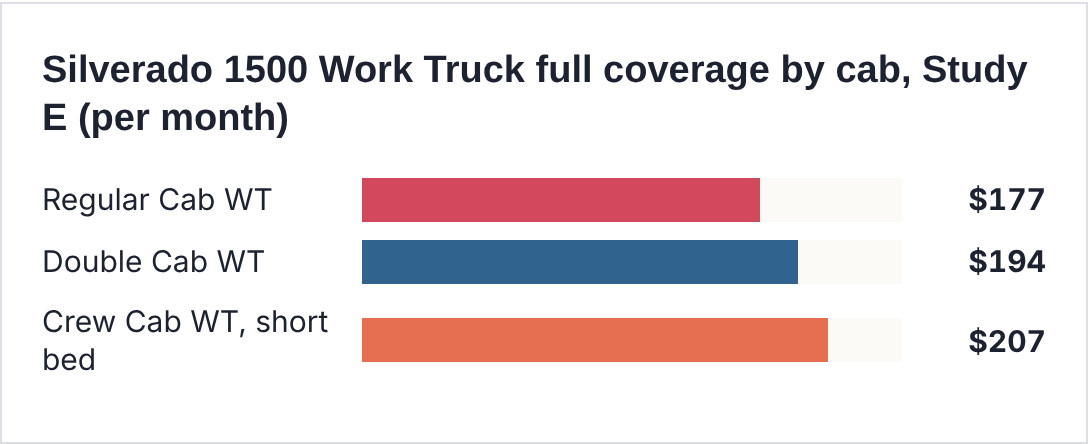
Study E prices Silverado 1500s by cab and bed, and the pattern is clear for the Work Truck: a bigger cab costs more to insure.
40-year-old, 100/300/100, $1,000 deductible. Source: Study E, May 21, 2026.
Moving from a Regular Cab to a Crew Cab WT adds $30 a month, or $360 a year. Bed length matters too, though not always the way you would expect: Study E prices a Crew Cab High Country with the 6.5-foot bed at $197 a month but with the 5.75-foot bed at $294, and the LT Trail Boss shows a similar gap. Study E does not explain the gap, so quote the exact cab and bed you plan to buy.
Bottom line: Trim adds less than you might expect, the ZR2 is the exception, and a Regular Cab WT is the cheapest Silverado 1500 to insure.
Silverado theft: the coverage and habits that protect you
The Silverado 1500 ranked fourth by total thefts in the United States in 2025, with 16,764 thefts, according to the National Insurance Crime Bureau, behind the Hyundai Elantra, Honda Accord, and Hyundai Sonata and ahead of the Ford F-150 in seventh. Thefts nationally fell 23% in 2025 to 659,880, a historic low, but the Silverado remains one of the most targeted pickups.
NICB's 10 most-stolen vehicles of 2025
| Rank | Vehicle |
| 1 | Hyundai Elantra |
| 2 | Honda Accord |
| 3 | Hyundai Sonata |
| 4 | Chevrolet Silverado 1500 |
| 5 | Honda Civic |
| 6 | Kia Optima |
| 7 | Ford F-150 |
| 8 | Toyota Camry |
| 9 | Honda CR-V |
| 10 | Nissan Altima |
NICB ranks vehicles by total thefts, not theft rate, so popular models appear more often. Source: National Insurance Crime Bureau, March 18, 2026 report. Rankings count thefts, not thefts per registered vehicle.
Theft risk and insurance cost are not the same thing. Study C's comprehensive loss index for the Silverado, which captures theft, vandalism, fire, and weather, is 78, meaning those claims cost insurers 22% less per insured vehicle than average. Because NICB counts total thefts and the Silverado is one of the best-selling vehicles in the country, a high theft ranking can sit alongside below-average comprehensive losses.
Coverage that matters for theft
- Comprehensive coverage: the only part of a standard policy that pays if your truck, its wheels, or its tailgate is stolen. Keep it on any Silverado you could not replace with cash.
- Custom equipment coverage: lift kits, aftermarket wheels, light bars, and bed covers may not be fully covered unless you list them.
- Rental reimbursement: a stolen truck can take weeks to recover or settle, so this add-on keeps you on the road.
- Tools and cargo: auto insurance usually does not cover tools in the bed or cab; a homeowners, renters, or business policy may.
Habits and devices that cut the risk
- Park in a garage or well-lit area, and never leave the key fob in the truck.
- Use a steering wheel lock, a tailgate lock, and wheel locks.
- Consider a GPS tracker, and turn on any connected-vehicle tracking your truck offers.
- Etch the vehicle identification number on windows and record serial numbers of accessories.
- Ask your insurer about anti-theft device discounts; GEICO and other insurers list them, and rules vary by state.
PRO TIP #2
Photograph your truck, its wheels, and every accessory, and keep receipts in a cloud folder. If the Silverado is stolen, that record speeds up the claim and supports the value of add-ons.
Bottom line: Theft rankings justify checking comprehensive insurance and aftermarket-equipment limits, but whether the coverage is worth its cost depends on the truck’s value, deductible and the owner’s ability to absorb a loss.
The 6.2-liter V8 recall and what it means for insurance
In May 2025, GM recalled about 597,571 full-size trucks and SUVs built from March 2021 to May 2024 with the 6.2-liter V8, including about 107,244 2021 to 2024 Silverado 1500s. The connecting rods or crankshaft may have manufacturing defects that can lead to engine failure and a loss of power while driving. GM reported 28,102 related complaints or incidents in the United States, 14,332 of them alleging a loss of propulsion.
The remedy is an inspection: engines that fail it are repaired or replaced, and those that pass get higher-viscosity oil, a new oil filter, and a new oil fill cap, all free. Federal scrutiny continued after the recall: in August 2026, NHTSA expanded its engineering investigation into engine failures, including reported failures after recall work. The investigation population is broader than the vehicles included in recall 25V-274. Check the VIN for open recalls rather than assuming every investigated vehicle is recalled.
What this means for you
- A manufacturer recall remedy is provided without charge to eligible owners. Mechanical wear or defects ordinarily are not covered by collision or comprehensive insurance; coverage for resulting crash damage depends on the policy and facts.
- If an engine failure contributes to a crash, liability or collision coverage may apply depending on fault, policy terms and exclusions; do not assume every resulting loss is covered.
- Warning signs include knocking or banging noises, a check engine light, hesitation, abnormal shifting, or a no-start condition. Stop driving and contact a dealer if you notice them.
- If you are buying a used 2021 to 2024 Silverado with the 6.2-liter, ask for proof the recall was done and check the vehicle identification number on NHTSA's recall lookup.
Bottom line: If your 2021 to 2024 Silverado has the 6.2-liter V8, get the recall inspection done and watch for warning signs, even after the repair.
How safe is the Silverado 1500?
NHTSA and IIHS paint very different pictures. NHTSA gives the 2025 Silverado 1500 five stars overall, while IIHS rates it Poor in the updated moderate overlap test and Poor for headlights.
Safety ratings for the 2025 Chevrolet Silverado 1500
| Test | Rating |
| NHTSA overall | 5 stars |
| NHTSA frontal crash | 5 stars |
| NHTSA side crash | 5 stars |
| NHTSA rollover | 4 stars, 19.1% rollover risk |
| IIHS small overlap front | Marginal |
| IIHS moderate overlap front | Poor |
| IIHS side | Acceptable |
| IIHS headlights | Poor |
| IIHS pedestrian front crash prevention | Acceptable |
| IIHS child seat anchors | Marginal |
| IIHS award | None |
Source: NHTSA and IIHS ratings as compiled in the safety source listed in Sources.
The IIHS results matter most for rear-seat passengers and night driving. Study C's bodily injury loss index for the Silverado is 115, meaning injury claims for other people run 15% above average, which makes solid liability limits worth carrying. The 2027 redesign may change these results, so check new ratings when they are published.
Other recent Silverado recalls
RECALL TIMELINE
- May 2025: About 107,244 2021 to 2024 Silverado 1500s with the 6.2-liter V8 recalled for possible engine failure, part of a 597,571-vehicle campaign.
- November 2025: About 3,408 2026 Silverado 1500, 2500, and 3500 trucks recalled because they may not have received an owner's manual, which includes child seat anchor information. Dealers provide the manual.
- August 2026: NHTSA expanded an investigation of 6.2-liter L87 engine failures, including reports after recall work; investigation scope is not the same as recall coverage.
- 2026: About 66 2026 four-wheel-drive Silverado 1500s and GM SUVs recalled because a missing transfer case part can lock the wheels without warning. Owners are told not to drive until the repair is done.
Counts are totals for each campaign, which may include other GM models. Sources: NHTSA campaign records as compiled in the recall sources listed in Sources.
Super Cruise hands-free driving and insurance
Chevrolet offers Super Cruise hands-free driving on select Silverado 1500 trims, and the 2027 truck offers it with hands-free trailering. It works only under specified conditions and on compatible roads; the driver must remain attentive and ready to take over. We found no insurer that lists a discount for Super Cruise, and it does not change who is responsible behind the wheel: you are. If you have it, check that the camera and sensors are recalibrated after any windshield or front-end repair.
Bottom line: Five NHTSA stars but weak IIHS scores; carry strong liability limits, and get every recall done.
Silverado vs. GMC Sierra: does the badge change the price?
The Silverado 1500 and GMC Sierra 1500 share a platform and engines, and GM says the pair had their best combined sales in 20 years in 2025. In insurance-loss data, the Sierra comes out ahead: Study C gives it an overall index of 95 against the Silverado's 101, an estimated $95 a year less.
Study C does not explain the gap between two mechanically similar trucks. If you are choosing between them, quote both with the same company, trim level, and coverage.
Silverado vs. F-150, Ram 1500, and Tundra
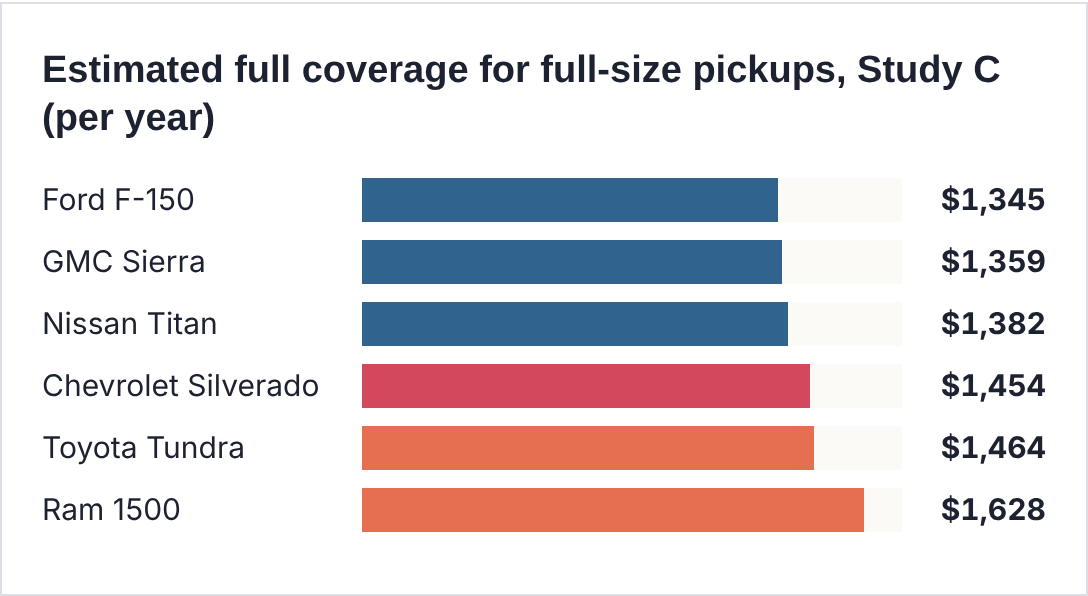
Loss-index estimates applied to a national average premium; not quotes. Study C does not say whether its Silverado figures cover light- or heavy-duty models. Source: Study C, November 2026.
Comparisons of insurance for Ford F-250, F-350 and F-450 trucks involve heavier-duty vehicles and should not be treated as directly interchangeable with Silverado 1500 rates. Among full-size pickups, the Silverado lands in the middle in Study C: $109 a year above the Ford F-150, about level with the Toyota Tundra, and $174 below the Ram 1500, which has the highest losses of the group. Overall, it ranks 15th of 22 pickups.
Full-size pickup sales and loss index
| Pickup | 2025 U.S. sales | Overall loss index, Study C |
| Ford F-Series (F-150 to F-450) | 828,832 | 94 (F-150) |
| Chevrolet Silverado 1500 | 362,909 | 101 (all Silverados) |
| GMC Sierra | 348,222 | 95 |
| Ram 1500 | Not published here | 113 |
| Toyota Tundra | Not published here | 102 |
Silverado 1500 figure covers the light-duty truck; F-Series and Sierra totals may include heavy-duty models. Sources: 2025 sales reports listed in Sources; Study C.
In Study B's rate estimates, a 40-year-old pays $2,546 a year for a Silverado 1500, $132 more than the $2,414 the same study gives for an F-150.
The Silverado vs. other Chevrolets
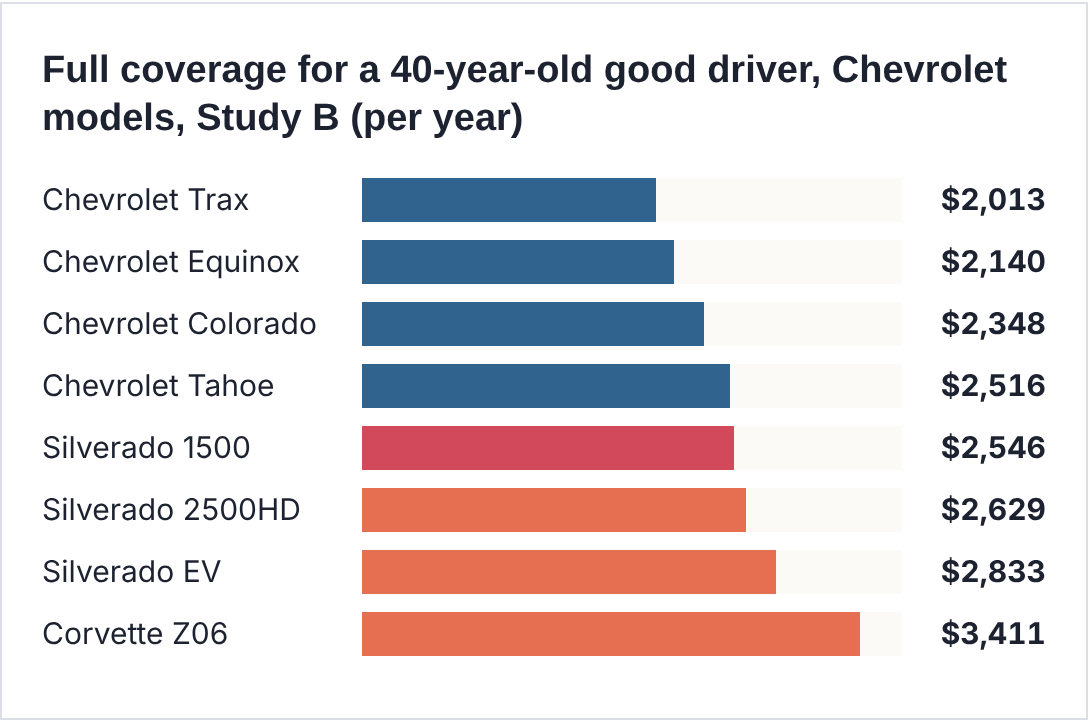
Estimates, not quotes; multi-vehicle discounts not included. Source: Study B.
A broader vehicle insurance cost comparison is useful when deciding whether you need a full-size pickup. The midsize Colorado costs $198 a year less to insure than the Silverado 1500 in Study B, and the heavy-duty 2500HD costs $83 more. If you do not need full-size capability, the Colorado is the cheaper Chevy pickup to insure.
Bottom line: The Silverado sits mid-pack among full-size pickups: above the F-150 and Sierra, below the Ram 1500.
What insurance-loss data says about the Silverado
Study C estimates an overall loss index of 101 for its Silverado grouping, approximately average, but the coverages tell two different stories.
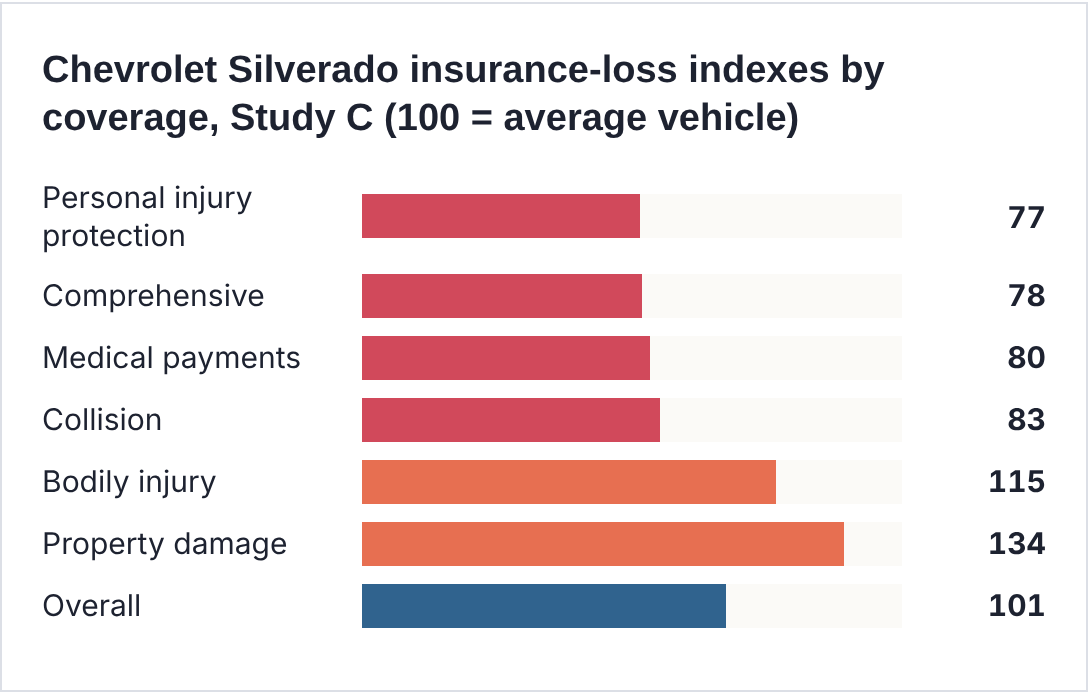
Lower is better. 2022 to 2024 models. Source: Study C, November 2026, citing Highway Loss Data Institute figures.
Damage to the Silverado itself costs insurers less than average: collision is 17% below and comprehensive 22% below. But claims for damage and injuries the truck causes to others run high, with property damage at 134 and bodily injury at 115. That puts the biggest share of Study C's $1,455 estimate on liability, at $698, against $407 for collision and $175 each for comprehensive and other coverages.
Understanding bodily injury and property damage liability limits helps interpret these loss data. The practical takeaway: liability limits matter on a Silverado. State minimums may not cover a serious crash with a full-size pickup, so 100/300/100 or higher, plus an umbrella policy if you have assets to protect, is worth pricing.
PRO TIP #3
Ask for quotes at 100/300/100 and 250/500/100. Compare the price difference with the added protection, since Silverado liability losses run above average.
The Silverado EV: insurance for Chevy's electric pickup
The Silverado EV costs more to insure than the gas Silverado 1500. Study B estimates $2,833 a year for a 40-year-old good driver, $287 more than the gas truck and $337 above its average for popular pickups.
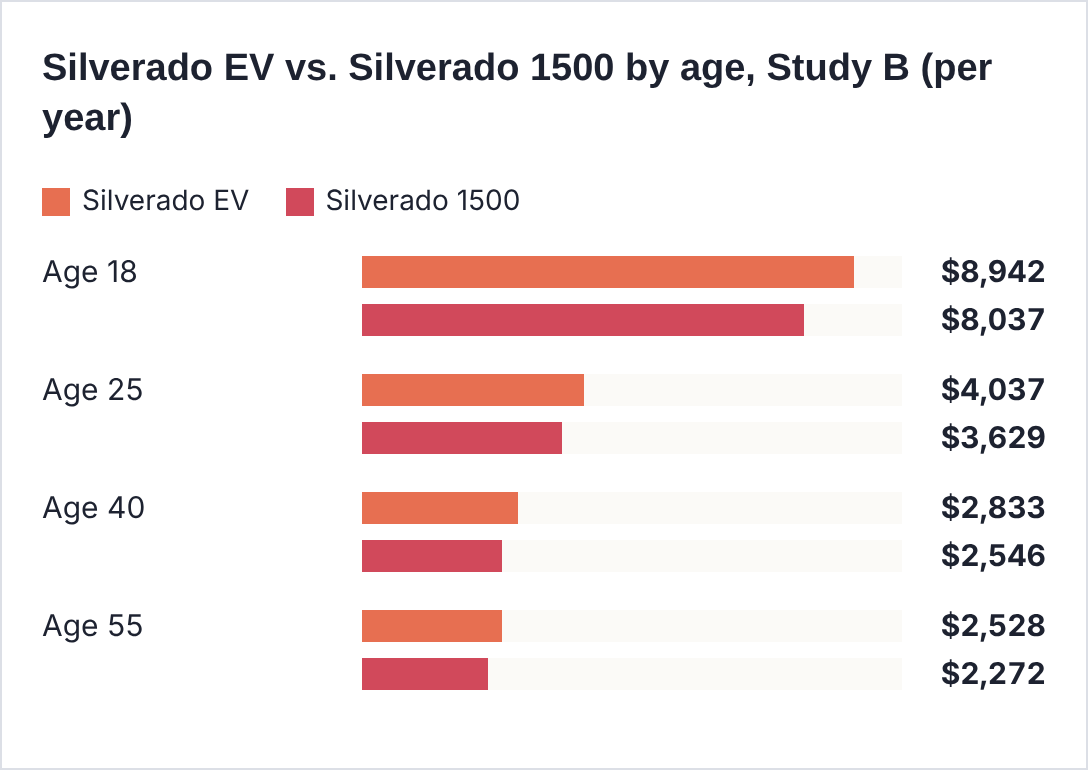
Good driver, good credit, new vehicle. Source: Study B.
2026 Silverado EV prices
| Trim and battery | Starting price |
| WT Standard Range | $54,895 |
| LT Standard Range | $62,995 |
| WT Extended Range | $68,295 |
| LT Extended Range | $71,195 |
| Trail Boss Extended Range | $72,095 |
| WT Max Range | $76,295 |
| Trail Boss Max Range | $88,695 |
| LT Max Range | $91,295 |
Prices include $2,095 destination. Source: 2026 Silverado EV pricing report listed in Sources.
With prices up to $91,295, battery choice changes the value insurers protect as much as trim does. Ask each insurer how it handles damage to the high-voltage battery, whether it uses EV-certified repair shops, and whether your home charger is covered by your home or auto policy. Travelers lists a hybrid and electric vehicle discount, and The Hartford's AARP program lists one too.
Bottom line: The Silverado EV costs about $290 a year more than a gas Silverado 1500 at 40; ask for EV discounts and battery coverage details.
Work trucks, fleets, and business use
Many Silverados, especially the WT, earn a living. A personal auto policy may limit or exclude business use, so tell your insurer how the truck is used.
- Personal policy: fits a truck used mostly for personal driving, with occasional hauling for yourself.
- Commercial policy: usually needed if a business owns the truck, employees drive it, or it carries tools, materials, or goods for paid work.
- Tools and equipment: commercial auto covers the truck, not the tools; an inland marine or business property policy usually covers those.
- Upfits: ladder racks, toolboxes, service bodies, and plows add value; list them so they are covered after a theft or crash.
- Hired and non-owned auto: covers your business when employees use their own vehicles for work.
Progressive and Travelers, two of the cheapest personal insurers for the Silverado, both also sell commercial auto coverage, which can make it easier to keep personal and business trucks with one company.
Towing and Max Trailering
The Silverado 1500 is built to tow, and towing changes what your policy needs to cover.
- Your liability coverage generally extends to a trailer while it is attached, but damage to the trailer itself usually needs its own policy or endorsement.
- Campers, boats, and horse trailers each need their own coverage, and the contents of a camper may need extra protection.
- Super Cruise, including hands-free trailering, is available on the 2027 Silverado; you remain responsible for the truck and trailer at all times.
- Ask whether roadside assistance covers a truck that is towing, and whether it will tow the trailer too.
Off-roading in a ZR2 or Trail Boss
The ZR2 and Trail Boss are built for trails, and the 2027 ZR2 adds 35-inch mud-terrain tires and front and rear locking differentials. Collision coverage may pay for trail damage, but policies differ, and some limit coverage for organized events. Lift kits, larger wheels and tires, winches, and light bars should be listed as custom equipment, with receipts.
PRO TIP #4
Before your first off-road trip or tow, call your insurer and ask three questions: is trail damage covered, is my trailer covered, and are my accessories listed? Get the answers in writing.
Bottom line: Match your policy to how you use the truck: work, towing, and off-roading each need specific coverage.
Silverado insurance by model year
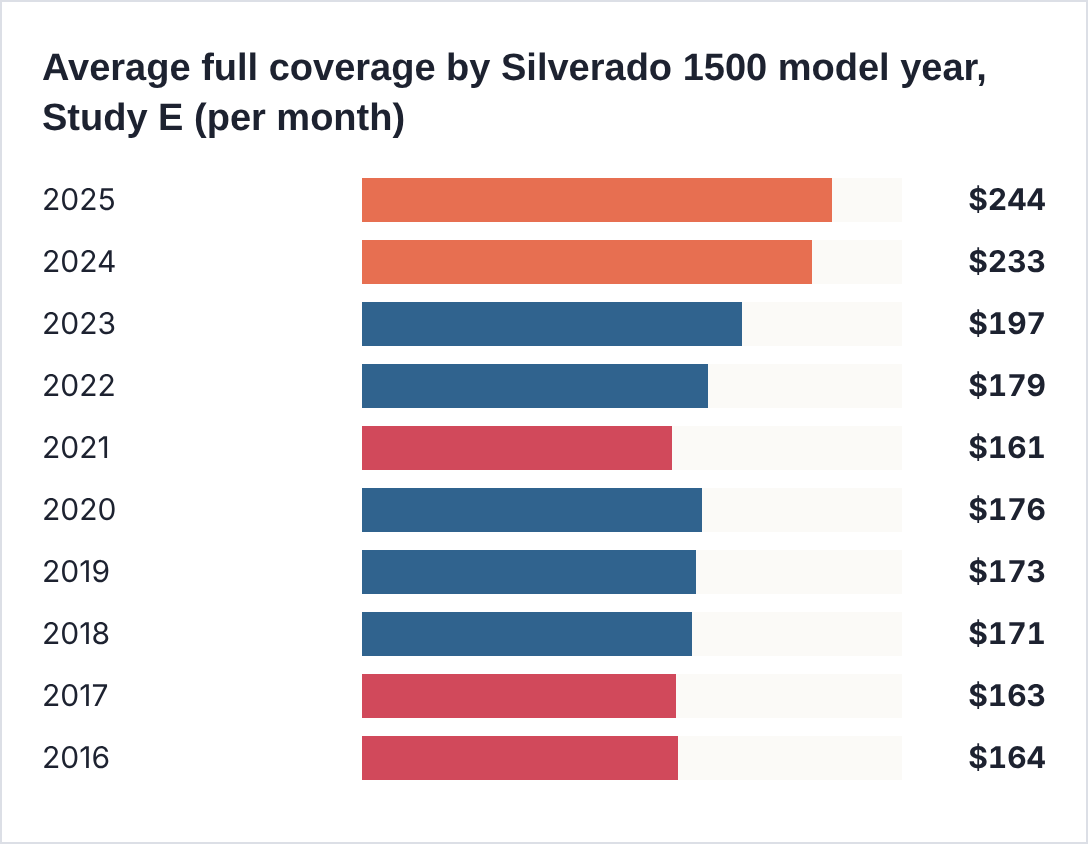
40-year-old, 100/300/100, $1,000 deductible. Source: Study E, May 21, 2026.
Study E shows a big step between a 2023 and a 2024 truck, $36 a month, and the 2021 is the cheapest year from 2016 on, at $161. Study A shows a steadier rise, from $2,195 for a 2018 to $2,629 for a 2025, and Study D from $1,756 for a 2014 to $2,456 for a 2023.
Buying a used Silverado? A guide by generation
2014 TO 2018
Study D prices these years from $1,756 to $2,055 a year, and Study F from $1,704 to $1,933 for a 30-year-old. USAA leads Study F in each of these years. Values are lower, so check whether collision and comprehensive still pay for themselves.
2019 TO 2021
The fourth-generation Silverado arrived for 2019. Study E prices these years from $161 to $176 a month, and Travelers charges $1,707 to $1,753 a year in Study A. The 2021 is the sweet spot for low premiums in Study E. Check whether a 2021 has the 6.2-liter V8 and, if so, whether the recall was done.
2022 TO 2026
The 2022 refresh brought a new interior and the ZR2. Study E prices 2022 to 2025 trucks from $179 to $244 a month, and Study A's average runs from $2,492 to $2,629. Check the 6.2-liter recall on 2022 to 2024 trucks.
2027 ONWARD: THE NEXT GENERATION
The redesigned 2027 Silverado 1500 brings new 5.7-liter and 6.6-liter V8s, a 16.3-inch screen in every trim, and a renamed lineup: WT, Custom, Custom Trail Boss, Silverado, Trail Boss, ZR2, and High Country. Chevrolet expected sales to begin before the end of 2026, with prices announced closer to launch. Quote by vehicle identification number once it arrives.
Liability-only vs. full coverage on a Silverado
Before dropping physical-damage protection, review the differences between liability, comprehensive and collision in car insurance coverage basics.
State-minimum liability costs $82 a month in Study E against $158 for full coverage. General full-coverage quotes under $150 a month use different driver and vehicle profiles, so they are not a Silverado-specific benchmark. It pays for damage you cause to others, not your own truck. With Silverado theft risk and truck values, keep collision and comprehensive on any truck you could not replace with cash; a lender requires them anyway. Given the Silverado's above-average liability losses, consider higher liability limits rather than the state minimum.
States where trucks rule: Silverado insurance by state
Study D publishes Silverado 1500 averages for every state. Louisiana is the most expensive at $3,934 a year, followed by Texas at $3,526, and Hawaii is the cheapest at $1,541. That is a gap of $2,393 a year for the same truck.
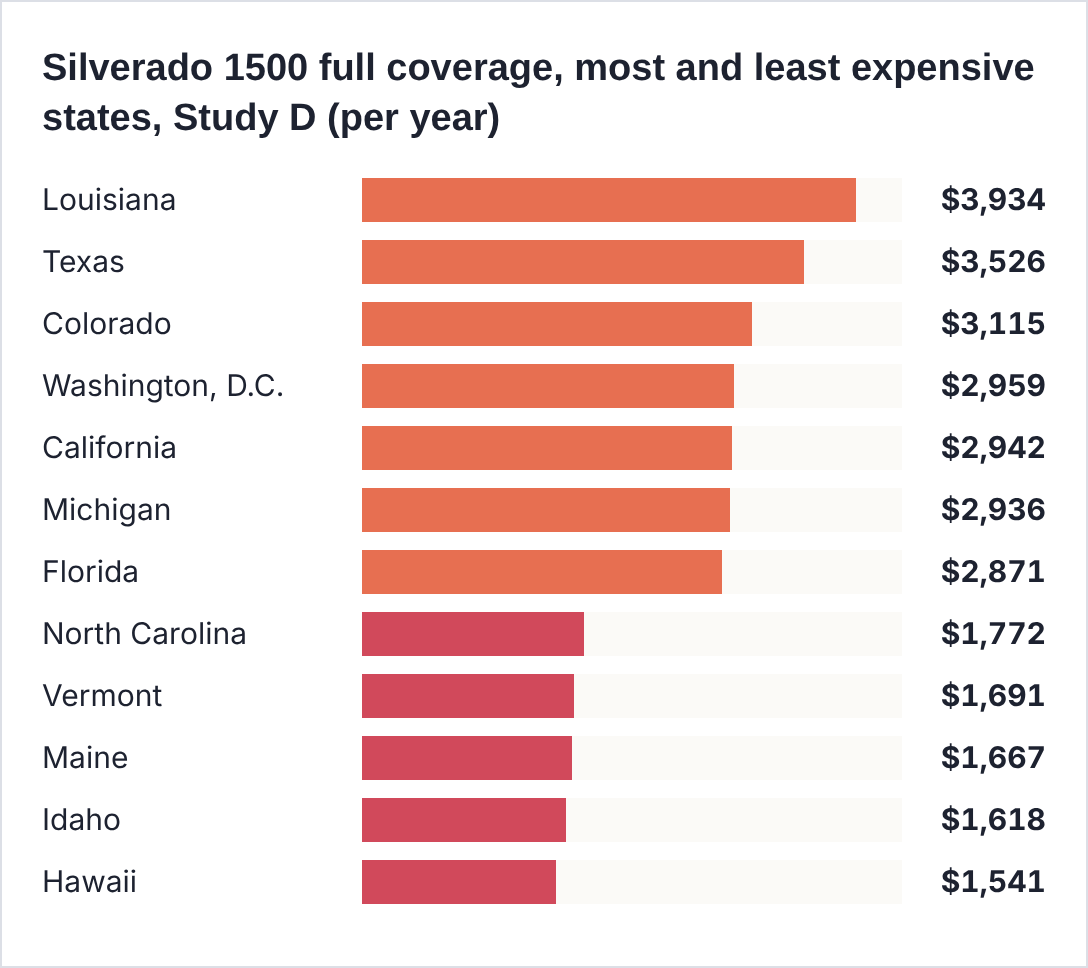
40-year-old, 100/300/100, $500 deductible. Source: Study D, Chevrolet Silverado 1500 car insurance cost.
Big pickup states
Silverado 1500 averages in major pickup states, Study D (per year)
| State | Average |
| Louisiana | $3,934 |
| Texas | $3,526 |
| Florida | $2,871 |
| Georgia | $2,870 |
| South Dakota | $2,869 |
| Kentucky | $2,863 |
| Missouri | $2,760 |
| Montana | $2,662 |
| Tennessee | $2,650 |
| Oklahoma | $2,611 |
| Alabama | $2,322 |
| Indiana | $2,235 |
Source: Study D. Every state's average is in the study listed in Sources.
Texas is the second most expensive state for a Silverado 1500 in Study D, $1,113 above the study's overall average of $2,413, and Louisiana tops the list by a wide margin. Several other Southern and Plains states, including Kentucky, Georgia, and South Dakota, sit between $2,860 and $2,870.
Silverado 1500 full coverage by state for a 40-year-old, Study B (per year)
| State | Good driver | One accident | Poor credit |
| Alabama | $2,698 | $3,918 | $4,987 |
| Alaska | $2,231 | $3,093 | $3,007 |
| Arizona | $2,523 | $3,647 | $5,373 |
| Arkansas | $2,766 | $4,346 | $4,785 |
| California | $3,079 | $5,446 | $3,079 |
| Colorado | $2,874 | $4,022 | $5,103 |
| Connecticut | $3,671 | $5,694 | $7,228 |
| Delaware | $3,039 | $4,051 | $5,203 |
| Florida | $3,619 | $5,007 | $6,524 |
| Georgia | $2,950 | $4,412 | $4,448 |
| Hawaii | $1,179 | $1,600 | $1,179 |
| Idaho | $2,047 | $2,714 | $3,300 |
| Illinois | $2,143 | $3,240 | $3,694 |
| Indiana | $2,202 | $3,366 | $3,777 |
| Iowa | $1,744 | $2,392 | $2,812 |
New vehicle, good credit unless noted. Study B publishes these 15 states. Source: Study B.
Study B's state figures show how much your profile adds on top of your address. In Connecticut, poor credit pushes a Silverado 1500 to $7,228 a year, and in California an at-fault accident adds $2,367. California and Hawaii show no credit penalty because both states bar insurers from using credit to set auto rates.
Bottom line: Louisiana and Texas are among the high-cost states in Study D; other data sets and individual ZIP codes can produce a different order.
How age, accidents, and credit change a Silverado premium
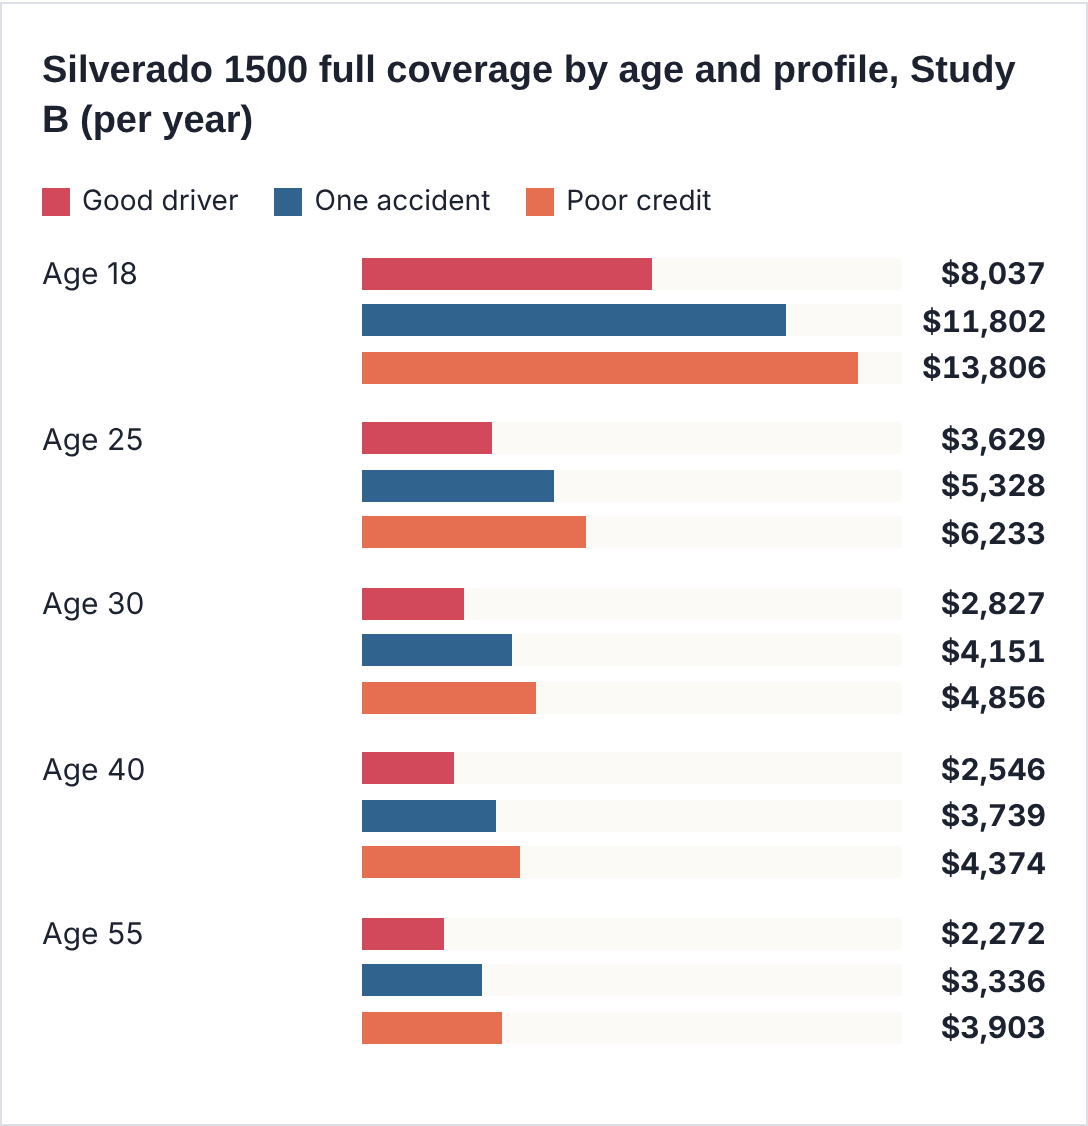
New vehicle, national estimates. Source: Study B, Chevrolet Silverado 1500 insurance.
At 40, one at-fault accident adds $1,193 a year, a 47% increase, and poor credit adds $1,828, or 72%. An 18-year-old good driver pays $8,037, more than three times a 40-year-old, and prices ease to $2,272 by 55.
Silverado insurance for teen drivers
Study D puts the average teen premium for a Silverado 1500 at $8,878 a year, about $740 a month, and Study B estimates $8,037 for an 18-year-old good driver. No study we found prices the Silverado by company for each teenage year, so these sections pair Silverado figures with national teen data.
Silverado insurance at age 16
Adding a 16-year-old to a parent's policy costs about $4,050 a year on average in Study D, the most of any teenage year. On a separate policy, GEICO is the cheapest national company for a 16-year-old in Study A's teen data, at $8,436 a year before the truck is factored in, so the family policy is the clear choice.
Silverado insurance at age 17
Adding a 17-year-old costs about $3,740 a year in Study D, and GEICO's cheapest separate policy for a 17-year-old is $6,937 in Study A's teen data. A Regular Cab WT, the cheapest configuration in Study E, is the least expensive Silverado to put a teen in.
Silverado insurance at age 18
Study B estimates $8,037 a year for an 18-year-old good driver, $11,802 after one at-fault accident, and $13,806 with poor credit. Adding an 18-year-old to a family policy costs about $3,478 a year in Study D.
Silverado insurance at age 19
Adding a 19-year-old costs about $3,105 a year in Study D, the least of the four teenage years. On a separate policy, Travelers is the cheapest national company at 19 in Study A's teen data, at $4,465 a year.
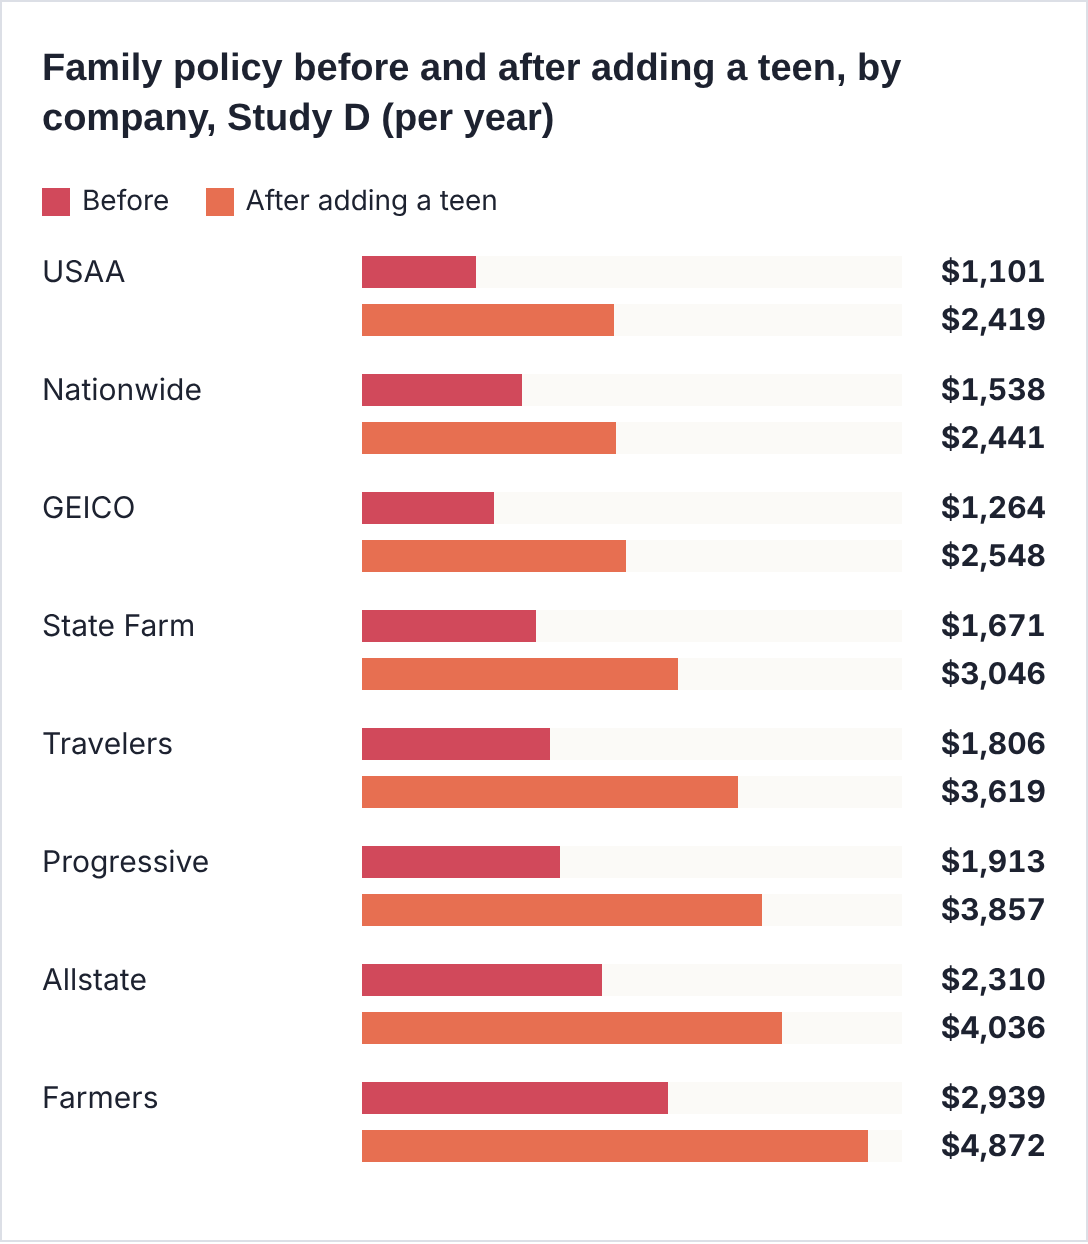
National data, no specific test vehicle. Source: Study D, cost of adding a teen driver, August 4, 2026.
Nationwide adds the least to a family policy, $903 a year, and it is also the cheapest company for a Silverado 1500 in Study D. That makes it a strong first quote for families with a new driver.
PRO TIP #5
Turn on Chevrolet's Teen Driver mode before your teen drives the Silverado. It can mute the radio until seat belts are buckled, warn the driver above a speed you choose, and give you a report card on their driving, and it pairs well with a telematics discount program.
The Silverado as a family vehicle
A crew cab Silverado is a family vehicle for many households. IIHS rates its child seat anchors Marginal for ease of use, so check that your car seats fit before you buy and have them inspected. Its Poor rating in the updated moderate overlap test relates to rear-seat protection, so make sure everyone in back is belted. Insuring the truck with a second family vehicle can earn GEICO's multi-vehicle discount of up to 25% or Progressive's 12% average saving.
Silverado insurance for seniors and military families
Study B's Silverado 1500 estimate falls to $2,272 at 55. National data in Study D shows average senior premiums of $2,353 at 65, $2,498 at 70, and $2,742 at 75, with Travelers the cheapest company open to everyone for drivers 65 to 75 at $1,987 a year, which lines up with its Silverado lead in Study A. The Hartford, which sells through AARP, offers members 10% off and 5% for a defensive driving course.
For military families, USAA charges $1,949 for a 2025 Silverado 1500 in Study A and is the cheapest company of all for 2018 and 2019 models.
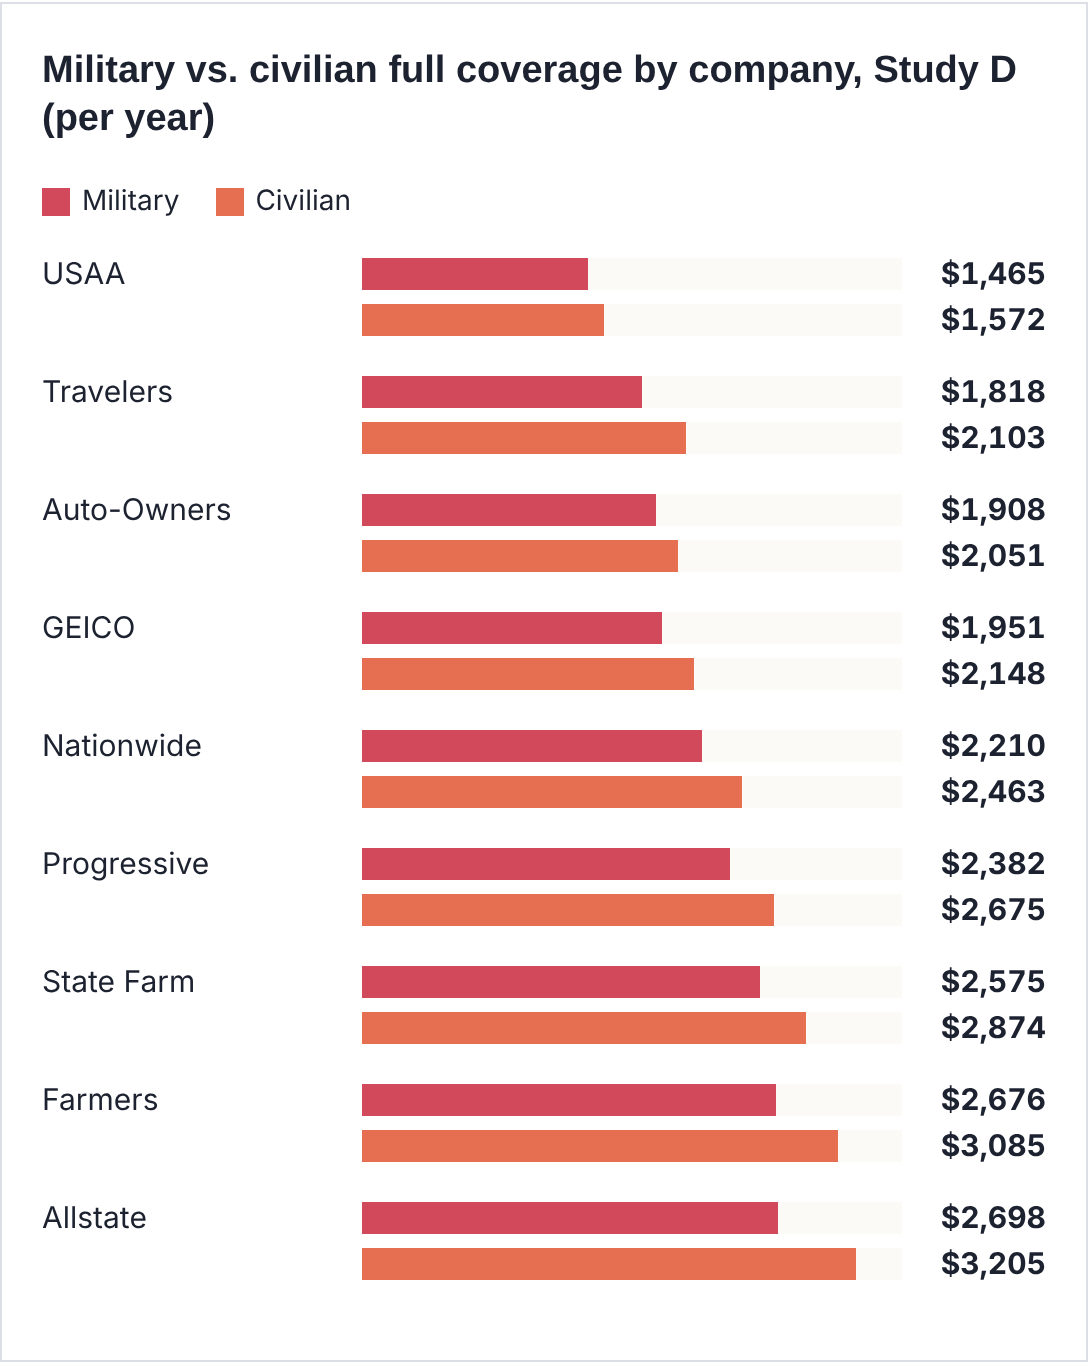
National data, no specific test vehicle. Source: Study D, best car insurance for military members, August 13, 2026.
Every company in Study D charged military members less than civilians. GEICO offers up to 15% for military members and up to 25% when deployed, and USAA offers up to 60% off when a vehicle is in storage, except in North Carolina and Virginia, and 15% off comprehensive when it is garaged on a military base.
10 discounts that lower Silverado insurance
We took each discount below from the insurer's own website. Amounts are maximums or averages, and not every discount is offered in every state.
1. More than one vehicle
GEICO lists up to 25% off for insuring several vehicles, and Progressive says its multi-car customers save 12% on average. A Silverado paired with a family car is an easy fit.
2. Bundling home and auto
Progressive says customers who bundle save more than $1,000 a year on average; Nationwide cites $1,032, and The Hartford $963. Farmers lists savings of 10% or more. If you own a boat, camper, or trailer, ask whether it can join the bundle.
3. Telematics programs
State Farm's Drive Safe & Save and Liberty Mutual's RightTrack each offer up to 30%. USAA's SafePilot gives 10% for enrolling and up to 30% at renewal; Nationwide's SmartRide gives 10% for signing up, and Progressive says Snapshot drivers save $328 a year on average.
4. Newer vehicle
Travelers offers a discount on vehicles less than three years old in most states, but not in California. A 2024 or newer Silverado can qualify.
5. Anti-theft devices
With the Silverado near the top of the theft list, ask about anti-theft discounts. City-level differences matter: Phoenix vehicle theft and car insurance data provide one localized example. GEICO lists one for anti-theft systems, and rules for these discounts differ by state.
6. Good grades
State Farm offers up to 25% for good students, GEICO up to 15%, and Progressive about 5%. Travelers asks for at least a B average.
7. Clean driving record
GEICO lists up to 22% for drivers with five years free of accidents, and Travelers offers a safe driver discount.
8. Safety features
State Farm offers up to 40% off certain medical coverages for factory airbags, and GEICO lists 5% for anti-lock brakes.
9. Quoting online and paying in full
Progressive lists about 7% for a quote started online and about 10% for signing documents online, and The Hartford lists 8% for an online quote. Travelers offers discounts for quoting early and for paying in full.
10. Military, AARP, and driver courses
GEICO offers up to 15% for military members, The Hartford gives AARP members 10% off and 5% for a defensive driving course, and Travelers lists a driver training discount for young drivers.
Bottom line: For most Silverado owners, multi-vehicle, bundling, and telematics discounts save the most, and an anti-theft discount is worth asking about.
Gap insurance, your deductible, and add-ons for a Silverado
A new Silverado is a big purchase. A 2026 High Country starts at $65,495 with destination, a ZR2 at $74,295, and a Silverado EV LT Max at $91,295.
If the truck is totaled or stolen early in a loan, its value can fall below what you still owe, and standard collision or comprehensive coverage pays only the truck's actual cash value. Gap insurance covers that difference, so it is worth pricing on a long loan or a small down payment. Your lender or dealer may offer it, but compare its price with your insurer's.
Your deductible is the next lever. A higher deductible lowers your premium, while a lower one costs more but leaves less to pay after a claim. Pick an amount you could pay tomorrow without strain, and quote at least two levels with each company so you can see the real difference in dollars. For context, a small first car insurance payment changes billing cash flow, not the protection purchased. Study A prices a $500 deductible and Study E a $1,000 deductible, which is one reason their numbers differ.
Two smaller add-ons matter for truck owners. Rental reimbursement pays for a replacement vehicle while your Silverado is in the shop after a covered claim, and if you rely on the truck for work, check whether the daily limit is enough for a pickup. Roadside assistance covers towing, jump-starts, and lockouts, which helps on job sites and remote trails. Both are usually inexpensive, but confirm what the limits pay for.
Bottom line: Add gap insurance on a big loan, choose a deductible you can afford, and check that rental coverage fits a pickup.
Silverado insurance myths vs. facts
MYTH VS. FACT
- Myth: A High Country costs far more to insure than a WT. Fact: Study D's gap from the cheapest to the priciest trim is $291 a year.
- Myth: A most-stolen truck must have high theft claims. Fact: Study C's comprehensive loss index for the Silverado is 78, 22% below average.
- Myth: The Silverado and the Sierra cost the same to insure. Fact: Study C estimates the Sierra $95 a year lower.
- Myth: USAA is always cheapest. Fact: Travelers beats USAA for every Silverado 1500 from 2020 to 2025 in Study A.
- Myth: Super Cruise earns a discount. Fact: We found no insurer that lists one.
Six mistakes that make Silverado insurance cost more
- Accepting the first quote. For the same 2025 Silverado 1500, Study A's prices range from $1,865 to $3,612 a year.
- Leaving the wrong cab, bed, trim, or engine on file.
- Skipping custom equipment coverage for a lift kit, wheels, a light bar, or a toolbox.
- Using a personal policy for a truck that does regular business work.
- Ignoring your record: one at-fault accident adds $1,193 a year at 40 in Study B, and poor credit adds $1,828.
- Putting off the 6.2-liter engine recall or any other open recall.
Seven questions to ask an insurer about your Silverado
- Do you have my exact trim, cab, bed length, and engine on file?
- How much custom equipment coverage do I have, and what does more cost?
- Do you offer an anti-theft discount for my truck?
- Is my truck covered when I use it for work, and when would I need a commercial policy?
- How is a trailer I tow covered, both for liability and for damage?
- What would a $500 deductible cost compared with $1,000?
- How will adding my teen change the price, and which vehicle will you rate them on?
How to shop for Silverado insurance in five steps
- Write down the model year, trim, cab, bed, engine, vehicle identification number, and any add-on equipment.
- Pick your limits and deductible, at least 100/300/100, and use them on every quote.
- Get at least four quotes, starting with Travelers, GEICO, State Farm, and Nationwide, plus USAA if you qualify.
- Ask for multi-vehicle, bundling, telematics, and anti-theft discounts by name.
- Requote at every renewal, after a move, and whenever a teen starts driving. Compare advertising claims about car insurance below $100 per month against your actual Silverado liability and physical-damage limits.
Silverado insurance in five cartoon panels
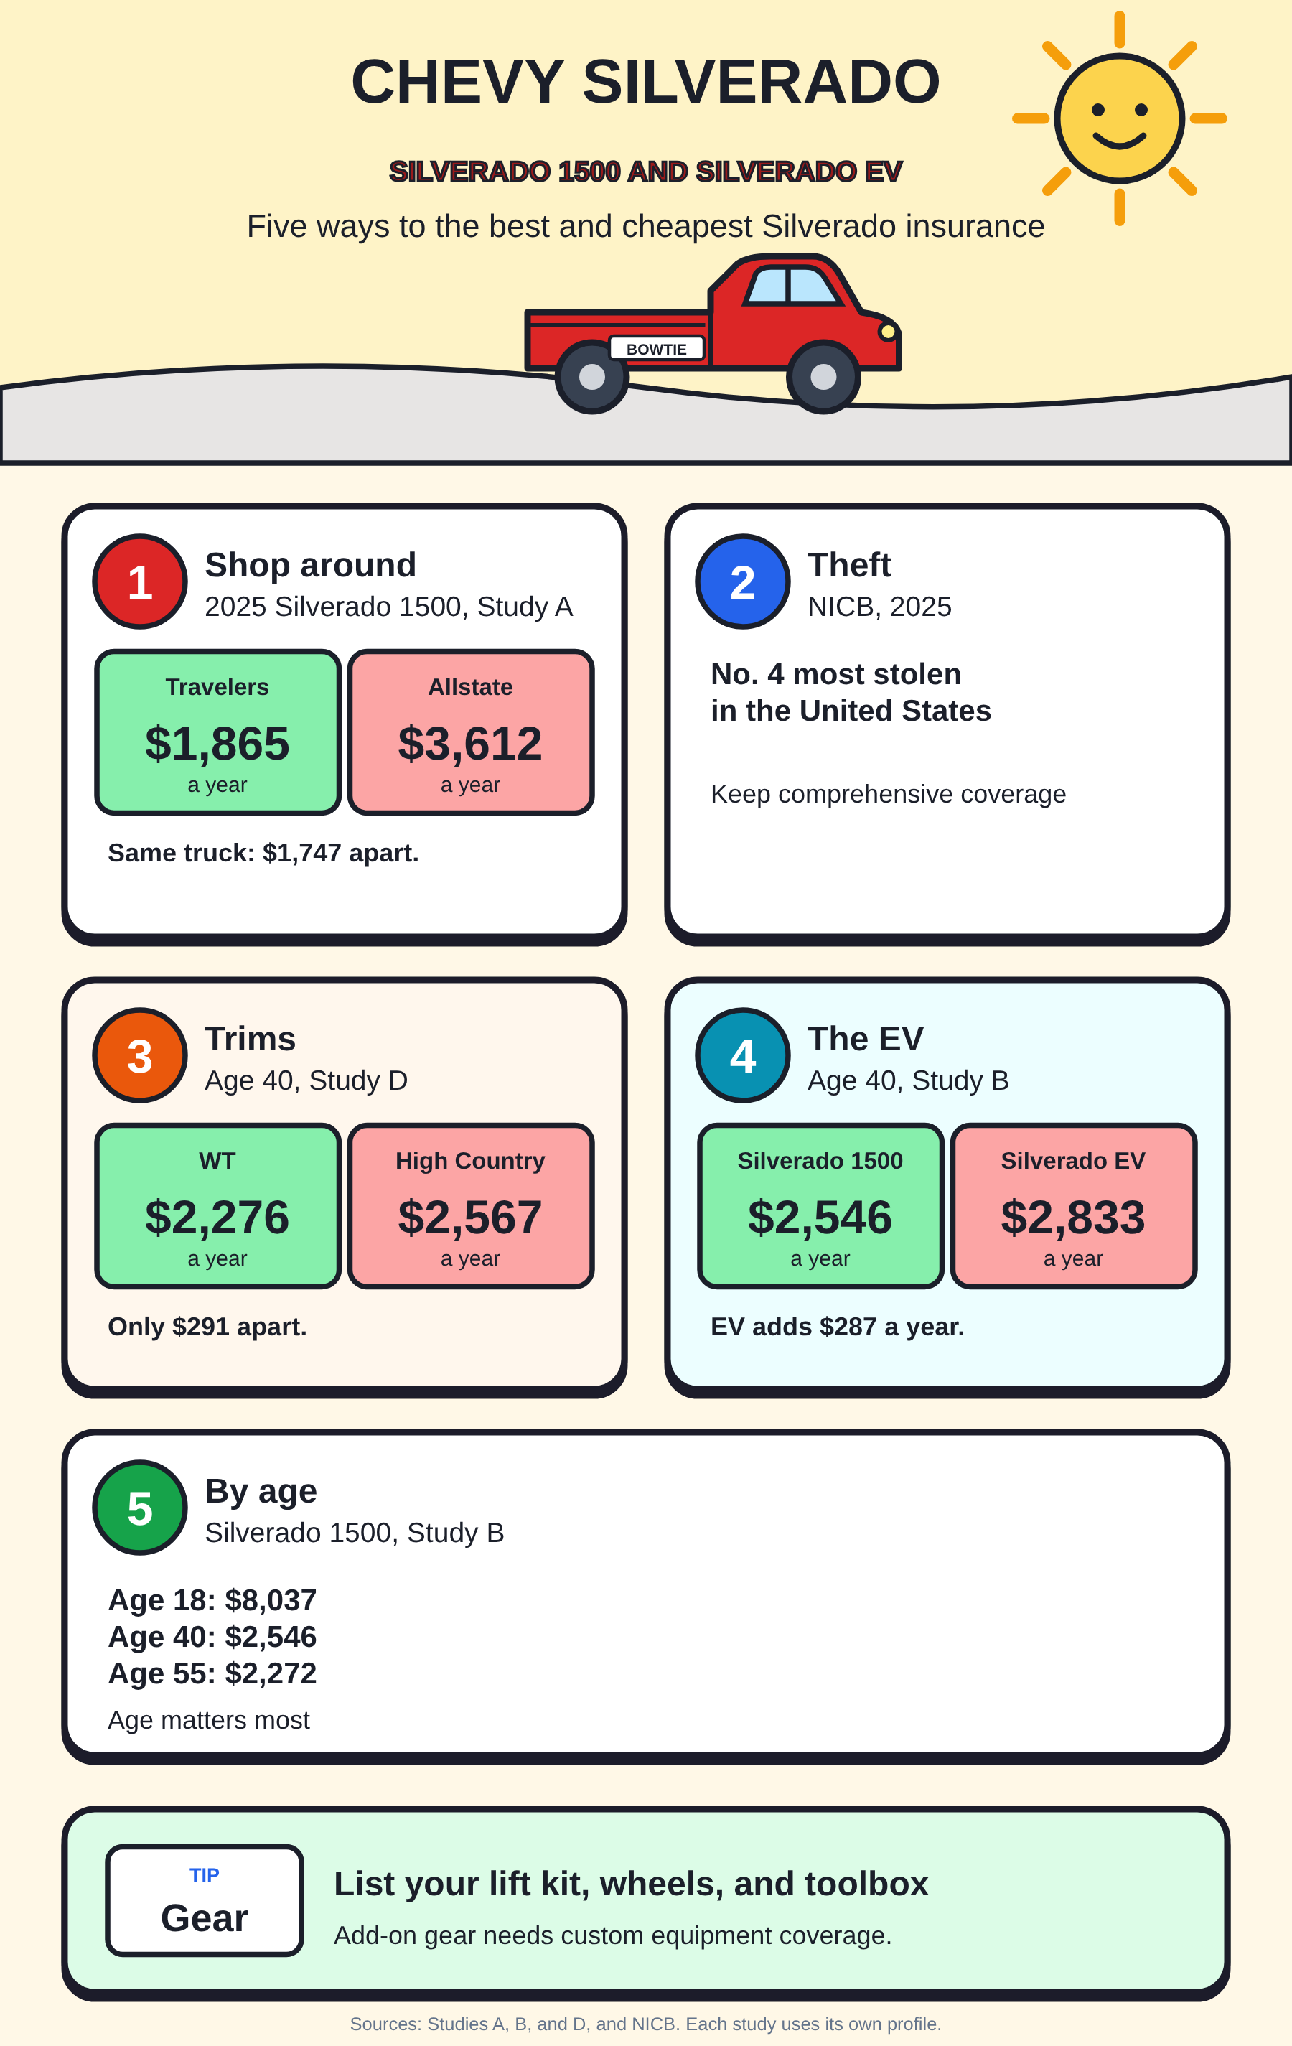
An original cartoon summary of the key Silverado insurance numbers.
Frequently asked questions about the best and cheapest Chevrolet Silverado insurance
Who has the cheapest Chevrolet Silverado insurance?
Travelers, at $1,865 a year for a 2025 Silverado 1500 in Study A, is the cheapest company for every model year from 2020 to 2025. USAA is next for military families, and GEICO leads Study E.
How much is Silverado insurance per month?
About $201 to $219 a month for a 40-year-old, based on Studies A, B, and D, or $158 a month across all model years with a $1,000 deductible in Study E.
Which Silverado trim is cheapest to insure?
The WT, at $2,276 a year in Study D. The High Country is the most expensive trim in that study at $2,567, and Study E prices the ZR2 at $326 a month in crew cab form.
Does the cab style change the price?
Yes. In Study E, a Regular Cab WT costs $177 a month, a Double Cab WT $194, and a Crew Cab WT $207.
Which Silverado model year is cheapest to insure?
Among recent years in Study E, the 2021, at $161 a month, against $244 for a 2025.
Is the Silverado expensive to insure because it is stolen so often?
Not by as much as you might expect. It was fourth on NICB's 2025 most-stolen list, but Study C puts its comprehensive losses 22% below average. Keep comprehensive coverage regardless.
Does the 6.2-liter engine recall affect my insurance?
A recall does not automatically trigger a uniform rate surcharge; any effect on pricing is insurer- and risk-dependent. Ordinary mechanical failure generally is not covered by personal auto insurance. Get the recall repair done, and check your vehicle identification number on NHTSA's lookup.
Is the Silverado cheaper to insure than an F-150?
No. Study B puts the Silverado 1500 $132 a year above the F-150, and Study C $109 above it.
Is the Silverado cheaper to insure than a Ram 1500?
Yes, in Study C's loss data, by $174 a year. The Ram 1500 has the highest losses of the full-size pickups in that study.
How much does the Silverado EV cost to insure?
Study B estimates $2,833 a year for a 40-year-old good driver, $287 more than the gas Silverado 1500.
How much does an 18-year-old pay to insure a Silverado?
Study B estimates $8,037 a year for a good driver. Adding the teen to a parent's policy usually costs much less.
How much is minimum coverage on a Silverado?
Study E puts state-minimum coverage at $82 a month on average, with GEICO cheapest at $58.
Which state has the cheapest Silverado insurance?
Hawaii, at $1,541 a year in Study D's 50-state data and $1,179 among the 15 states in Study B's table. Louisiana is the most expensive in Study D.
Who has the cheapest Silverado insurance in Florida?
State Farm, at $2,075 a year for a 2025 Silverado 1500 Custom in Study A's Florida sample, followed by Travelers at $2,287.
Do I need commercial insurance for a work Silverado?
If the truck is used regularly for business, carries employees, or is owned by a company, ask about a commercial policy. A personal policy may limit or exclude business use.
Is the Silverado safe?
NHTSA gives the 2025 Silverado 1500 five stars overall. IIHS rates it Marginal in the small overlap test and Poor in the updated moderate overlap test, so it has no IIHS award.
Is the ZR2 expensive to insure?
It is the priciest version in Study E, at $326 a month for a Crew Cab ZR2 against $207 for a Crew Cab WT, a gap of about $1,430 a year.
Does bed length change the price?
It can. Study E prices a Crew Cab High Country at $294 a month with the 5¾-foot bed and $197 with the 6½-foot bed, so quote the exact configuration you plan to buy.
Should I keep full coverage on an older Silverado?
Keep it while you have a loan or lease, since lenders require it. On an older, paid-off truck you could replace with cash, compare the yearly cost of collision and comprehensive with what the truck is worth.
Does the Silverado cost more to insure for a 30-year-old?
Study B estimates $2,827 a year for a 30-year-old good driver, $281 more than at 40. In Study F, Progressive is cheapest for a 30-year-old at $1,705 for a 2025 Silverado 1500.
How much does poor credit add to Silverado insurance?
Study B estimates $4,374 a year for a 40-year-old with poor credit against $2,546 with good credit. California and Hawaii do not allow credit to affect auto rates.
Is the Silverado cheaper to insure than a Tundra?
The two are about level in Study C, at $1,454 and $1,464 a year. Quote both with the same company if you are cross-shopping.
Will the 2027 Silverado cost more to insure?
The cited rate studies do not provide a verified like-for-like insurer ranking for the redesigned 2027 model. Get quotes on the exact trim and engine before you buy.
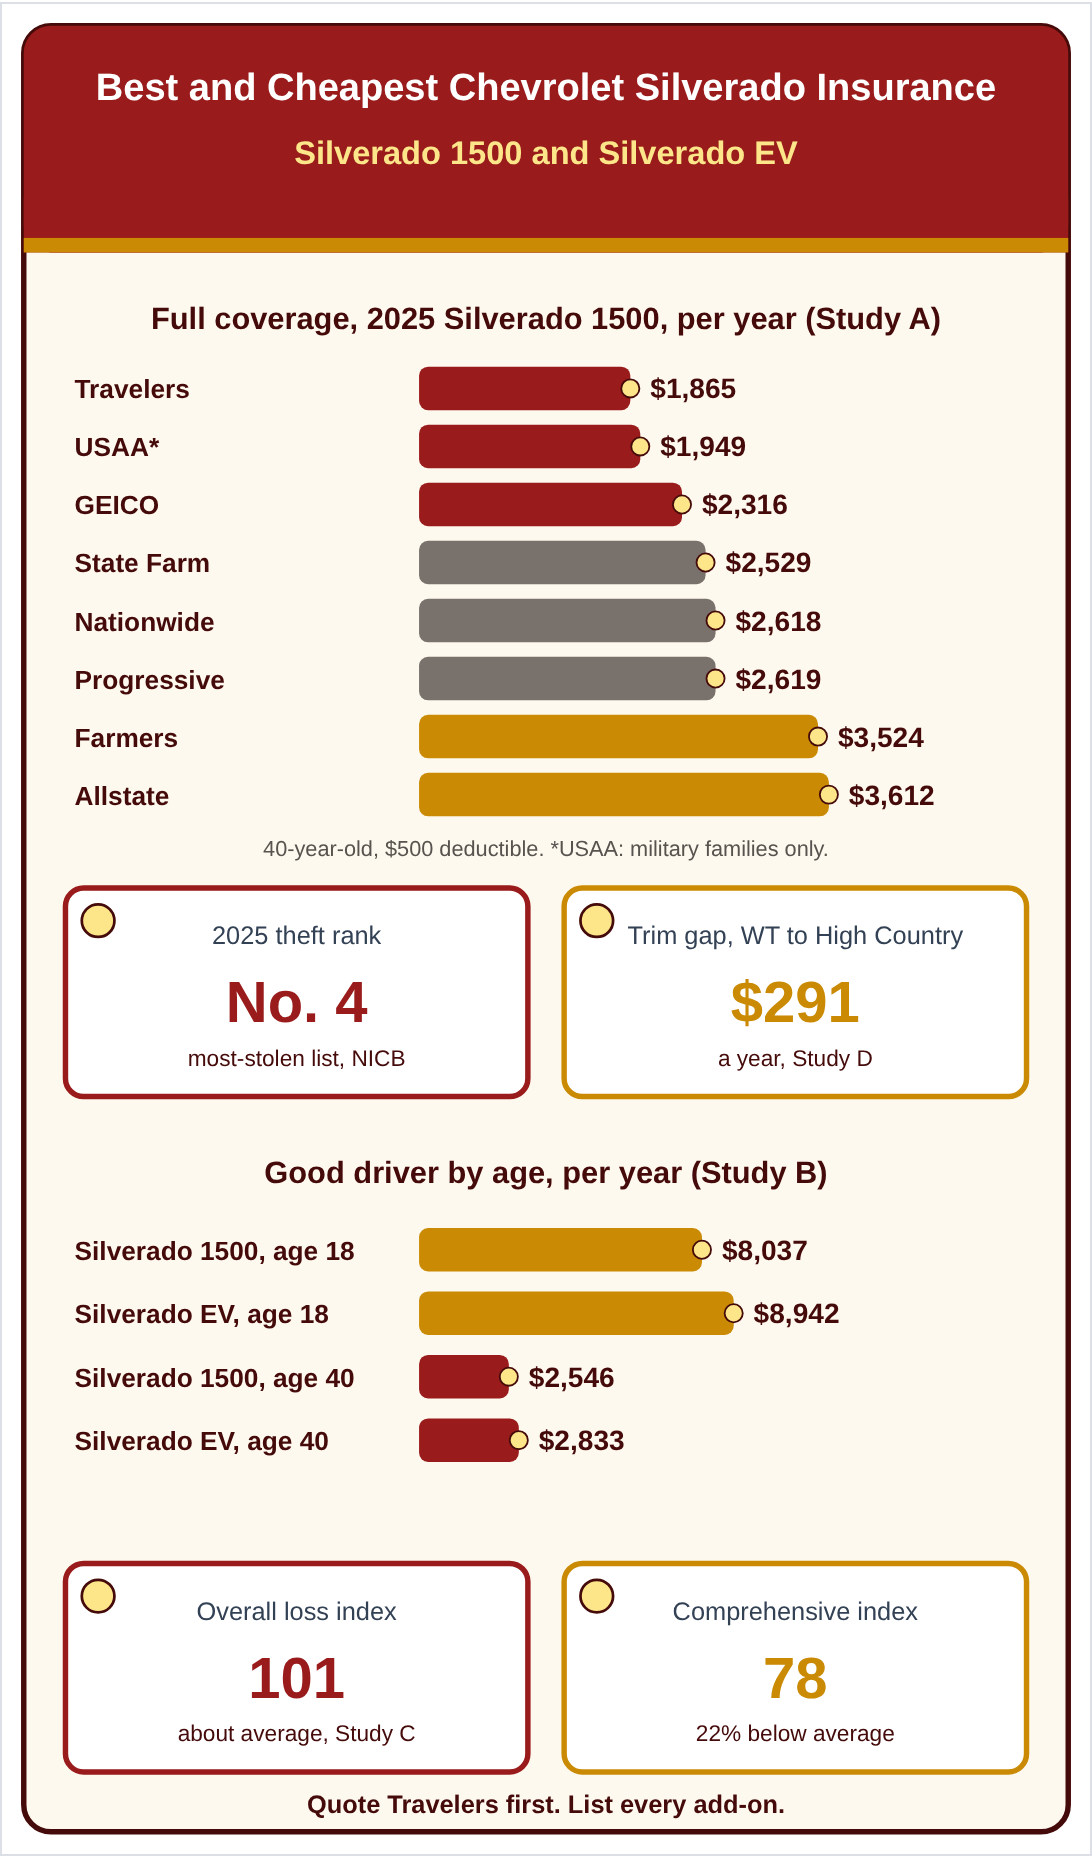
Silverado 1500 and Silverado EV insurance in one picture.
The final word on the best and cheapest Chevrolet Silverado insurance
The Silverado has approximately average losses in one vehicle-loss model, and the details you choose move the price less than the company you pick. Trims sit within about $300 a year of each other in Study D, a Regular Cab costs a little less than a Crew Cab, and the EV adds a few hundred dollars. Theft risk is real, but the truck's comprehensive losses are below average, so the right coverage matters more than a higher price.
Start with Travelers, GEICO, State Farm, and Nationwide, add USAA if you qualify, and keep the limits and deductible the same on every quote. List your lift kit, wheels, and toolbox, tell the insurer if the truck works for a living, and keep teens on the family policy. If you own a 2021 to 2024 Silverado with the 6.2-liter V8, make sure the recall work is done.
Sources
- Study A: Insurance.com, Chevrolet Silverado 1500 car insurance (October 26, 2026), and teen car insurance costs (August 13, 2026).
- Study B: CarEdge, Chevrolet Silverado 1500 insurance rates and Chevrolet Silverado EV insurance rates.
- Study C: ForCar, Chevrolet Silverado insurance cost (November 2026), citing Highway Loss Data Institute figures.
- Study D: CarInsurance.com, Chevrolet Silverado 1500 car insurance cost; cost of adding a teen driver (August 4, 2026); car insurance for seniors (April 16, 2026); best car insurance for military members (August 13, 2026); top financially rated insurers (December 16, 2025); and insurers ranked by NAIC complaint data (August 13, 2026).
- Study E: MoneyGeek, Chevrolet Silverado 1500 insurance (May 21, 2026).
- Study F: The Zebra, Chevrolet Silverado 1500 insurance by model year and company.
- Service ratings: J.D. Power 2026 U.S. Auto Insurance Study coverage (June 9, 2026); J.D. Power 2026 regional scores; Amica, J.D. Power 2026 results; and J.D. Power 2026 Auto Claims Satisfaction Study coverage (October 27, 2026).
- Insurer pages: Travelers discounts; Progressive discounts; GEICO discounts; GEICO military discounts; State Farm discounts; Nationwide discounts; Nationwide SmartMiles; Liberty Mutual RightTrack; Farmers discounts; USAA discounts; The Hartford AARP discounts; and Lemonade, pay-per-mile car insurance.
- NICB, 2025 vehicle theft totals and rankings (March 18, 2026).
- Chevrolet, official next-generation 2027 Silverado announcement (June 2026).
- Reuters, NHTSA expanded GM engine investigation (August 21, 2026).
- NHTSA, recall 25V274 (May 2025).
- Theft: CarPro, the 10 most stolen vehicles in the U.S. in 2025, reporting National Insurance Crime Bureau data.
- Recalls: Automotive Fleet, GM recalls nearly 600,000 vehicles for potential engine failure (May 2025); CarComplaints, GM engine failure recall investigation (January 2026); 2026 Chevrolet Silverado 1500 recalls; and NHTSA recall lookup.
- Safety: 2025 Chevrolet Silverado 1500 IIHS and NHTSA ratings, and Chevrolet, Teen Driver technology.
- Vehicle data: Pickup Truck Talk, 2026 Silverado 1500 pricing (December 2025); GM Authority, 2026 Silverado EV pricing (April 2025); and Carscoops, 2027 Chevrolet Silverado 1500 redesign (June 2026).
- Sales: Jalopnik, Chevy 2025 lineup sales results; Pedal Commander, best-selling trucks of 2025; and GM newsroom, 2025 U.S. sales.
- Other sources: AARP, auto insurance discounts.
Disclaimer
This guide brings together published rate studies, insurance-loss estimates, theft rankings, satisfaction surveys, crash-test results, and recall records for the Chevrolet Silverado 1500 and Silverado EV. Each study uses its own driver profile, coverage limits, and deductible, and one study does not say whether its Silverado figures include heavy-duty trucks, as noted where it appears. The rate studies reviewed here do not establish a comparable insurer ranking for the 2027 Silverado 1500. Treat everything here as general information, not insurance, legal, tax, or financial advice.
What you pay will depend on your ZIP code, age, driving and claims history, credit where allowed, the other drivers in your home, your mileage, and how you use the truck, as well as its model year, trim, cab, bed, engine, and add-on equipment and the limits and deductible you choose. Business use, towing, and aftermarket parts are treated differently by each insurer, so get the terms in writing before you rely on them.
We are an independent publisher with no connection to General Motors, Chevrolet, GMC, the National Insurance Crime Bureau, IIHS, NHTSA, the Highway Loss Data Institute, J.D. Power, AM Best, or any insurer named here, including Travelers, USAA, GEICO, State Farm, Nationwide, Progressive, Farmers, Allstate, UAIC, Mercury, AIG, American Family, Erie, The Hartford, Liberty Mutual, and Lemonade. Company positions are presented as results from named third-party data sets, not independently collected quotes; this article is not an endorsement by any insurer.
Chevrolet, Silverado, Silverado EV, Super Cruise, Teen Driver, Trail Boss, ZR2, High Country, LTZ, RST, TurboMax, Duramax, GMC, Sierra, Ford, F-150, F-Series, Ram, Toyota, Tundra, Nissan, Titan, and other names used here are trademarks of their respective owners.