
Cheapest Chevrolet Impala Insurance: Companies, Rates & Used Car Coverage
QUICK ANSWER
For a 30-year-old with no violations, USAA sells the cheapest Chevrolet Impala insurance in Study A, at $1,673 a year for a 2020 model, and it is cheapest for eight of the 10 model years from 2011 to 2020. American Family is the cheapest company open to everyone at $1,722. Because most Impalas are now worth less than $10,000, the biggest saving for many owners comes from deciding whether to keep collision and comprehensive.
KEY TAKEAWAYS
- Study A reports a $2,327 full-coverage figure for a 2020 Impala. Its published year-by-year averages need separate methodological verification before combining them into a new overall average.
- Study C gives 2018 to 2020 Impalas a loss index of 145, 45% above average, with personal injury protection losses nearly twice the average.
- Older Impalas cost less to insure: a 2011 averages $1,492 a year in Study A, $835 less than a 2020.
- On most Impalas from 2017 and earlier, Study C’s collision and comprehensive estimate is more than 10% of the car’s typical asking price.
- Chevrolet built the last Impala in February 2020, ending a run that began in 1958.
Drivers searching for the cheapest Chevrolet Impala insurance are usually insuring a used car, since the last Impala left the Detroit-Hamtramck plant on February 27, 2020. Over 62 years and 10 generations, the Impala went from a 1960s icon to a roomy, front-wheel-drive family sedan and a regular choice for police departments and business fleets.
That history matters for insurance. Most Impalas on the road are from 2000 to 2020, worth a few thousand to about $13,000, and the newest ones have a surprisingly poor claims record. The right company and the right coverage can make a big difference to what you pay.
This guide uses five sources: a rate study by company and model year, an insurer comparison from a state tool, insurance-loss and used-price data, an ownership-cost model, and national figures for teens, seniors, and military families. Each one prices its own driver and coverage, so compare figures within a study rather than across them.
WHAT CHANGED IN THIS UPDATE
- November 2026: Added Study C’s loss indexes by coverage and model-year group, state estimates, used prices from 2001 to 2020, and recall list.
- October 26, 2026: Added Study B’s company comparison from its state tool.
- 2026: Added Study D’s five-year ownership costs.
- 2025 data: Added Study A’s company prices for a 2020 Impala and its averages for 2011 to 2020.
- Added sections on the Impala SS, the Impala Limited, classic Impalas, and the Caprice PPV.
IN THIS GUIDE
- The cheapest companies and every model year from 2011 to 2020
- All generations and engines since 2000, the SS, the Impala Limited, and trims LS to Premier
- Loss data, recalls, and when to drop full coverage
- Classic Impalas and the Caprice PPV police car
- States, tickets, teens, seniors, military, discounts, and five-year costs
- Jump to your situation: owners of a 2017 or older Impala, see the liability-only section; buyers of an ex-police car, see the Caprice PPV section.
Chevrolet Impala insurance at a glance
| Measure | Figure |
| Cheapest company, 2020 Impala, Study A | USAA, $1,673 a year |
| Cheapest open to all, 2020 Impala, Study A | American Family, $1,722 a year |
| Average, 2020 Impala, Study A | $2,327 a year |
| Average, 2011 Impala, Study A | $1,492 a year |
| Insurance-loss index, 2018 to 2020 models, Study C | 145 (45% above average) |
| Loss-based estimate, Study C | $2,092 a year |
| Collision and comprehensive estimate, Study C | $837 a year |
| Insurance, five years, new Impala, Study D | $12,010 |
Full coverage. Study A prices a 30-year-old man with no violations. Study D prices a 40-year-old with good credit. The Sources section names every study.
Impala insurers ranked from cheapest
Study A prices a 2020 Impala at nine companies for a 30-year-old man with no violations, using 2025 rates. The graphic ranks them and adds the study’s average. The nine individual company prices displayed below average about $2,256, while a separate Study A summary reports $2,327. These values are not reconciled, so the latter should not be described as the computed nine-company average.
Full-coverage prices for a 2020 Chevrolet Impala, Study A.
USAA
USAA charges $1,673 a year, $654 below the average, and it is the cheapest company for eight of the 10 model years in Study A prices. It sells only to military members, veterans, and their families.
American Family and Erie
American Family charges $1,722, the lowest price open to everyone, and it is the cheapest company of all for 2013 and 2015 Impalas. Erie, which sells in a limited number of states, charges $1,885.
State Farm and Progressive
State Farm and Progressive are just $10 apart, at $1,974 and $1,984. Both are well below the $2,327 average.
GEICO, Farmers, Nationwide, and Allstate
GEICO charges $2,311, close to the average. Farmers charges $2,823, Nationwide $2,859, and Allstate $3,077, the highest in Study A and $1,404 more than USAA.
PRO TIP #1
Start with USAA if you qualify, then American Family, State Farm, and Progressive. If you live in a state where Erie sells, add it to the list.
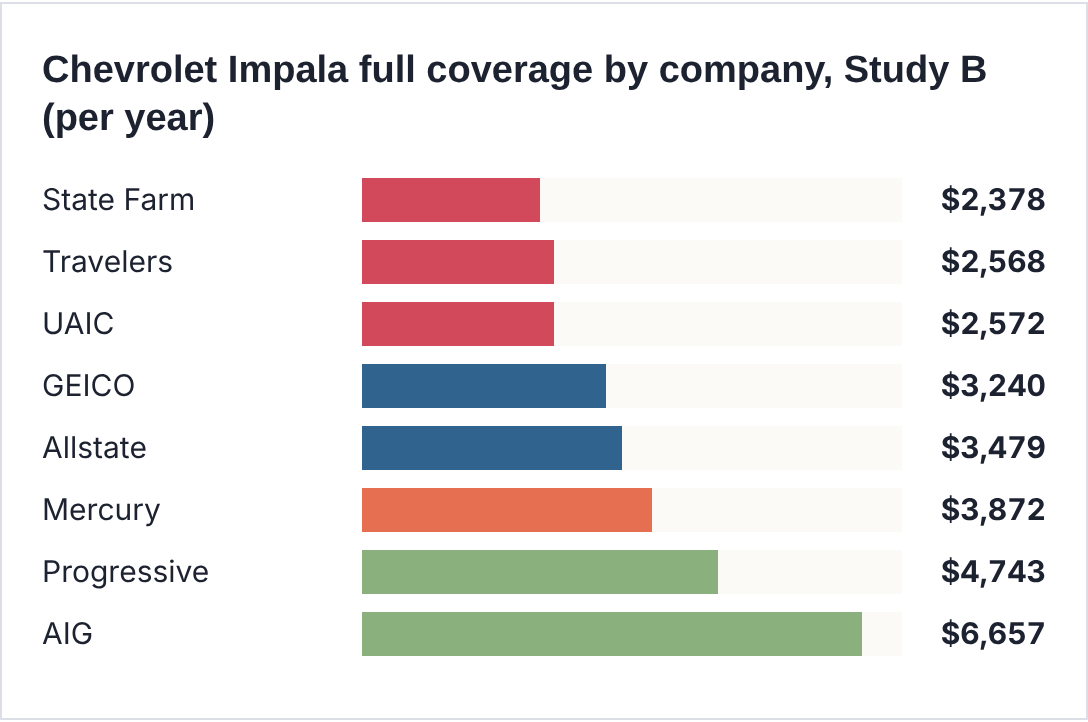
From Study B’s state tool, which loads with Florida and a 2019 Impala LS, the table itself is not labeled. Source: Study B, October 26, 2026.
Study B’s comparison, which appears to reflect Florida, finds State Farm cheapest at $2,378 a year, followed by Travelers and UAIC. AIG charges $6,657, nearly three times as much. Because Study B does not label the table, treat it as a guide to Florida prices rather than a national ranking.
Bottom line: Quote USAA, American Family, and State Farm first, and in Florida add Travelers and UAIC.
Impala model years ranked by insurance cost
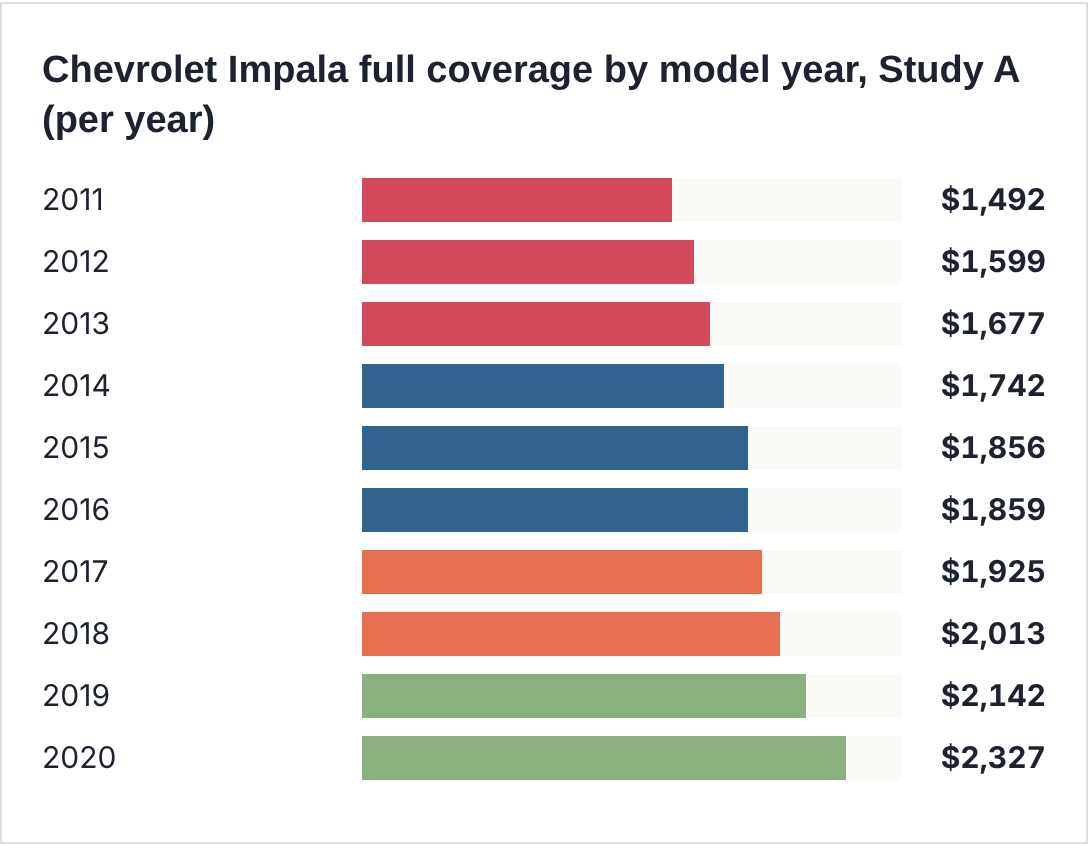
30-year-old man with no violations, average of nine companies. Source: Study A, 2025 data.
The displayed Study A average generally declines with older model years, although the data do not establish a universal pricing rule. A 2011 Impala costs $1,492 a year, $835 less than a 2020. The largest single drop, $185, comes between the 2020 and the 2019.
Cheapest Impala company by model year, Study A
| Model year | Cheapest company | Price | Study A average |
| 2020 | USAA* | $1,673 | $2,327 |
| 2019 | USAA* | $1,481 | $2,142 |
| 2018 | USAA* | $1,420 | $2,013 |
| 2017 | USAA* | $1,328 | $1,925 |
| 2016 | USAA* | $1,274 | $1,859 |
| 2015 | American Family | $1,297 | $1,856 |
| 2014 | USAA* | $1,246 | $1,742 |
| 2013 | American Family | $1,212 | $1,677 |
| 2012 | USAA* | $1,159 | $1,599 |
| 2011 | USAA* | $1,058 | $1,492 |
*USAA sells only to military families. Source: Study A, 2025 data.
Bottom line: In Study A, older Impala model years generally have lower average sample premiums; quotes for a specific vehicle may break this pattern.
Impala prices in California
Study F prices three Impala model years at four companies for a 30-year-old with a clean record in California, using 50/100/50 limits and a $500 deductible.
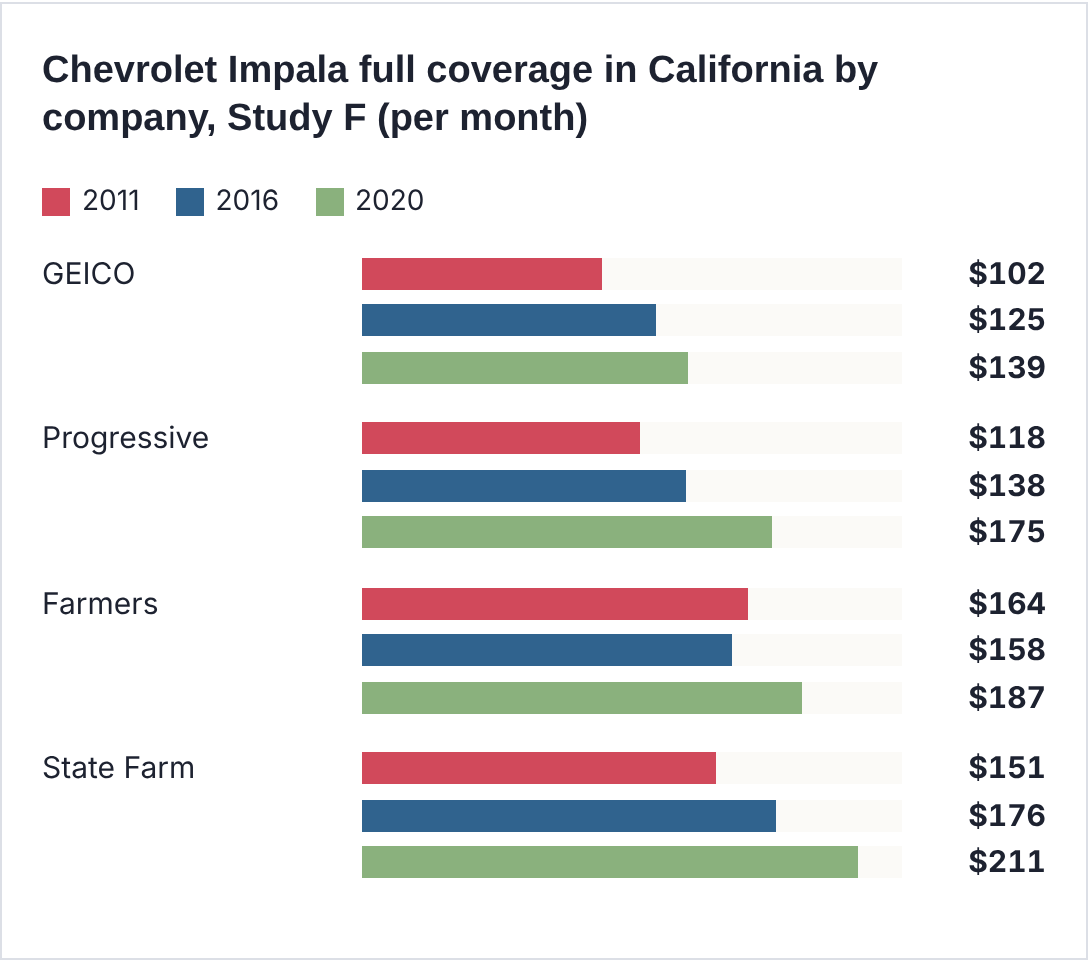
30-year-old with a clean record in California, 50/100/50 limits, $500 deductible. Source: Study F.
GEICO is cheapest for all three years in Study F, at $139 a month for a 2020 Impala and $102 for a 2011. The four-company average rises from $134 a month for a 2011 to $178 for a 2020, about $2,136 a year. California does not let insurers use gender in setting rates.
Bottom line: In California, GEICO is the first company to quote for an Impala of any age in Study F.
Service and financial ratings for Impala insurers
Service and financial ratings for Impala insurers
| Insurer | J.D. Power 2026 range | AM Best | NAIC complaint index |
| USAA* | 707 to 763 | A++ | 1.18 |
| American Family | 632 to 649 | A | 0.33 |
| Erie | 652 to 704 | A | 0.89 |
| State Farm | 632 to 669 | A+ | 0.79 |
| Progressive | 604 to 645 | A+ | 0.71 |
| GEICO | 631 to 668 | A++ | 0.69 |
| Travelers | 584 to 657 | A++ | 0.52 |
| Nationwide | 612 to 685 | A | 0.63 |
| Farmers | 558 to 675 | A | 0.86 |
| Allstate | 612 to 660 | A+ | 1.10 |
J.D. Power regional ranges on a 1,000-point scale; the 2026 study average is 644. An NAIC index below 1.00 means fewer complaints than expected. *USAA sells only to military families. Sources: J.D. Power 2026 U.S. Auto Insurance Study; Study E.
American Family, the cheapest Impala company open to everyone in Study A, also has the lowest complaint index in the table at 0.33. Erie combines strong J.D. Power scores with an A (Excellent) financial strength rating, affirmed in September 2026.
Every modern Impala generation and trim
Most Impalas you can insure today come from three generations built between 1999 and 2020. None of the studies price individual trims, so the generation and engine are the best guide to what you are insuring.
Chevrolet Impala generations since 2000
| Model years | Engines | Notes |
| 2000 to 2005 | 3.4-liter V6, 180 hp; 3.8-liter V6, 200 hp; supercharged 3.8-liter V6 in the 2004 and 2005 SS | Front-wheel drive, four-speed automatic, standard anti-lock brakes |
| 2006 to 2013 | 3.5-liter V6, 211 hp; 3.9-liter V6, 233 hp (LTZ); 5.3-liter V8, 303 hp (SS, through 2009) | Trims LS, LT, LTZ, and SS; standard stability control |
| 2014 to 2016, Impala Limited | Carried over from the 2006 to 2013 car | Sold only to fleet customers |
| 2014 to 2020 | 2.5-liter four, 196 hp; 3.6-liter V6, 305 hp; 2.4-liter mild hybrid, 182 hp, early on | Six-speed automatic; trims LS, LT, LTZ, and later Premier; available blind-spot, lane departure, adaptive cruise, and automatic emergency braking |
Sources: Impala buying guide and encyclopedia entry named in Sources, and Study B’s trim list.
TRIM CARD: LS
The base trim in multiple modern generations and the trim Study B’s tool loads by default. Its lower original price may affect premiums, but no source here establishes that LS is always cheapest to insure.
TRIM CARD: LS FLEET
A version sold to businesses and government buyers. Ask for a history report, since a fleet car may have high mileage or a history of many drivers.
TRIM CARD: LT
The middle trim in each generation. Study B lists it among its 2015 to 2020 choices.
TRIM CARD: LTZ AND PREMIER
The top trims, with LTZ on earlier cars and Premier on later tenth-generation cars. Their higher market values can affect the decision to retain collision and comprehensive; compare the actual premium and deductible.
TRIM CARD: SS
The performance model, offered with a supercharged V6 for 2004 and 2005 and a 303-horsepower V8 from 2006 to 2009, and as the 1994 to 1996 V8 sedan. No study prices it separately; see the SS section below.
Bottom line: For a 2014 to 2020 Impala, tell the insurer which engine you have, and for any year, quote by vehicle identification number so the trim and equipment are captured.
How far apart are the studies?
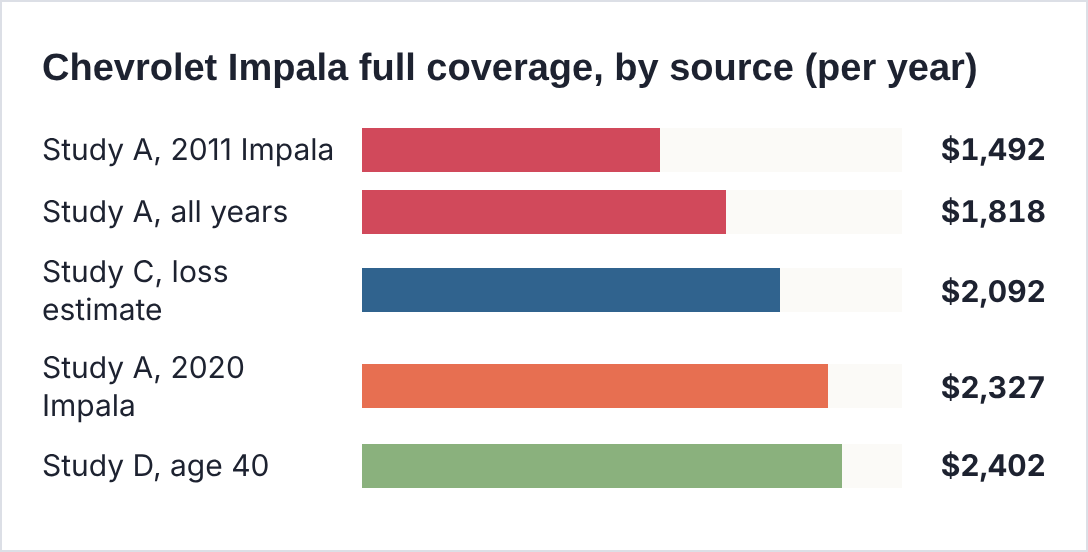
Each study uses its own driver, coverage, and date. Sources: Studies A, C, and D.
Unusually, Study C’s loss-based estimate is higher than Study A’s average across model years. That reflects the Impala’s high loss index for 2018 to 2020 models; Study C applies it to a national average premium. Study D’s figure is for a 40-year-old and a new car.
Bottom line: These studies illustrate a range of sample premiums, not a reliable budget for every Impala owner; obtain matching quotes for your state, coverage and vehicle.
Impala price finder
Chevrolet Impala price finder
| Your situation | Typical price | Source |
| Military family, 2020 Impala | USAA, $1,673 a year | Study A |
| Cheapest open to all, 2020 Impala | American Family, $1,722 a year | Study A |
| 2011 Impala, cheapest company | USAA, $1,058 a year | Study A |
| 2013 Impala, cheapest company | American Family, $1,212 a year | Study A |
| 2016 Impala, average | $1,859 a year | Study A |
| Florida, cheapest company | State Farm, $2,378 a year | Study B |
| Florida, loss-based estimate | $2,899 a year | Study C |
| Maine, loss-based estimate | $1,346 a year | Study C |
| Age 40, new Impala | $2,402 a year | Study D |
Full coverage.
Five Impala owners and their premiums
THE 2018 IMPALA COMMUTER
A 30-year-old with a clean record pays $2,013 a year on average in Study A, or $1,420 with USAA.
THE STUDENT WITH A 2012 IMPALA
Study A’s average for a 2012 is $1,599 for a 30-year-old. A younger driver will pay more, but a car with a typical asking price of $5,350 is a strong candidate for liability-only coverage.
THE CALIFORNIA DRIVER
A 30-year-old with a clean record pays $139 a month with GEICO for a 2020 Impala in Study F, against a four-company average of $178.
THE FLORIDA DRIVER
Study B’s Florida comparison runs from $2,378 with State Farm to $6,657 with AIG, a gap of more than $4,000.
THE OWNER OF A 2007 IMPALA SS
No study prices the SS. Study C lists 2007 Impalas at a typical asking price of $3,650, so compare liability only and, for a clean, low-mileage SS, an agreed-value collector policy.
What the loss data says about the Impala
Study C gives 2018 to 2020 Impalas an overall loss index of 145, meaning insurers paid 45% more in claims for them than for the average vehicle. Every coverage is above average, and the injury coverages are highest. An insurance-loss index measures relative claims experience, not how much an individual driver’s premium must rise.
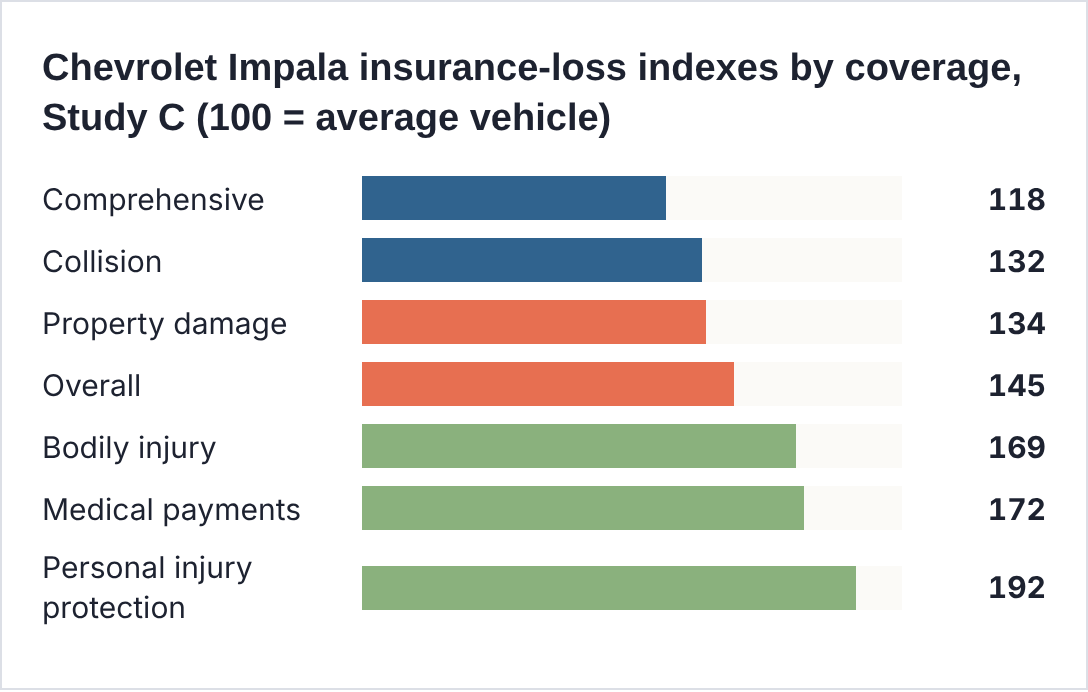
Lower is better. 2018 to 2020 models. Source: Study C, November 2026, citing Highway Loss Data Institute figures.
Personal injury protection, at 192, is nearly double the average, and medical payments and bodily injury liability are about 70% higher. Study C splits its $2,092 estimate into $1,004 for liability, $586 for collision, $251 for comprehensive, and $251 for other coverages.
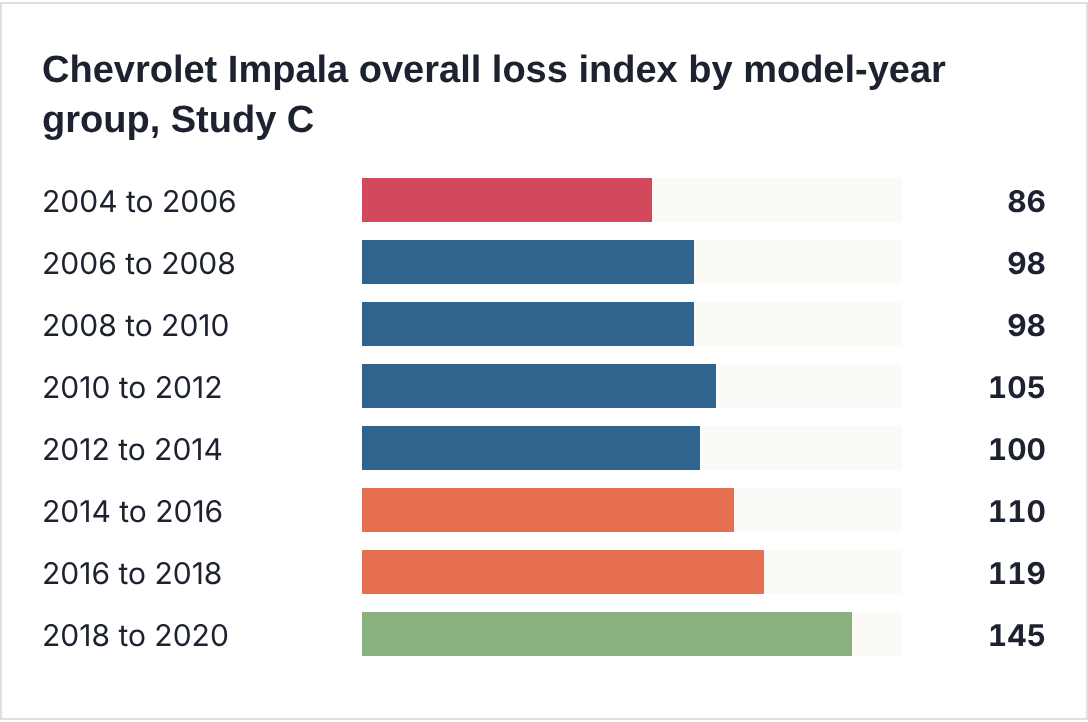
100 = average vehicle. Source: Study C, November 2026.
The loss index has climbed steadily, from 86 for 2004 to 2006 Impalas to 145 for the final cars. Study C does not explain the trend, and the data does not show who drove these cars or how they were used.
PRO TIP #2
Since injury claims are the Impala’s highest-loss area, keep bodily injury liability and medical or personal injury protection coverage strong, and look for savings in your deductible or in dropping collision on an older car.
Bottom line: Late-model Impalas have a claims record well above average, so shopping several companies matters more than usual.
Liability only or full coverage on an Impala?
Editorial caution: The $837 collision-and-comprehensive figure below is derived from late-model Impalas only. Dividing it by older used-car asking prices does not establish what owners of those older cars actually pay. Compare quotes for your exact VIN and coverage before deciding to drop protection.
For many Impala owners, this is the most important insurance decision. Study C estimates collision and comprehensive at $837 annually for late-model Impalas. Applying this figure to asking prices of much older Impalas is only a hypothetical comparison, not evidence that their actual physical-damage premiums are $837.
Collision and comprehensive compared with Impala value
| Impala | Typical asking price | $837 as a share of value |
| 2020 model | $12,995 | 6.4% |
| 2019 model | $9,250 | 9.0% |
| 2018 model | $8,988 | 9.3% |
| 2017 model | $6,999 | 12.0% |
| 2016 model | $6,900 | 12.1% |
| 2015 model | $7,395 | 11.3% |
| 2014 model | $6,900 | 12.1% |
| 2012 model | $5,350 | 15.6% |
| 2010 model | $4,200 | 19.9% |
| 2008 model | $3,995 | 21.0% |
| 2006 model | $2,900 | 28.9% |
| 2003 model | $2,500 | 33.5% |
Asking prices are listing medians, not sale prices. The $837 estimate is based on 2018 to 2020 models. It cannot be assumed to be the cost for older cars. Percentages in the table are hypothetical calculations, not year-specific premiums. Source: Study C, November 2026.
The dollar gap between a vehicle’s actual cash value and deductible narrows as it ages, but only a same-vehicle quote can establish whether collision and comprehensive are worth keeping. If your car is paid off and you could replace it from savings, price a liability-only policy with strong limits. Keep comprehensive if a theft or storm loss would leave you without a car, and keep full coverage on any Impala with a loan.
Bottom line: For an older, paid-off Impala, compare liability-only, comprehensive-only (when offered), and full-coverage quotes. Retain lender-required protection and decide based on price, deductible, actual cash value, theft/weather exposure, and replacement savings.
Building the right Impala policy
Liability and injury coverage
Liability takes $1,004 of Study C’s $2,092 estimate, and the Impala’s injury losses are its highest. Carry at least 100/300/100 limits, and in states with personal injury protection, compare the levels on offer rather than defaulting to the minimum.
Uninsured motorist coverage
If you drop collision on an older Impala, uninsured motorist property damage, where your state offers it, can still pay for damage caused by an uninsured driver. Ask whether it is available and what it costs.
Deductible
If you keep full coverage, compare quotes at $500 and $1,000. On a car worth $7,000 to $13,000, a higher deductible can lower the premium, as long as you could pay it after a claim.
Impala crash tests
The tenth-generation Impala did well in most IIHS crash tests, but its headlights rated Poor. These results apply to 2014 to 2020 cars unless noted.
IIHS ratings for the 2014 to 2020 Chevrolet Impala
| Test | Rating | Model years |
| Small overlap front, driver side | Acceptable | 2015 to 2020 |
| Moderate overlap front | Good | 2014 to 2020 |
| Side | Good | 2014 to 2020 |
| Roof strength | Good | 2014 to 2020 |
| Head restraints and seats | Good | 2020 |
| Headlights, LT and Premier | Poor | 2017 to 2020 |
| Front crash prevention, with optional equipment | Superior | 2020 |
| Child seat anchors | Acceptable | 2015 to 2020 |
Source: IIHS ratings for the 2020 Chevrolet Impala.
The Superior front crash prevention rating applies only to cars with the optional automatic emergency braking and forward collision alert systems. NHTSA gave the 2020 Impala five stars for driver frontal protection, four stars for the front passenger, and four stars for rollover resistance. When you shop for a used 2014 to 2020 Impala, check whether it has that equipment.
Bottom line: The last Impalas protect occupants well in most IIHS tests, but their headlights were rated Poor, and automatic braking was an option, not standard.
Impala recalls to check
Study C lists 39 recall campaigns for Impalas from 1981 to 2019. Repairs are free at Chevrolet dealers. Run your vehicle identification number through NHTSA’s recall lookup to find any still open.
SELECTED IMPALA RECALLS
- 2006 to 2014 models: A heavy key ring or a jolt can turn the ignition out of run, cutting engine power and possibly preventing airbag deployment. The remedy is new key rings and an insert or key cover.
- 2000 to 2004 models: Engine oil can leak onto the exhaust manifold and start a fire. Dealers replace the valve cover and gasket under an improved remedy.
- 2014 and 2015 models: The electronic parking brake may not fully release, creating a fire risk from dragging pads. Dealers update the software.
- 2014 and 2015 models: The passenger airbag may deploy with a child seat in front. Dealers recalibrate the occupant sensor.
- 2014 models: A poor electrical ground can cause loss of power steering assist, and some cars had airbag modules left in manufacturing mode.
- 2018 and 2019 models: Gas pockets in the rear brake calipers can reduce rear braking. Dealers bleed the brakes.
Source: NHTSA campaign records as compiled in Study C’s recall list, November 2026.
Insuring an Impala SS
Three different cars wore the SS badge in the modern era: the 1994 to 1996 V8 sedan that briefly brought the Impala name back, the supercharged V6 SS of 2004 and 2005, and the 303-horsepower, 5.3-liter V8 SS sold from 2006 to 2009. None of the rate studies price an SS separately.
2004 to 2009 SS
These cars now list for roughly the same prices as other Impalas of their age, about $2,600 to $4,000 in Study C. For most, the choice is between liability only and full coverage, as with any older Impala. Tell the insurer it is an SS, because the engine affects the quote.
1994 to 1996 SS
The rear-wheel-drive V8 SS of the mid-1990s has a following among enthusiasts. If yours is kept in good condition and driven only occasionally, ask about an agreed-value collector policy, which pays a value you and the insurer settle on in advance rather than a depreciated market value.
Classic Impalas, 1958 to 1985
The Impala debuted as a premium Bel Air model for 1958 and became its own model in 1959, and the 1960s SS with the 409-cubic-inch V8 is among the best-known Chevrolets of the era. Some of these cars qualify for collector policies; others may be insured on standard auto policies depending on use, condition and insurer eligibility. None of the sources in this guide price them.
Collector policies typically require that the car is not your daily driver, that it is stored securely, and that you have another vehicle for regular use. In return, they often cost less than standard coverage and pay an agreed value. Get an appraisal and photos before you buy one.
Bottom line: Compare collector-policy eligibility, actual-value terms and usage restrictions for an older SS or classic Impala; do not assume every vehicle qualifies.
The Impala Limited and police Impalas
When the tenth-generation Impala arrived for 2014, Chevrolet kept building the previous car as the Impala Limited and sold it only to fleet customers through 2016. Study C does not yet have enough loss records to estimate a premium for it. If you buy one, expect a former fleet car, and get a history report and a quote by vehicle identification number.
Chevrolet also sold Impalas with a police package, known as 9C1, with heavy-duty suspension and the 3.8-liter engine on 2000 to 2005 cars. A former police Impala may be eligible for a personal policy, but eligibility and underwriting vary. Disclose its use history and remaining modifications.
The Chevrolet Caprice PPV
The Caprice PPV was a rear-wheel-drive police car sold from the 2011 model year, offered with a 6.0-liter V8 rated at an estimated 355 horsepower and a V6 added for 2012. GM said it was not based on an existing civilian model sold in North America, and it served as a large police sedan alongside the Impala police package.
Retired Caprice PPVs now reach the public through government auctions. If you buy one, tell the insurer it is a former police vehicle, give the vehicle identification number, and get a history report. None of the studies price the Caprice PPV, and some insurers may ask about leftover police equipment or modifications.
PRO TIP #3
Before you bid on a retired police car, get an insurance quote using the vehicle identification number from the auction listing, so the premium does not surprise you after the sale.
Bottom line: An ex-police Caprice or Impala should be quoted by vehicle identification number, with any equipment or changes disclosed.
Five-year cost of a new Impala
Five-year cost of owning a new Impala, Study D
| Cost | Five years | Per year |
| Depreciation | $15,458 | $3,092 |
| Insurance | $12,010 | $2,402 |
| Fuel | $11,620 | $2,324 |
| Loan interest | $5,504 | $1,101 |
| Maintenance and repairs | $2,095 | $419 |
| Total | $46,687 | $9,337 |
Historical new-vehicle ownership-cost scenario published in 2026, not a 2026 or 2027 Impala available for sale. Assumes a $31,323 vehicle with 3.6-liter V6, 40-year-old with good credit, 12,000 miles per year, 72-month loan at 6.99% and 20% down. Model year is unspecified; do not apply its amounts to used Impala ownership.
Insurance is the second-largest cost in Study D’s estimate, after depreciation, which takes about 49% of the car’s price over five years. For a used Impala, depreciation slows, so insurance becomes a bigger share of what you spend.
Bottom line: Insurance is about a quarter of the Impala’s five-year cost in Study D, so shopping the policy each year pays off.
Buying a used Impala: insurance checklist
- Get quotes by vehicle identification number, including the generation, engine, and trim.
- Check for open recalls, especially the ignition key recall on 2006 to 2014 cars.
- Run a history report for fleet, rental, police, salvage, or flood use.
- On a 2017 or older Impala, compare liability-only and full-coverage quotes.
- Set up coverage before you drive the car home.
Impala insurance by state
Study C adjusts its national estimate for each state. Florida and Louisiana top the list at close to $2,900 a year, while Maine is lowest at $1,346.
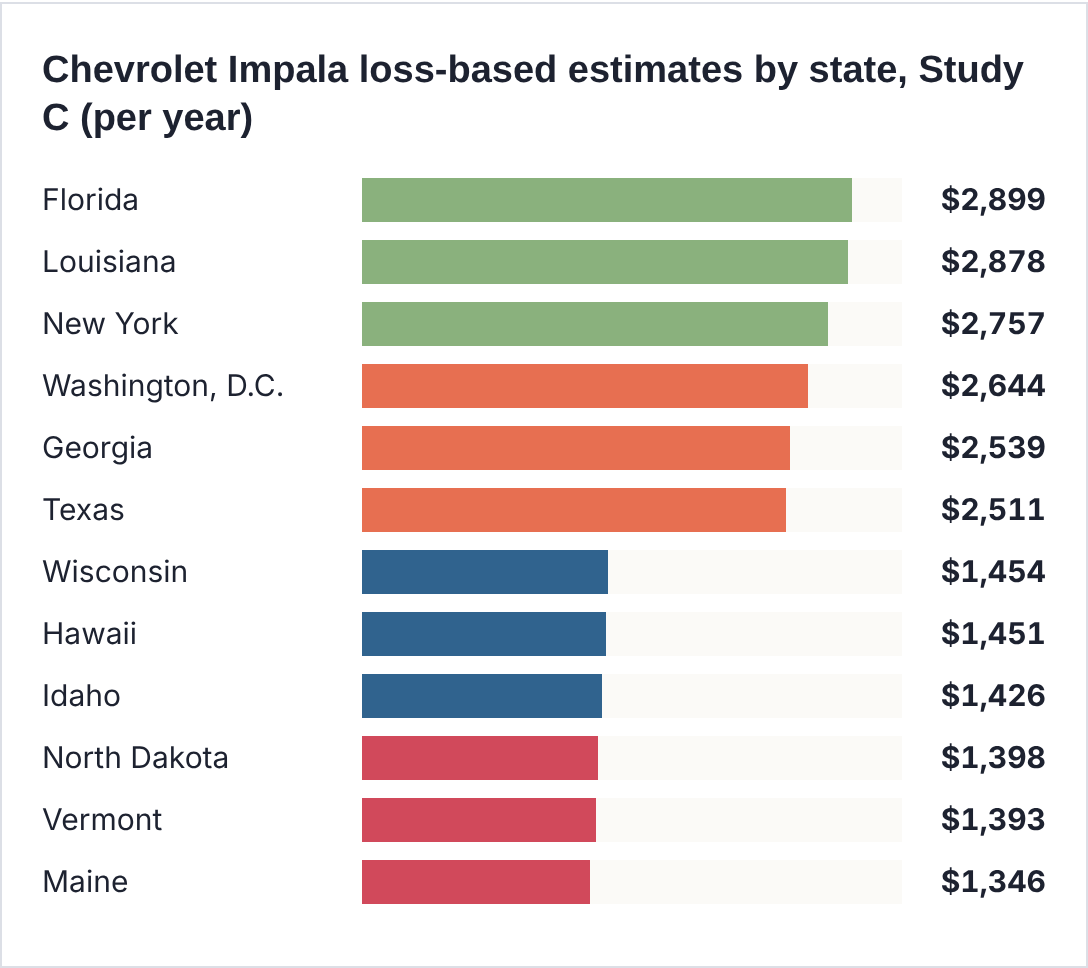
Full coverage estimate for 2018 to 2020 models. Source: Study C, November 2026.
A Florida driver’s estimate is more than twice a Maine driver’s. Study B’s Florida company prices, which run from $2,378 to $6,657, show how much the company choice matters in an expensive state.
Bottom line: Impala owners in Florida, Louisiana, New York, and Georgia have the most to gain from comparing companies.
Tickets, accidents, and a DUI on an Impala policy
None of the Impala studies publish prices after a violation. Study B’s publisher reports national average increases for common violations, and applying them to Study A’s $2,327 average for a 2020 Impala gives a rough guide.
Estimated Impala premium after a violation, based on Study B
| Violation | Average increase | Estimated yearly premium | Estimated added cost |
| Clean record | None | $2,327 | None |
| Speeding, 1 to 10 mph over | 26% | $2,932 | $605 |
| Speeding, 11 to 29 mph over | 34% | $3,118 | $791 |
| Speeding, 30 mph or more over | 39% | $3,235 | $908 |
| At-fault accident, under $2,000 in damage | 52% | $3,537 | $1,210 |
| At-fault accident, over $2,000 in damage | 53% | $3,560 | $1,233 |
| At-fault accident with injuries | 60% | $3,723 | $1,396 |
| Reckless driving | 82% | $4,235 | $1,908 |
| DUI or DWI, first offense | 90% | $4,421 | $2,094 |
Our estimates apply all-vehicle average increases, which assume a 40-year-old with 100/300/100 limits and a $500 deductible, to Study A’s 2020 Impala average for a 30-year-old. Actual increases vary by company and state. Source: Study B, September 1, 2025. These projections combine incompatible profiles and should not be used as personalized pricing estimates.
Bottom line: A DUI or speeding violation may materially increase the price, but the illustrative figures above combine different driver profiles and should not be treated as Impala-specific forecasts.
Impala insurance for teenage drivers
A used Impala may have a low purchase price, but its suitability for a novice driver also depends on crashworthiness, safety equipment, condition and total ownership costs. No Impala study publishes teen prices, so these figures come from national data.
Chevrolet Impala insurance at age 16
Adding a 16-year-old to a parent’s policy costs about $4,050 a year on average in Study E. A separate policy costs far more: GEICO is the cheapest national company for a 16-year-old in Study B at $8,436.
Chevrolet Impala insurance at age 17
Adding a 17-year-old costs about $3,740 a year in Study E. On a separate policy, GEICO again leads Study B at $6,937.
Chevrolet Impala insurance at age 18
Adding an 18-year-old costs about $3,478 a year in Study E, $572 less than at 16. Study E does not price an Impala for an 18-year-old, but for the Malibu, another longtime Chevrolet sedan, it puts an 18-year-old at $9,529 a year on their own policy, about 3.3 times a 40-year-old’s price.
Chevrolet Impala insurance at age 19
Adding a 19-year-old costs about $3,105 a year in Study E. For a separate policy, Travelers is cheapest in Study B at $4,465.
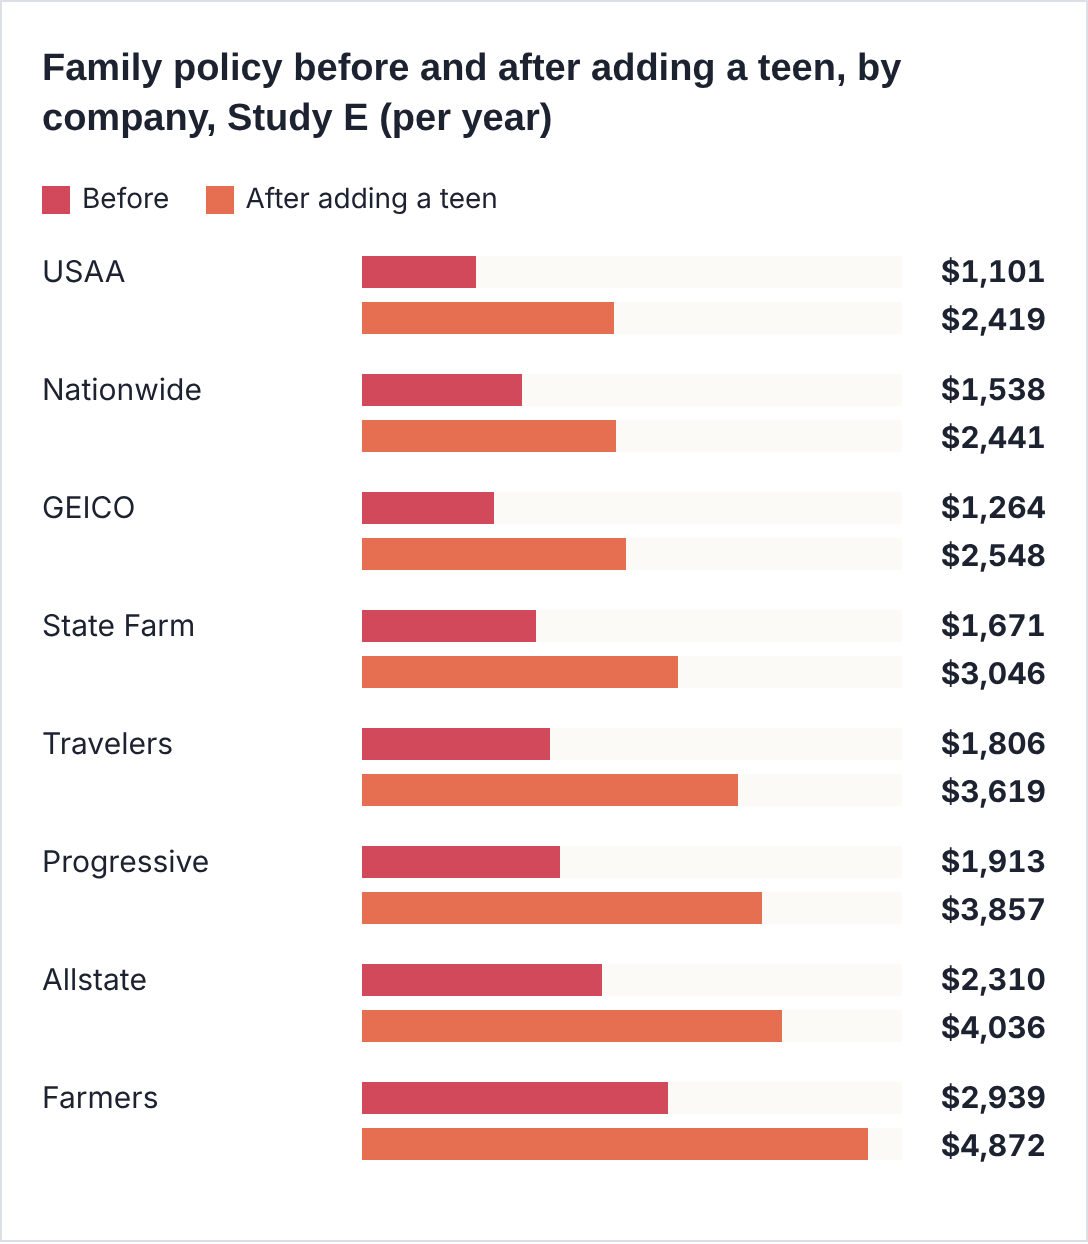
National data, no specific test vehicle. Source: Study E, cost of adding a teen driver, August 4, 2026.
Nationwide adds the least, $903 a year. USAA, the cheapest Impala company in Study A, adds $1,318, and State Farm, the leader in Study B’s Florida figures, adds $1,375.
PRO TIP #4
Compare the teen’s actual family-policy quote with and without collision, and check vehicle safety and your ability to replace it. Do not remove physical-damage coverage solely because the car is old.
Bottom line: Keep a teen on the family policy, and compare Nationwide, USAA, and GEICO.
Impala insurance for seniors and military families
Drivers 65 and older
Study E’s national figures show full coverage of $2,353 a year at 65, $2,498 at 70, and $2,742 at 75. Travelers is the cheapest company open to everyone for drivers 65 to 75, at $1,987. The Hartford, which sells to AARP members, lists 10% off for membership and 5% more for a defensive driving course.
Military members and veterans
USAA is the cheapest Impala company in Study A for eight of 10 model years. In Study E’s national comparison, all nine companies checked charged military members less than civilians, with USAA at $1,465 for military members against $1,572 for civilians. GEICO lists up to 15% off for military members and 25% when deployed, and USAA offers up to 60% off a stored vehicle, except in North Carolina and Virginia.
Bottom line: Military families should start with USAA, and drivers over 65 should compare Travelers and The Hartford.
Driving an Impala for rideshare
Uber required a 2010 or 2011 or newer vehicle in most of the 52 areas one 2026 review checked, and Lyft lists 2010 or newer for most states, so many 2006 to 2009 Impalas no longer qualify. If yours does, add a rideshare endorsement before driving, since a personal policy can exclude or limit coverage while an app is on.
10 discounts Impala owners can ask about
Each discount below is listed on the insurer’s website. Amounts are averages or maximums and vary by state.
1. Home and auto bundle
Nationwide reports average bundling savings of $1,032 a year, Progressive more than $1,000, and The Hartford $963. Farmers lists 10% or more.
2. More than one car
GEICO lists up to 25% off for multiple vehicles, and Progressive says multi-car customers save 12% on average.
3. Safe-driving apps
State Farm’s Drive Safe & Save and Liberty Mutual’s RightTrack offer up to 30%. USAA’s SafePilot and Nationwide’s SmartRide give 10% to start, and Progressive says Snapshot drivers save $328 a year on average.
4. Pay per mile
An Impala kept as a second car may benefit from a mileage-based program, where available. Compare the base charge, mileage charge and availability rather than assuming savings.
5. Good students
State Farm offers up to 25%, GEICO up to 15%, and Progressive about 5% for good grades. Travelers requires at least a B average.
6. No accidents
GEICO lists up to 22% after five accident-free years, and Travelers offers a safe driver discount.
7. Airbags and anti-lock brakes
Every modern Impala has anti-lock brakes and airbags. GEICO lists 5% for anti-lock brakes, and State Farm up to 40% off some medical coverages for factory airbags.
8. Early quotes and full payment
Travelers rewards shopping before your policy expires and paying in full. The Hartford lists 8%, and Progressive about 7% for quoting online.
9. Defensive driving
The Hartford offers 5% for a defensive driving course, and Travelers has a driver training discount for young drivers.
10. Military and AARP
GEICO offers up to 15% to military members, and The Hartford gives AARP members 10%.
Bottom line: Bundling, a second car, and a driving app carry the biggest published savings, and a pay-per-mile plan can suit an Impala that mostly stays parked.
Impala insurance myths
MYTH VS. FACT
- Myth: A family sedan always has a good claims record. Fact: Study C gives 2018 to 2020 Impalas a loss index of 145.
- Myth: The newest Impala is the best value to insure. Fact: In Study A, every older model year costs less than the one after it.
- Myth: Every company prices an Impala about the same. Fact: Study B’s Florida comparison runs from $2,378 to $6,657.
- Myth: An SS or classic Impala needs a standard policy. Fact: A clean, rarely driven one may qualify for agreed-value collector coverage.
Five mistakes Impala owners make
- Paying for collision on a $3,000 Impala without pricing liability only.
- Cutting injury coverages on a car whose injury losses run well above average.
- Skipping the ignition key recall check on a 2006 to 2014 car.
- Buying an ex-police or fleet Impala without a history report.
- Taking one quote when Study A’s 2020 prices run from $1,673 to $3,077 a year.
Five steps to the cheapest Impala insurance
- Note the model year, generation, engine, trim, and vehicle identification number.
- Decide whether the car’s value justifies collision and comprehensive.
- Quote USAA if you qualify, then American Family, State Farm, and Progressive, and Erie where it sells.
- Choose strong liability limits and the same deductible on every quote.
- Ask about bundling, multi-car, telematics, and good student discounts, and shop again at each renewal.
The Impala insurance story in six panels
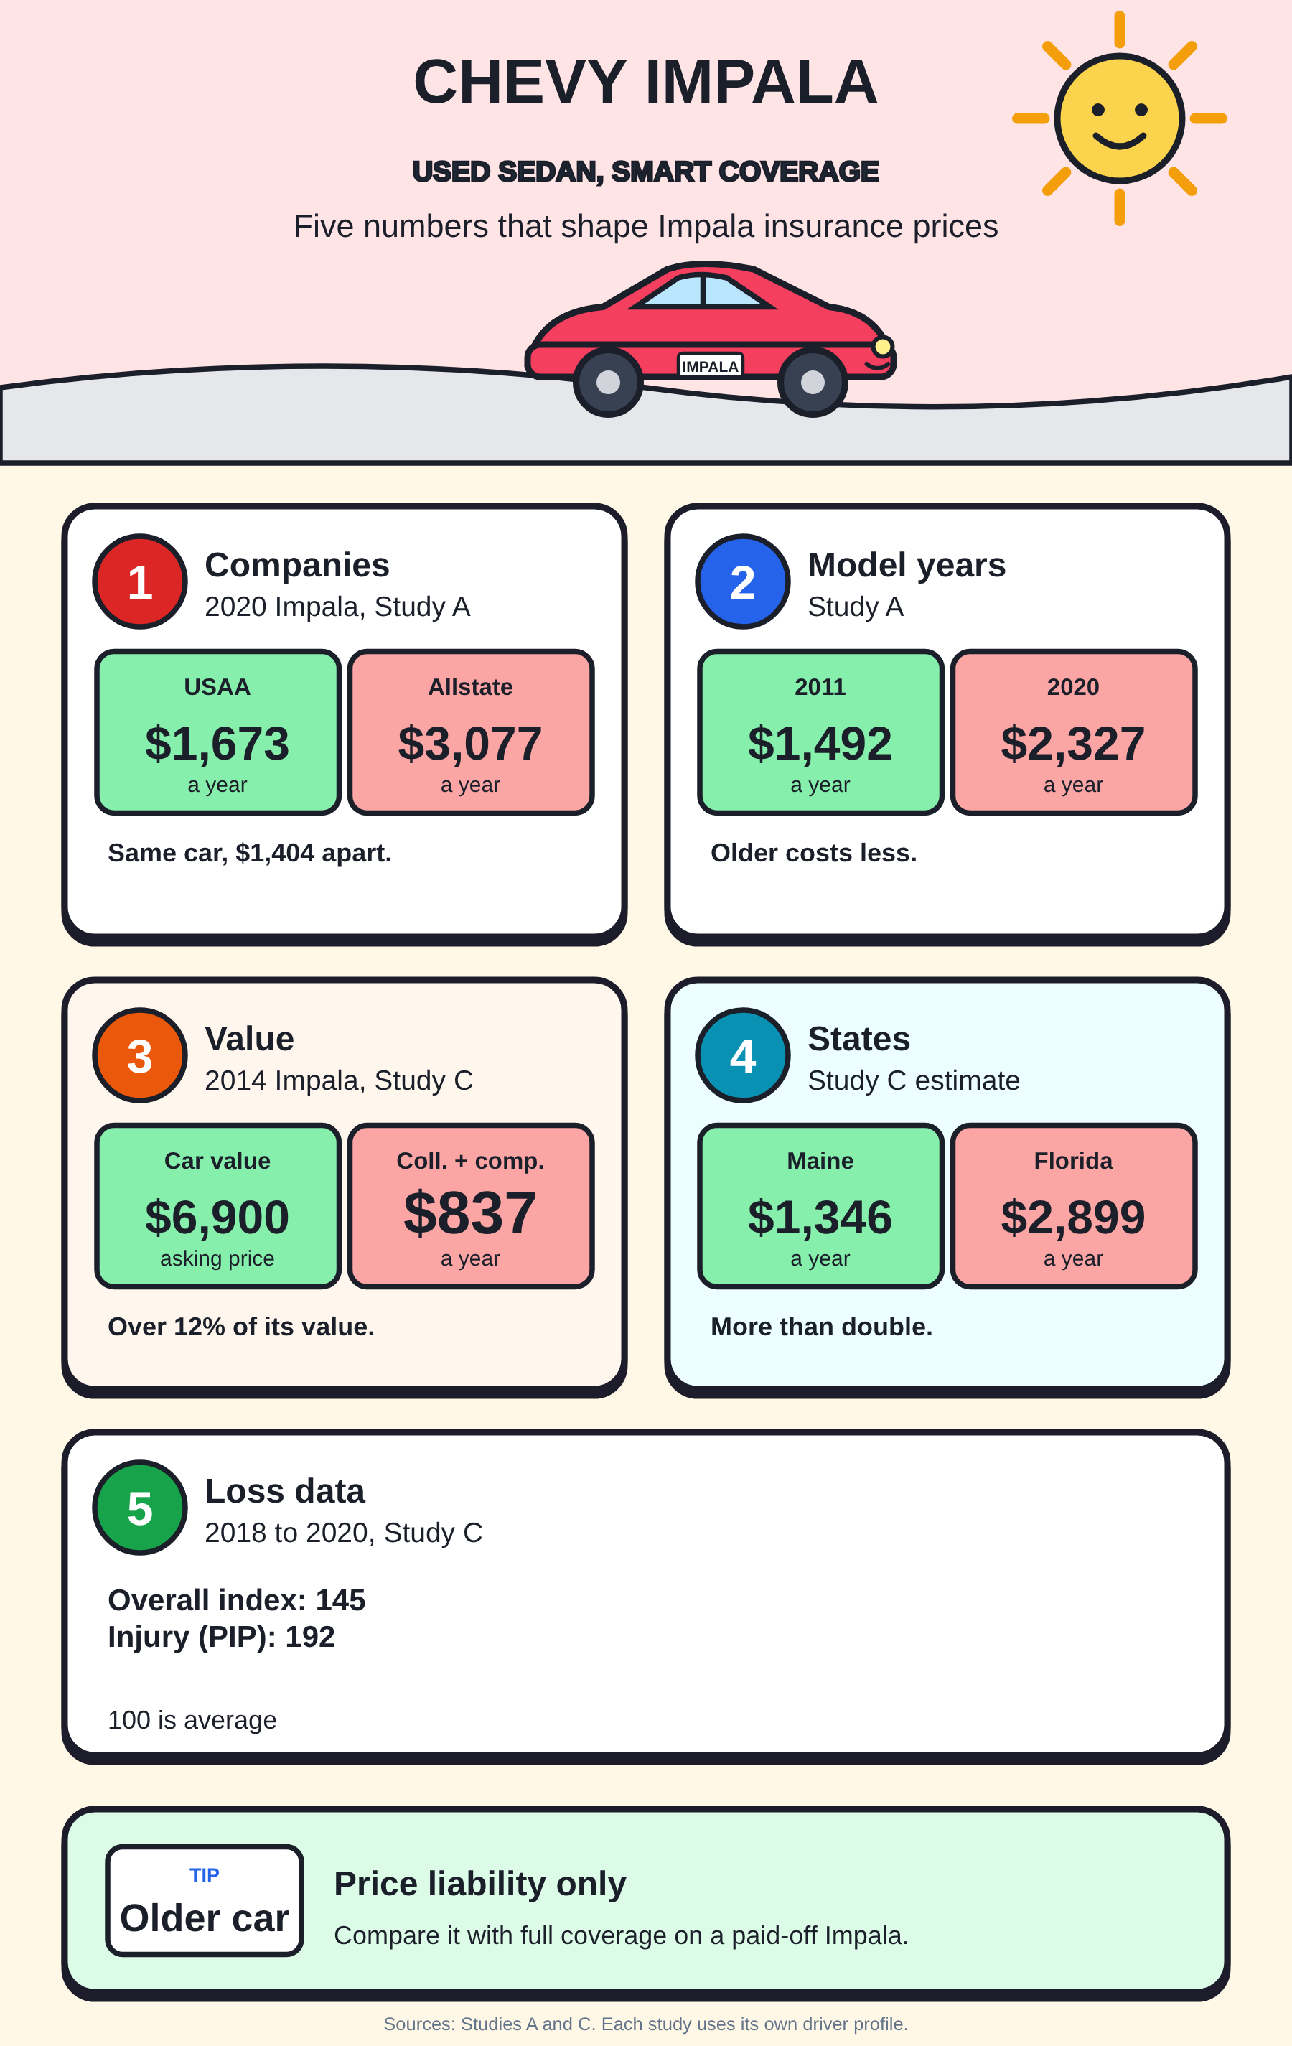
An original cartoon summary of the main Impala insurance numbers.
Frequently asked questions about the cheapest Chevrolet Impala insurance
Who has the cheapest Chevrolet Impala insurance?
USAA, at $1,673 a year for a 2020 Impala in Study A, for military families. American Family is cheapest for everyone else at $1,722.
How much is Impala insurance per month?
About $152 a month on average across model years in Study A, and $194 a month for a 2020 Impala.
Is the Chevrolet Impala expensive to insure?
Older ones are not. A 2011 averages $1,492 a year in Study A. The 2018 to 2020 cars have a high loss index of 145 in Study C, which pushes their prices up.
Which Impala model year is cheapest to insure?
The 2011, the oldest year Study A prices, at $1,492 a year on average and $1,058 with USAA.
Should I drop full coverage on my Impala?
Compare both on any Impala from 2017 or earlier. Study C’s collision and comprehensive estimate is more than 10% of the typical asking price for those years.
Is the Impala SS more expensive to insure?
No study prices it separately. Tell the insurer it is an SS, and consider a collector policy for a clean 1994 to 1996 SS.
Which Impala model year is the most expensive to insure?
The 2020, at $2,327 a year on average in Study A, $185 more than a 2019.
How do I insure an Impala Limited?
Quote it by vehicle identification number. It was sold only to fleets from 2014 to 2016, and no study prices it yet.
Does the engine affect Impala insurance?
None of the studies price engines separately, but insurers quote by vehicle identification number, which records the engine. Tell the insurer if your Impala has the V6 or V8.
Who has the cheapest Impala insurance in Florida?
State Farm, at $2,378 a year in Study B’s Florida comparison, followed by Travelers at $2,568.
Which state has the cheapest Impala insurance?
Maine, at an estimated $1,346 a year in Study C, followed by Vermont and North Dakota.
How much is Impala insurance for a teenager?
Adding a 16-year-old to a family policy costs about $4,050 a year nationally in Study E, while a separate policy for a 16-year-old starts at $8,436 in Study B.
Can I insure a former police Impala or Caprice?
Yes. Quote it by vehicle identification number, tell the insurer it was a police car, and get a history report.
How do I insure a classic 1960s Impala?
Usually with a classic or collector policy that pays an agreed value. Most require secure storage and another car for daily use.
Is the Chevrolet Impala safe?
The 2014 to 2020 Impala rated Good in IIHS moderate overlap, side, and roof strength tests and Acceptable in the driver-side small overlap test, but its headlights rated Poor.
Who has the cheapest Impala insurance in California?
GEICO, at $139 a month for a 2020 Impala and $102 for a 2011 in Study F.
When did Chevrolet stop making the Impala?
The last Impala was built on February 27, 2020, at the Detroit-Hamtramck plant.
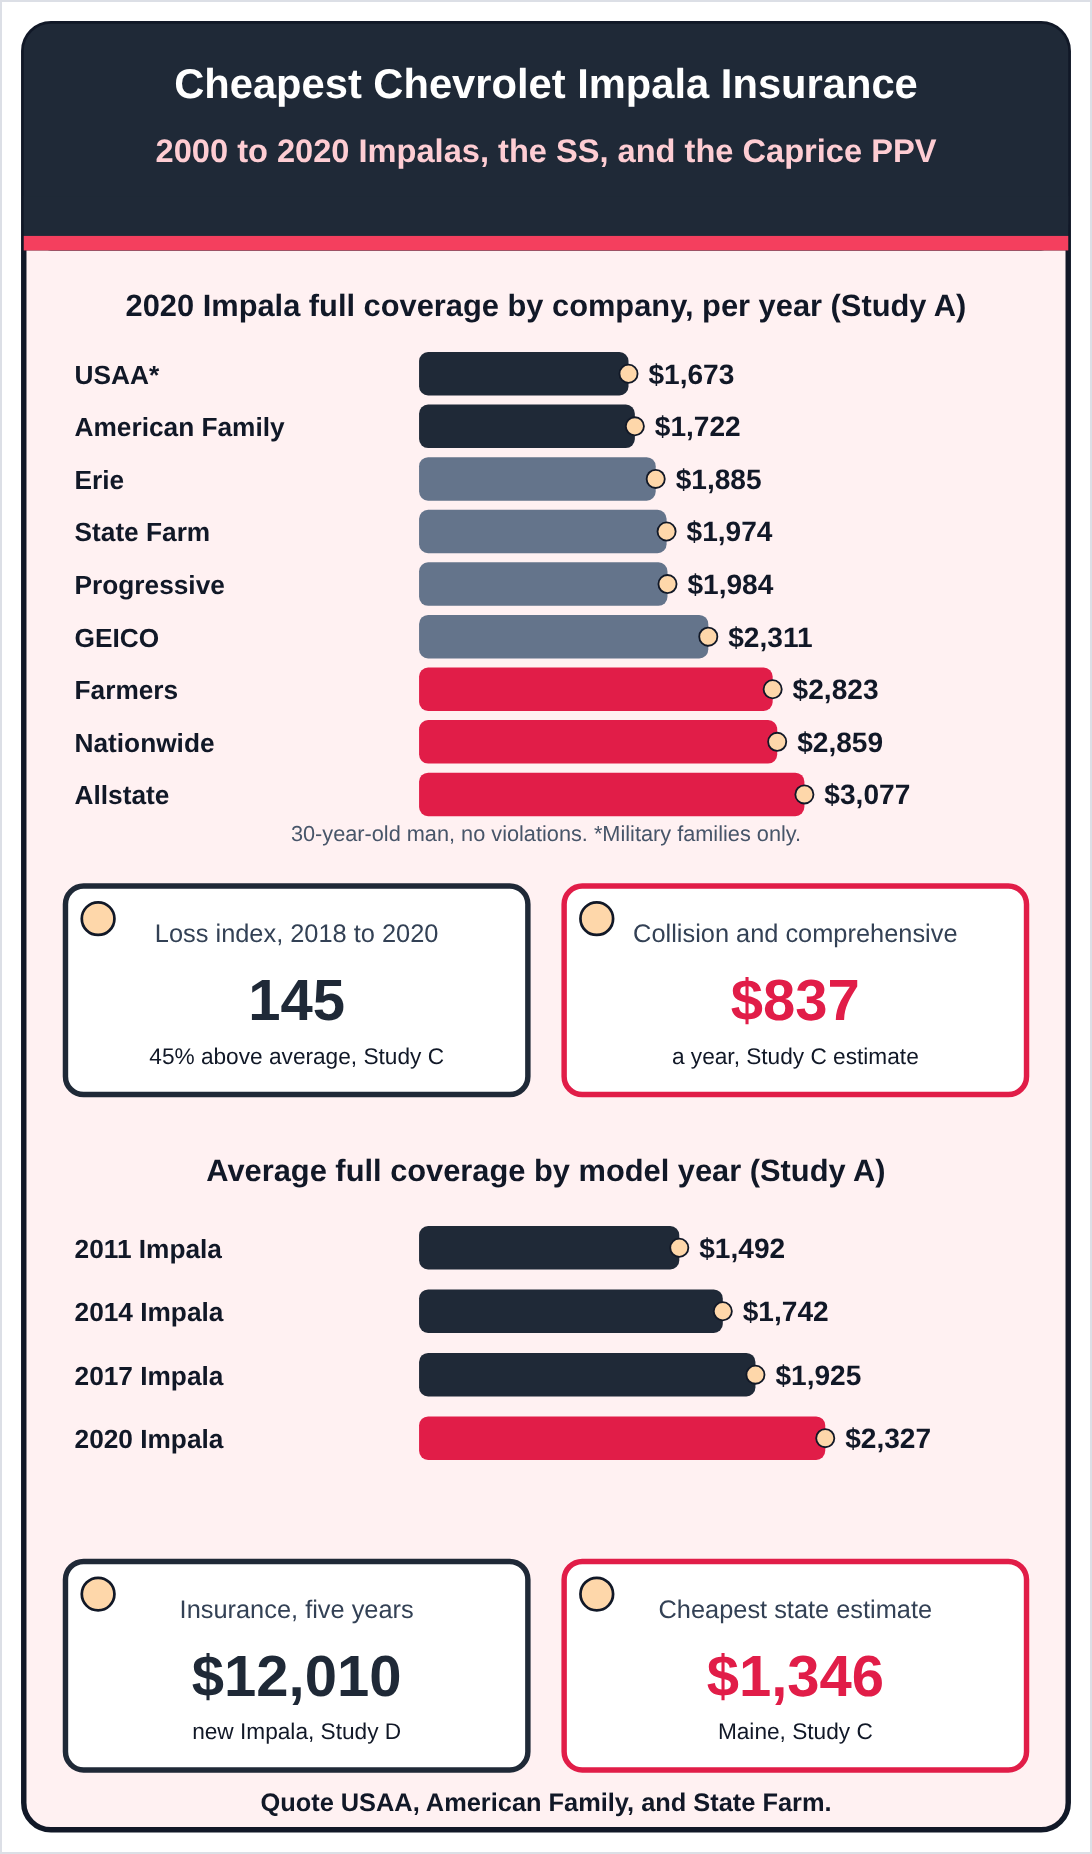
Chevrolet Impala insurance in one graphic.
The final word on the cheapest Chevrolet Impala insurance
The Impala is now a used car only, and that shapes the best way to insure it. Older model years cost steadily less in Study A, USAA and American Family lead on price, and for many cars the real saving comes from dropping collision and comprehensive once the car is worth only a few thousand dollars.
The final 2018 to 2020 cars are the exception: their losses run well above average, so compare several companies and keep strong injury coverage. Check the ignition key recall on 2006 to 2014 cars, quote any ex-police or fleet car by vehicle identification number, and consider agreed-value coverage for a clean SS or classic Impala.
Sources
- Study A: The Zebra, Chevrolet Impala insurance by model year and company (2025 data).
- Study B: Insurance.com, Chevrolet Impala car insurance (October 26, 2026), teen car insurance costs (August 13, 2026), and how much accidents and tickets increase insurance (September 1, 2025).
- Study C: ForCar, Chevrolet Impala insurance cost, used Chevrolet Impala prices, Chevrolet Impala recalls, and Chevrolet Impala Limited (November 2026), citing Highway Loss Data Institute figures.
- Study D: CarEdge, Chevrolet Impala ownership costs (2026).
- Study E: CarInsurance.com, Chevrolet car insurance cost (March 23, 2026); cost of adding a teen driver (August 4, 2026); car insurance for seniors (April 16, 2026); best car insurance for military members (August 13, 2026); top financially rated insurers (December 16, 2025); and insurers ranked by NAIC complaint data (August 13, 2026).
- Study F: Finder, Chevrolet Impala insurance rates.
- Service ratings: J.D. Power 2026 U.S. Auto Insurance Study coverage (June 9, 2026); J.D. Power 2026 regional scores; Amica, J.D. Power 2026 results; and J.D. Power 2026 Auto Claims Satisfaction Study coverage (October 27, 2026).
- Insurer pages: Travelers discounts; Progressive discounts; GEICO discounts; GEICO military discounts; State Farm discounts; Nationwide discounts; Nationwide SmartMiles; Liberty Mutual RightTrack; Farmers discounts; USAA discounts; The Hartford AARP discounts; and Lemonade, pay-per-mile car insurance.
- Rideshare: Uber and Lyft car requirements for 2026.
- Vehicle history: SlashGear, why Chevrolet discontinued the Impala; Hagerty, Chevrolet Impala production ends (February 27, 2020); CarGurus, Chevrolet Impala buying guide; and Wikipedia, Chevrolet Impala.
- Caprice PPV: Government Fleet, Chevrolet debuts all-new 2011 Caprice police patrol vehicle (November 9, 2009).
- Safety: IIHS ratings, 2020 Chevrolet Impala, and NHTSA ratings for the 2020 Impala as compiled by CarComplaints.
- Recalls: NHTSA recall lookup.
- AM Best, Erie rating affirmed A, September 2026
- AM Best, State Farm rating downgrade to A+, November 2025
- Chevrolet 2012 Impala standard equipment guide
Disclaimer
This guide brings together a premium study by company and model year, an insurer comparison from a state tool, insurance-loss estimates, used-car asking prices, recall records, an ownership-cost model, national figures for teens, seniors, military families, and violations, and service and financial ratings for the Chevrolet Impala, with background on the SS, the Impala Limited, classic Impalas, and the Caprice PPV. Each source sets its own driver, coverage, and date, so figures from different studies are not directly comparable.
Several limits apply. Study B’s company table is not labeled with a state, year, or trim, and we treat it as a Florida guide based on the tool’s defaults.
Study A’s rates are from 2025 and cover 2011 to 2020 models only. Study C’s loss data covers 2018 to 2020 cars, so its collision and comprehensive estimate may overstate the cost for older Impalas. No source priced trims, the SS, classic Impalas, the Impala Limited, or the Caprice PPV separately. Asking prices are listing medians, not sale prices.
Your premium will depend on your location, age, driving and claims history, credit where state law allows, household drivers, mileage, and use, and on your Impala’s year, engine, trim, condition, title, and history. Confirm coverage, exclusions, and discounts in writing. This guide is general information, not insurance, legal, or financial advice.
We are an independent publisher, not affiliated with General Motors, Chevrolet, the Highway Loss Data Institute, NHTSA, J.D. Power, AM Best, Uber, Lyft, or any insurer named here, including USAA, American Family, Erie, State Farm, Progressive, GEICO, Farmers, Nationwide, Allstate, Travelers, UAIC, Mercury, AIG, Auto-Owners, Liberty Mutual, The Hartford, and Lemonade. No company paid to appear, and the rankings reflect our reading of the published figures.
Chevrolet, Impala, Impala SS, Impala Limited, Caprice, Bel Air, and other names in this guide are trademarks of their respective owners.