
Cheapest Toyota Sequoia Insurance: Companies, Costs & Coverage
For a 2025 Toyota Sequoia, Study B reports an average full-coverage premium of $3,194 per year for its 40-year-old sample driver, with Travelers at $1,851 in the same study. Study A, using a different 30-year-old profile, lists Progressive at $1,741 and Allstate at $4,890. Those are published study estimates, not current personal quotes. Comparing them requires keeping the driver, model, liability limits and deductibles consistent.
The third-generation Sequoia arrived for the 2023 model year with Toyota’s i-FORCE MAX hybrid drivetrain: a 3.4-liter twin-turbocharged V6 coupled to an electric motor for 437 combined horsepower. The preceding 2008–2022 generation used a naturally aspirated V8. Many earlier vehicles remain in service; a model-year insurance comparison is not a controlled test of what a hybrid drivetrain adds to a premium.
This guide compares insurer quotes within their individual published studies, reviews 2026 and newly announced 2027 Sequoia equipment and MSRP, and explains coverage for older V8 and newer hybrid models. It also discusses independent safety tests, VIN-specific recalls, selected model and state estimates, discounts and the limits of national teen, senior and military-driver benchmarks.
Toyota Sequoia insurance at a glance
| Measure | Figure | Source |
| Average full coverage, 2025 Sequoia, 40-year-old | $3,194 a year ($266 a month) | Study B, Oct 2026 |
| Average liability-only (50/100/50) | $1,153 a year | Study B, Oct 2026 |
| Cheapest company, 2025 model, 40-year-old | Travelers, $1,851 a year | Study B, Oct 2026 |
| Cheapest company, 2025 model, 30-year-old | Progressive, $1,741 a year | Study A |
| Average for a 40-year-old, good credit | $2,154 a year | Study D |
| Average for an 18-year-old male driver | $10,254 a year | Study C, Mar 2026 |
| Average for a 2022 V8 model vs. a 2023 hybrid | $2,592 vs. $3,009 a year | Study B, Oct 2026 |
Each published study uses its own driver profile, model year, policy limits, deductible and data period. Compare insurers within the same study; do not rank quotes from different studies as if they describe the same insured driver. The original study names are retained in Sources.
Insurance companies to compare for a Toyota Sequoia
Studies A and B publish Sequoia-specific insurer prices but use different sample drivers; Study B also provides a separate Florida-only column. The table below keeps those datasets separate instead of claiming to rank ten carriers nationally. Availability, eligibility and individual premiums vary by state and driver. For more guidance on choosing limits and customizing a car insurance policy, compare the actual terms rather than just the advertised price.
2025 Sequoia full-coverage sample prices by insurer (not a combined ranking)
| Insurer | Study A, 30-year-old male | Study B, 40-year-old driver | Study B, Florida |
| Travelers | — | $1,851 | $2,336 |
| Progressive | $1,741 | $2,746 | $4,384 |
| USAA* | $2,043 | $2,139 | — |
| Nationwide | $2,167 | $2,549 | $2,166 |
| Erie | $2,603 | — | — |
| American Family | $2,750 | — | — |
| GEICO | $3,216 | $2,758 | $3,531 |
| State Farm | $2,787 | $2,790 | $2,573 |
| UAIC | — | — | $2,742 |
| Farmers | $3,802 | $4,049 | — |
| Allstate | $4,890 | $4,370 | $4,875 |
Full coverage. Study A: 30-year-old male, no violations. Study B: 40-year-old, 100/300/100 with a $500 deductible, October 2026; its Florida column is for a 2025 Sequoia in that state. *USAA sells only to military families.
Travelers
Within Study B’s published 2018–2025 Sequoia samples, Travelers had the lowest listed premium across those model years. A 2025 model was $1,851 annually in that study. Another source repeats a similar Travelers value but does not establish a second independent nationwide pricing comparison; request a current quote for the actual VIN.
Progressive
Progressive had the lowest 2025 Sequoia price in Study A, $1,741 a year, and it was cheapest there for the 2024 and 2023 models too. It ranks third in Study B, so a quote from both Progressive and Travelers is worth getting.
USAA
USAA was the second-cheapest company in both studies for a 2025 Sequoia, at $2,043 a year in Study A and $2,139 in Study B. Only military families can buy it.
Nationwide
Nationwide was $2,167 annually for Study A’s 2025 model and $2,549 for Study B’s national sample. In the separate Florida-only 2025 table, Nationwide led at $2,166; that regional observation does not make Nationwide the cheapest nationwide.
Erie
Study A reports Erie at $2,603 annually for its 2025 Sequoia sample, below that study’s stated model average. Its AM Best property/casualty financial-strength rating is A following a September 2025 downgrade. Erie operates only in its served states.
American Family
American Family costs $2,750 a year for a 2025 model in Study A, but it was the cheapest company in that study for most older Sequoias, every model year from 2014 to 2022.
GEICO
GEICO charges $2,758 a year in Study B for a 2025 Sequoia, the fifth-lowest there, but $3,216 in Study A.
State Farm
State Farm costs about the same in both studies, $2,787 in Study A and $2,790 in Study B, and it was the third-cheapest company in Study B’s Florida sample at $2,573.
UAIC
UAIC was reported at $2,742 annually in Study B’s Florida-only sample. No comparable national Sequoia quote for UAIC appears in these sources, so its Florida figure cannot establish a nationwide placement.
Farmers
Farmers costs $3,802 a year in Study A and $4,049 in Study B for a 2025 Sequoia. It lists home-and-auto bundle savings of 10% or more, which can narrow the gap for homeowners.
PRO TIP #1
Compare Travelers, Progressive and Nationwide on the same Sequoia VIN and coverage terms, along with USAA if eligible. Study A’s 2025 sample shows a $3,149 difference between Progressive and Allstate, but that does not predict an individual driver’s savings.
Sequoia insurers compared on service
For a family SUV that can cost more than $85,000, the claims experience matters as much as the premium. We checked the cheaper Sequoia insurers on J.D. Power’s 2026 satisfaction scores, AM Best financial strength ratings, and the NAIC complaint index, where 1.00 is the expected number of complaints for a company’s size.
Service ratings for leading Sequoia insurers
| Insurer | J.D. Power 2026 (regional range) | AM Best rating | NAIC complaint index |
| Travelers | 584 to 657 | A++ | 0.52 |
| Progressive | 604 to 645 | A+ | 0.71 |
| USAA* | 707 to 763 | A++ | 1.18 |
| Nationwide | 612 to 685 | A | 0.63 |
| Erie | 652 to 704 | A | 0.89 |
| American Family | 632 to 649 | A | 0.33 |
| GEICO | 631 to 668 | A++ | 0.69 |
| State Farm | 632 to 669 | A+ | 0.79 |
| Farmers | 558 to 675 | A | 0.86 |
| Allstate | 612 to 660 | A+ | 1.10 |
J.D. Power figures are regional satisfaction scores on a 1,000-point scale; a regional range is not a Kentucky, nationwide or Sequoia-specific claims rating. The NAIC indexes are national complaint measurements for the underlying insurer/reporting scope, not a prediction about a particular claim. Financial-strength grades refer to specific AM Best-rated entities or groups; State Farm Group was downgraded to A+ in November 2025, and Erie’s property/casualty members were downgraded to A in September 2025. USAA is ineligible for official ranking in the J.D. Power study because of its eligibility restrictions.
Best overall: Travelers
Travelers led Study B for eight straight model years, holds an A++ rating, and has a complaint index of 0.52.
Lowest price in Study A: Progressive
Progressive led Study A, which priced a 30-year-old, for the 2023 to 2025 models, and it holds an A+ rating.
Best for older Sequoias: American Family
American Family was cheapest in Study A for every model year from 2014 to 2022 and has the lowest complaint index in our table, 0.33.
Best claims service: Nationwide and Amica
Amica ranked first in J.D. Power’s October 2026 claims study with 775 points, and Nationwide was second with 743, against an average of 700.
Best for military families: USAA
USAA was second on price in both company studies for a 2025 Sequoia and scored 707 to 763 in every J.D. Power region.
PRO TIP #2
Ask each company about its rental car limit. If your Sequoia is in the shop, you may need a large SUV or minivan to carry eight people, and a low daily limit will not cover one.
Which insurer was cheapest in each Sequoia sample?
There is no single verified nationwide cheapest carrier for every Sequoia owner. Travelers had the lowest 2025 price within Study B for its 40-year-old sample, while Progressive led Study A for its 30-year-old sample. They are reasonable companies to quote first, not guaranteed winners. Consult the checklist for requesting auto insurance quotes before comparing offers.
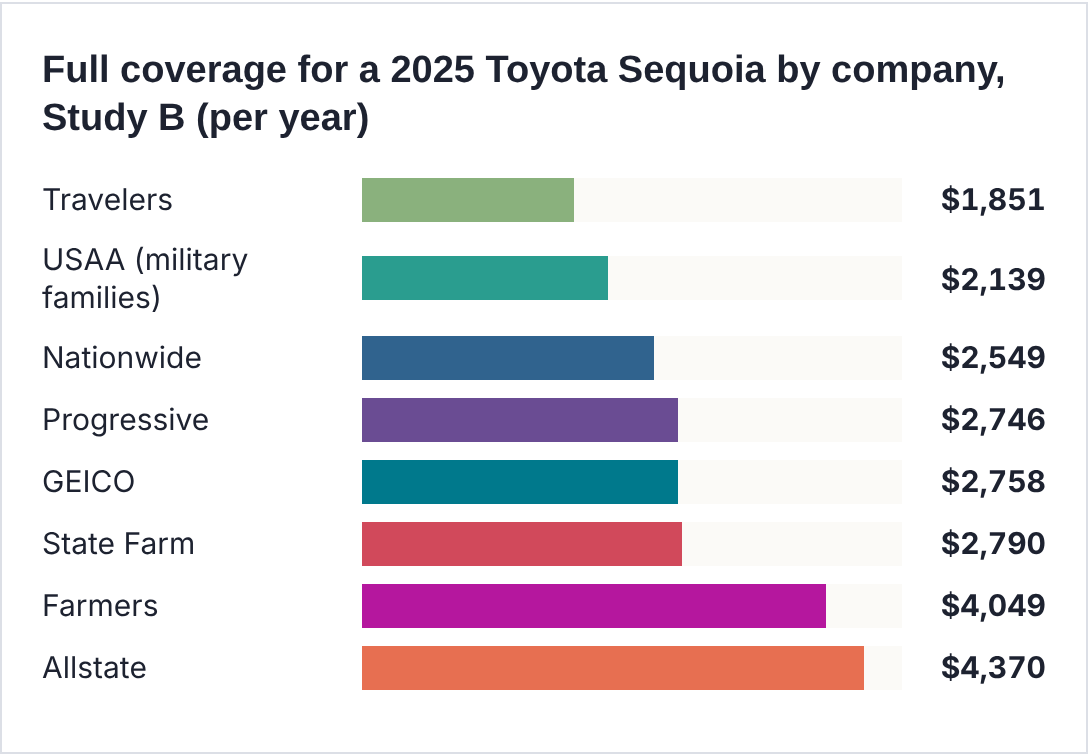
40-year-old driver, clean record, 100/300/100 with a $500 deductible. Source: Study B, Toyota Sequoia car insurance, October 26, 2026.
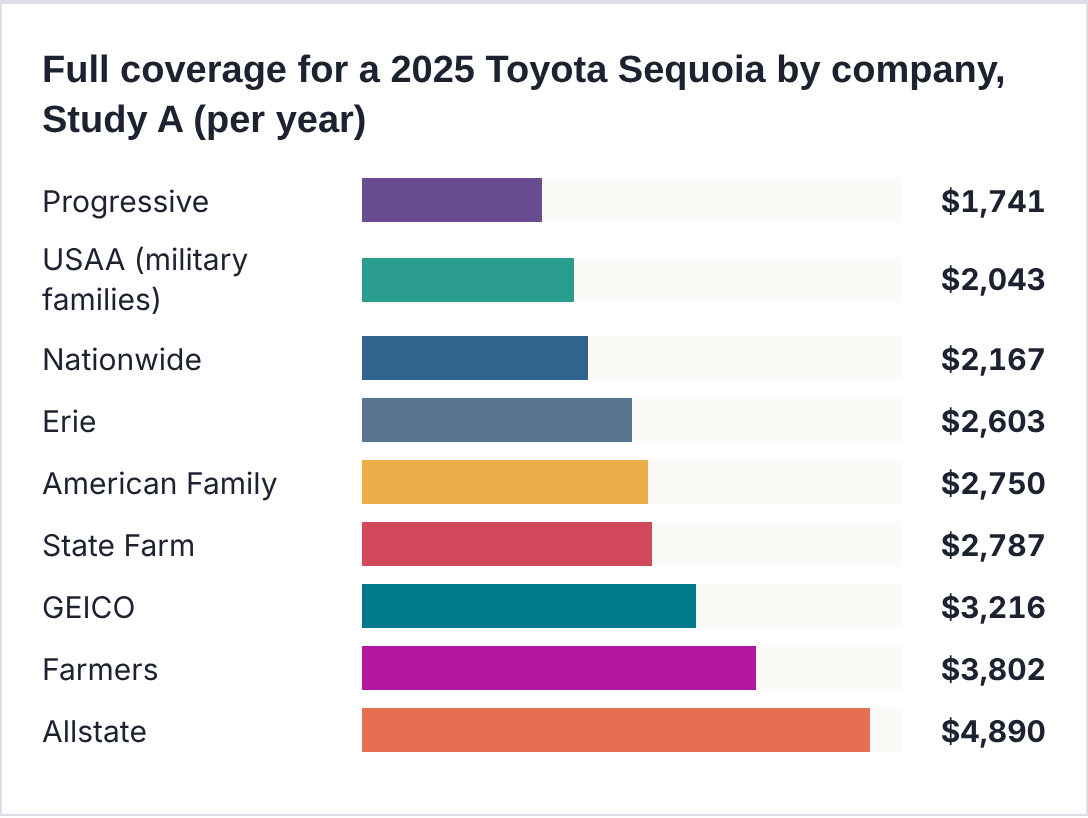
30-year-old male, full coverage, no violations. Source: Study A, Toyota Sequoia insurance.
How to get your lowest Sequoia quote
- Note your model year, trim, and drivetrain, and whether you have a 2023 or newer hybrid or an older V8.
- List every driver in the household, including teens.
- Get quotes from Travelers, Progressive, and Nationwide, plus USAA if you qualify and American Family for an older Sequoia.
- Compare the same limits at a $500 and a $1,000 deductible.
- Ask which discounts are included, and request any that are missing.
How we ranked these companies
The insurer comparisons use the Sequoia-specific rate tables of Studies A and B. These studies have different driver profiles, while Study B’s Florida numbers come from a single state. We do not calculate a combined insurer rank from them. The J.D. Power satisfaction survey, NAIC complaint metrics and AM Best financial-strength grades are separate measurements, not price quotes or a reproducible weighted score.
Toyota Auto Insurance
Toyota also sells its own coverage through Toyota Insurance Management Solutions, with claims support from Toggle, a Farmers company. At its last announced expansion, in 2023, it was available in 12 states, including Arizona, California, Colorado, Georgia, Illinois, Ohio, and Texas, and it can cover non-Toyota vehicles in your household. Add it to your quotes if it is sold where you live.
Why the Sequoia costs more to insure than other Toyotas
Within Study B’s selected Toyota SUV comparison, the Sequoia has the highest published sample annual premium. Other studies using different drivers, including Study D, produce substantially different averages. The results do not mean a Sequoia is always more expensive than another SUV to insure.
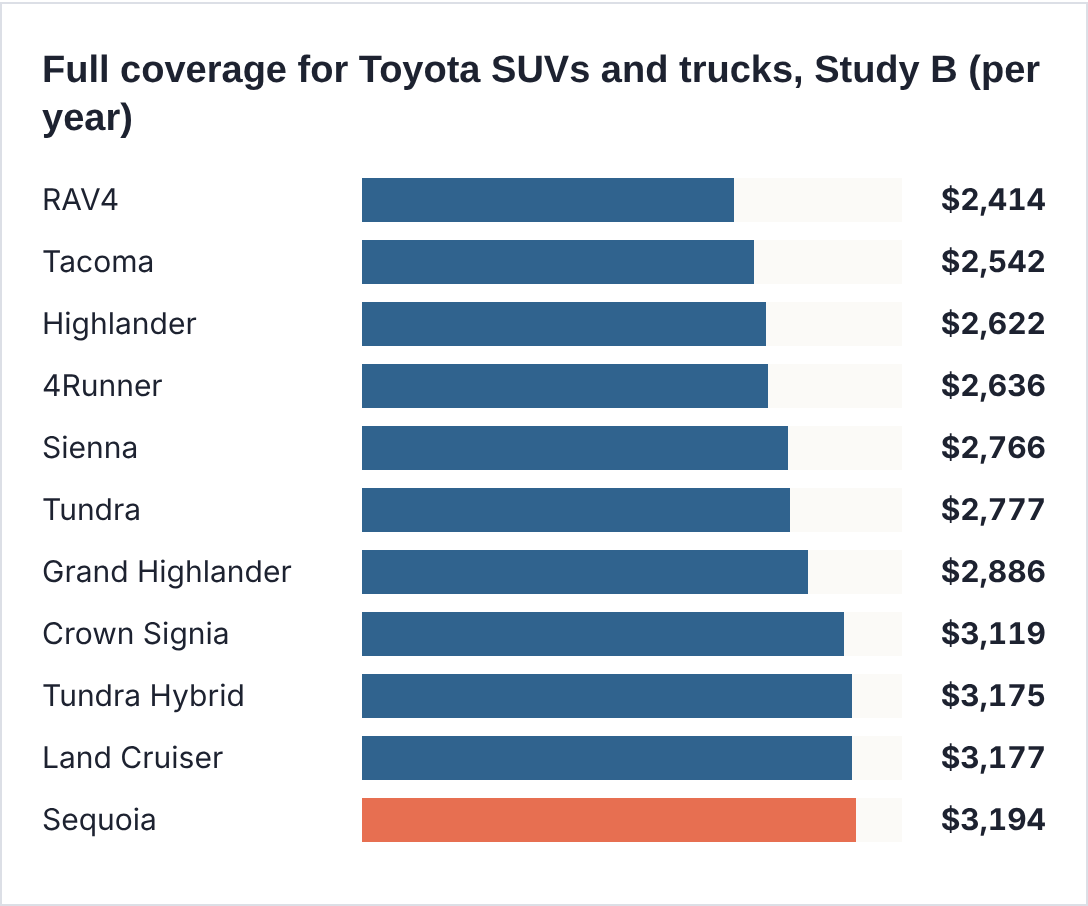
40-year-old driver, clean record, 100/300/100 with a $500 deductible. Source: Study B, Toyota insurance, October 26, 2026.
Three things drive the price:
- Its price. A 2026 Sequoia runs from $66,120 to $86,530 with destination, so collision and comprehensive coverage protect a lot of value.
- Its size and power. The Sequoia is a heavy, 437-horsepower body-on-frame SUV built on the same platform as the Tundra pickup.
- Its hybrid system. Every 2023 and newer Sequoia uses the i-FORCE MAX hybrid, which adds electric parts to repair after a serious crash. The Tundra Hybrid, which shares this powertrain, costs $3,175 a year in Study B, nearly the same as the Sequoia.
Not every driver pays that much. Study D’s figure for a 40-year-old with good credit is $2,154 a year, and Study A’s average for a 30-year-old is $2,917, so your profile and company choice still matter most.
Insurance estimates before and after the 2023 redesign
Both studies show higher published sample premiums for the 2023 Sequoia than for the 2022 model: Study B lists $3,009 versus $2,592, and Study A lists $2,722 versus $2,239. The model year also changes the vehicle’s age, replacement value, design and equipment. These numbers cannot isolate a hybrid-system surcharge or prove that the drivetrain caused the increase.
2022 V8 vs. 2023 hybrid Sequoia, Study A (per year)
| Insurer | 2022 V8 | 2023 hybrid | Change |
| Progressive | $1,758 | $1,818 | +$60 |
| USAA* | $1,988 | $2,022 | +$34 |
| Nationwide | $1,725 | $2,236 | +$511 |
| Erie | $1,868 | $2,562 | +$694 |
| American Family | $1,703 | $2,478 | +$775 |
| State Farm | $2,136 | $2,370 | +$234 |
| GEICO | $2,283 | $2,947 | +$664 |
| Farmers | $3,267 | $3,498 | +$231 |
| Allstate | $3,152 | $4,348 | +$1,196 |
| Average | $2,239 | $2,722 | +$483 |
30-year-old male, full coverage. Changes are our subtraction. *USAA sells only to military families. Source: Study A.
In Study A, Progressive’s published 2022-to-2023 sample difference was $60 and USAA’s $34, much smaller than the changes reported for some other insurers. Such results are not a promise that their rates will remain stable for another driver.
PRO TIP #3
Before replacing an older Sequoia with a newer hybrid, obtain a VIN-specific insurance quote. Study A’s published average rises $483 from the 2022 to the 2023 model, but your own renewal price could move differently.
Liability-only coverage for a Sequoia
Liability-only coverage pays for injuries and damage you cause to others but nothing for your own SUV. Study B puts 50/100/50 liability on a Sequoia at $1,153 a year, about $96 a month.
Liability-only (50/100/50) vs. full coverage for large Toyota SUVs, Study B (per year)
| Model | Liability only | Full coverage | Gap between differently covered sample policies* |
| 4Runner | $1,110 | $2,636 | 58% |
| Grand Highlander | $1,134 | $2,886 | 61% |
| Land Cruiser | $1,105 | $3,177 | 65% |
| Sequoia | $1,153 | $3,194 | 64% |
40-year-old clean-record sample driver; source: Study B, October 2026. *The percentage is (full-coverage premium minus 50/100/50 liability-only premium) divided by the full-coverage premium. The full-coverage policy also uses higher liability limits (100/300/100) and adds other terms, so the percentage is NOT a collision-and-comprehensive premium share. These are separate policy comparisons, not component-level premiums.
Study B reports Sequoia liability-only at $1,153 annually, versus $1,105–$1,134 for the three other listed models. The difference between liability-only and full coverage, however, includes higher liability limits and potentially other coverages. The table cannot allocate the difference solely to collision and comprehensive. See the guide to liability, collision and comprehensive coverage for the actual distinctions.
When liability-only makes sense
Liability-only generally leaves substantial vehicle value unprotected on recent Sequoias, and a financing or lease contract typically requires collision and comprehensive. On a paid-off older Sequoia, compare the actual physical-damage premium, deductibles, market value, risk of theft or storm loss and ability to replace the vehicle before deciding to drop either coverage.
PRO TIP #4
An eight-seat SUV can injure several people in one crash, so even if you drop to liability-only on an older Sequoia, keep limits of at least 100/300/100 and add uninsured motorist coverage.
Full coverage for a Toyota Sequoia
Average Sequoia full coverage by study
| Study | Full coverage | Sample driver |
| Study B (Oct 2026) | $3,194 a year | 40-year-old, $500 deductible, 2025 model |
| Study C (Mar 2026) | $3,194 a year | 40-year-old male, 100/300/100 |
| Study A | $2,917 a year | 30-year-old male, 2025 model |
| Study D | $2,154 a year | 40-year-old, good credit, new model |
Within Study A, the sample annual rate for Progressive and Allstate differs by $3,149 for the same 2025 Sequoia profile. The same premium every year for five consecutive years is an illustration only, not a justified five-year forecast. Claims, location, driver age, policy terms and insurer filings can all change during that period.
Sequoia insurance by trim
The studies used here do not provide reproducible premiums for each Sequoia trim. Purchase price is one factor that may influence collision and comprehensive costs, but trim, risk, repair costs, driver and local underwriting also matter. We therefore list 2026 MSRP values as vehicle prices, not trim-specific insurance estimates.
2026 Toyota Sequoia prices by trim
| Trim | Price with destination | Difference from SR5 |
| SR5 (rear-wheel drive) | $66,120 | — |
| Limited (rear-wheel drive) | $71,890 | $5,770 |
| Platinum | $82,130 | $16,010 |
| TRD Pro | $82,860 | $16,740 |
| 1794 Edition | $82,945 | $16,825 |
| Capstone | $86,530 | $20,410 |
Prices as of July 2025, including a $2,095 destination fee, from the vehicle sources listed in Sources. Differences are due to our subtraction.
SR5
The 2026 SR5 has the lowest listed MSRP of these trims, but no study establishes it as the cheapest to insure. IIHS rates the 2026 Sequoia’s standard headlights Poor; selected upgraded LED headlight configurations receive Good. Verify the actual equipment and quote the VIN.
Limited
The Limited adds about $5,800 to the SR5’s price. For 2026, it gets new leather-trimmed seats, and its upgraded LED headlights, optional on this trim, rate Good from IIHS.
Platinum, TRD Pro, and 1794 Edition
The 2026 Platinum, TRD Pro and 1794 Edition have relatively close listed starting prices, but this does not establish identical insurance premiums. The off-road components of the TRD Pro and equipment differences among trims may affect repair costs; compare VIN-specific quotes.
Capstone
The 2026 Capstone has the highest MSRP in the listed range, but that alone does not establish it as the highest-premium trim. The insurer must rate its actual VIN, driver and coverage; differences in theft, parts and claim history can matter.
Two- or four-wheel drive
Four-wheel drive adds $3,000 to the SR5 and Limited. No study separates insurance prices by drivetrain, but the higher value can raise collision and comprehensive costs slightly, so get quotes on the exact configuration you plan to buy.
Older trims
Older Sequoias came in SR5, Limited, and Platinum trims, plus TRD Sport, TRD Pro, and Nightshade Special Edition models late in the V8 generation. These cost less to insure than the hybrids, as the model-year section below shows.
PRO TIP #5
Use the VIN to obtain coverage terms and a premium for the correct trim. A wrong trim can distort a quote or cause inaccurate application information, but actual total-loss payments depend on the policy and vehicle valuation, not simply the list price.
2026 changes and the 2027 Sequoia
For 2026, the Sequoia gained power-folding third-row seats as standard, new leather-trimmed seats on the Limited and Capstone, and a new Wave Maker color for the TRD Pro, while the SR5’s price rose $1,600.
Toyota unveiled updates to the 2027 Sequoia in July 2026 and published a fuller U.S. specification and pricing announcement on November 4, 2026. It has redesigned front styling, a standard 14-inch touchscreen, a built-in Drive Recorder dash camera, Toyota Safety Sense 4.0 and expanded trailer-assistance features. An SR5 Trailhunter package adds upgraded suspension, off-road tires, skid protection and a locking rear differential; it is a package, not a standalone trim. Toyota announced a starting U.S. MSRP of $69,900 before destination. No comparable 2027 Sequoia insurer-by-insurer premium study was established by these sources. The insurance information on this page therefore remains based mainly on earlier model years.
2027 Toyota Sequoia U.S. starting MSRPs by trim (November 2026)
| Trim | MSRP before destination | With $2,195 destination |
| SR5 | $69,900 | $72,095 |
| Limited | $75,500 | $77,695 |
| Platinum | $83,400 | $85,595 |
| 1794 Edition | $84,400 | $86,595 |
| TRD Pro | $85,925 | $88,120 |
| Capstone | $87,900 | $90,095 |
Manufacturer suggested retail prices, excluding taxes, fees and optional equipment. The SR5 Trailhunter package adds $3,500 before destination. Pricing confirmed in Toyota’s November 4, 2026 announcement and the contemporaneous Kelley Blue Book trim table. These are not insurance premiums.
Safety ratings and recalls
IIHS assigns the 2026 Sequoia Good ratings in the original small-overlap front and updated side tests and Marginal in the updated moderate-overlap frontal test. The standard headlight configuration is Poor, while specified upgraded LEDs rate Good. The front crash-prevention rating varies with the exact test category and system; these findings do not amount to one overall safety score. See the IIHS model-specific record for the trim/equipment applicability.
Recent recalls
- October 2025 — NHTSA 25V657: Toyota recalled certain 2023–2025 Sequoia Hybrid SUVs, along with certain Tundra and Tundra Hybrid trucks, because the rearview image may not appear when reversing. The reported 393,838 potentially affected vehicles is the combined campaign total, not a Sequoia-only count. Toyota prescribed a dealer multimedia software update at no charge. Use the VIN to determine whether a particular Sequoia is included.
- October 2024: Toyota issued a recall for certain 2024 Tundra and Sequoia vehicles over possible tire sidewall damage during production. The published campaign total covers both models. Affected owners should confirm the VIN and dealer remedy rather than assuming every 2024 Sequoia has the defect.
A recall notice is not by itself a personal insurance-rate quote or proof of a premium increase. Check the VIN at NHTSA’s official recall lookup and arrange any outstanding repair with Toyota.
PRO TIP #6
If you are choosing between an SR5 and a higher trim, factor in the headlights. The upgraded LED lights rate Good from IIHS, and better visibility at night may help you avoid a claim.
Sequoia insurance by model year
Study A covers Sequoias from 2011 to 2025, and the step up at the 2023 redesign is easy to see. Averages climb slowly from $1,665 a year for a 2011 to $2,239 for a 2022, then jump to $2,722 for the first hybrid year and $2,917 for a 2025.
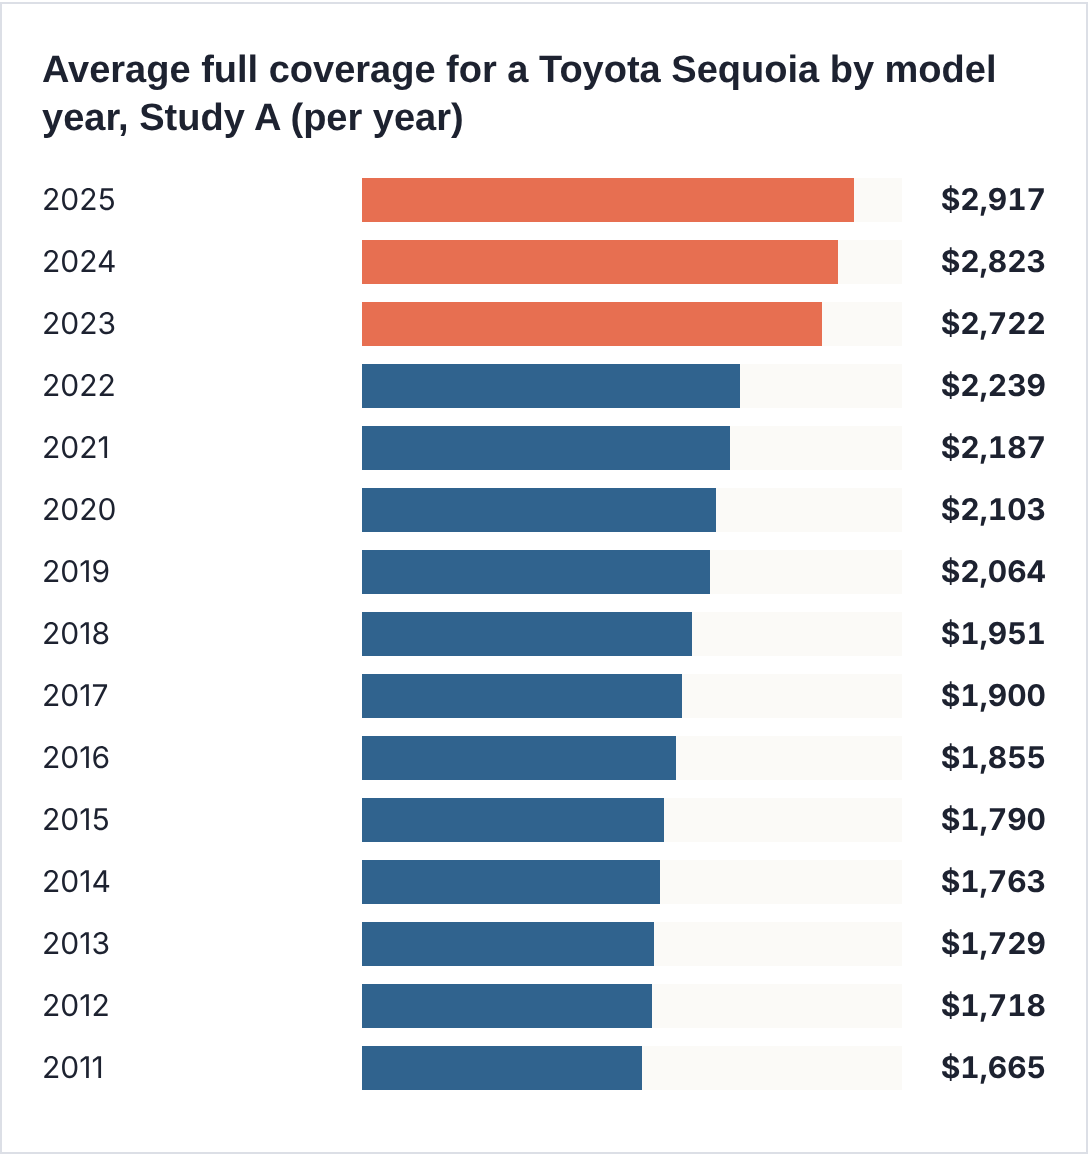
30-year-old male, full coverage. Source: Study A, Toyota Sequoia insurance.
Sequoia insurance by model year, Study B (per year)
| Model year | Average (headline table) | Average (year section) | Cheapest company: Travelers |
| 2025 | $3,194 | $2,907 | $1,851 |
| 2024 | $3,091 | $2,843 | $1,852 |
| 2023 | $3,009 | $2,788 | $1,808 |
| 2022 | $2,592 | $2,493 | $1,822 |
| 2021 | $2,497 | $2,435 | $1,745 |
| 2020 | — | $2,371 | $1,707 |
| 2019 | — | $2,291 | $1,609 |
| 2018 | — | $2,188 | $1,577 |
40-year-old driver, 100/300/100 with a $500 deductible, October 2026. Study B lists two different averages for some years on its page without explaining the difference; we show both.
Travelers’ prices barely move across model years in Study B, from $1,577 for a 2018 to $1,852 for a 2024, so it is a good first quote for any Sequoia, old or new.
Older Sequoia full coverage by company, Study A (per year)
| Insurer | 2021 | 2016 | 2011 |
| American Family | $1,628 | $1,383 | $1,280 |
| Progressive | $1,707 | $1,405 | $1,384 |
| Erie | $1,771 | $1,547 | $1,250 |
| Nationwide | $1,772 | $1,648 | $1,676 |
| USAA* | $1,901 | $1,460 | $1,224 |
| State Farm | $2,156 | $1,772 | $1,438 |
| GEICO | $2,203 | $1,891 | $1,612 |
| Allstate | $3,076 | $2,729 | $2,591 |
| Farmers | $3,158 | $2,512 | $2,066 |
| Average | $2,187 | $1,855 | $1,665 |
30-year-old male, full coverage. *USAA sells only to military families. Source: Study A.
Cheapest company by model year in Study A
Study A’s leader changes with the generation. Progressive is cheapest for the 2023 to 2025 hybrids, American Family for every V8 model from 2014 to 2022, and USAA for the 2011 to 2013 models.
PRO TIP #7
Shopping for a used Sequoia? A 2018 to 2022 V8 costs about $480 to $970 a year less to insure than a 2023 to 2025 hybrid in Study A. Get quotes from American Family and Travelers for the older model.
Sequoia insurance vs. other full-size SUVs
The Sequoia is one of the costlier full-size SUVs to insure. In Study C, it costs more than a Chevrolet Tahoe, GMC Yukon, Chevrolet Suburban, Nissan Armada, or Ford Expedition, but less than a Jeep Wagoneer or Grand Wagoneer.
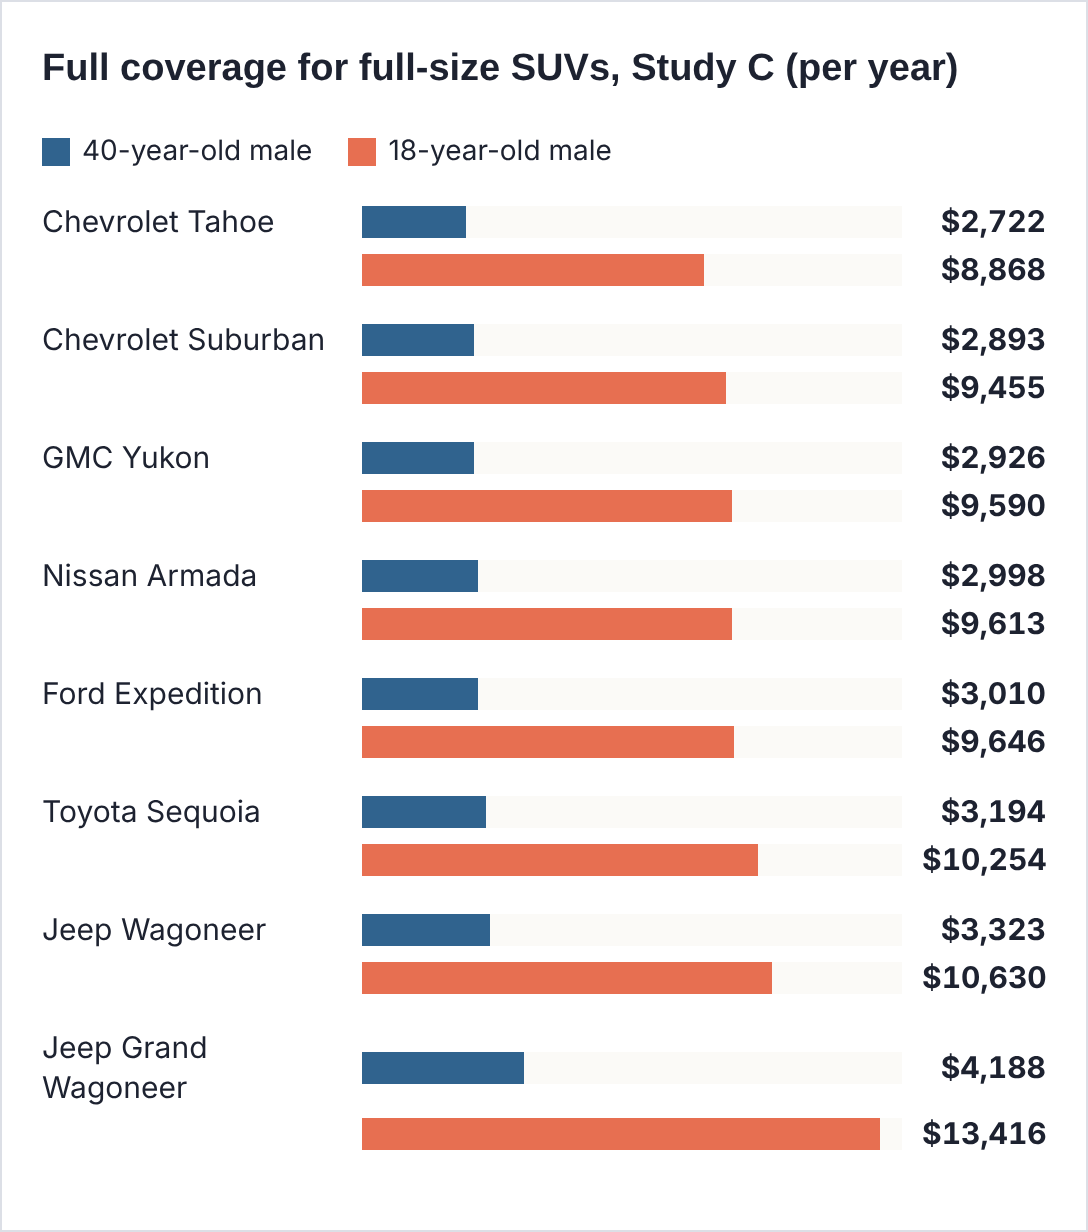
100/300/100 full coverage. Source: Study C, cheap SUV insurance rates, September 16, 2026.
Cheapest company for each full-size SUV, Study C (per year)
| SUV | Average, 40-year-old | Cheapest: Travelers |
| Chevrolet Tahoe | $2,722 | $1,810 |
| Toyota Sequoia | $3,194 | $1,851 |
| GMC Yukon | $2,926 | $1,864 |
| Chevrolet Suburban | $2,893 | $1,915 |
| Ford Expedition | $3,010 | $2,185 |
| Jeep Wagoneer | $3,323 | $2,244 |
| Nissan Armada | $2,998 | $2,403 |
| Jeep Grand Wagoneer | $4,188 | $2,546 |
Source: Study C, cheap SUV insurance rates, September 16, 2026. The Travelers figures come from the study’s company table, which does not state an age.
Shopping with Travelers changes the picture. The Sequoia’s $1,851 is the second-lowest price among these SUVs at that company, just $41 more than a Tahoe and $552 less than a Nissan Armada. On average, though, a Tahoe costs $472 a year less to insure.
Sequoia insurance by state
Study D’s figures for a 40-year-old with good credit range from $997 a year in Hawaii to $3,106 in Connecticut among the 15 states it shows.
Sequoia insurance in 15 states, Study D (per year)
| State | Good driver | Recent at-fault accident | Poor credit |
| Alabama | $2,282 | $3,314 | $4,219 |
| Alaska | $1,888 | $2,617 | $2,543 |
| Arizona | $2,134 | $3,085 | $4,545 |
| Arkansas | $2,340 | $3,676 | $4,047 |
| California | $2,605 | $4,606 | $2,605 |
| Colorado | $2,431 | $3,402 | $4,316 |
| Connecticut | $3,106 | $4,817 | $6,114 |
| Delaware | $2,571 | $3,426 | $4,401 |
| Florida | $3,061 | $4,235 | $5,519 |
| Georgia | $2,496 | $3,732 | $3,763 |
| Hawaii | $997 | $1,353 | $997 |
| Idaho | $1,732 | $2,296 | $2,791 |
| Illinois | $1,813 | $2,740 | $3,124 |
| Indiana | $1,863 | $2,847 | $3,195 |
| Iowa | $1,475 | $2,023 | $2,379 |
40-year-old driver, full coverage, good credit unless noted. Source: Study D, Toyota Sequoia insurance.
Full coverage for a 2025 Sequoia in Florida by company, Study B (per year)
| Insurer | Per year |
| Nationwide | $2,166 |
| Travelers | $2,336 |
| State Farm | $2,573 |
| UAIC | $2,742 |
| GEICO | $3,531 |
| Mercury | $3,635 |
| Progressive | $4,384 |
| Allstate | $4,875 |
| AIG | $6,681 |
In Florida, Nationwide leads at $2,166 a year, while Progressive, the cheapest company in Study A, costs $4,384. An at-fault accident adds the most in California in Study D, from $2,605 to $4,606, and poor credit nearly doubles the price in Connecticut.
Hawaii stands out as the cheapest state in Study D’s sample at $997 a year, and Iowa is next at $1,475. Florida and Connecticut both top $3,000 a year for a clean driver with good credit.
PRO TIP #8
Moving with your Sequoia? Get quotes at the new address before you register it there, because the cheapest company in one state may be among the most expensive in the next.
How age, accidents, and credit change Sequoia rates
Study D shows how the same new Sequoia is priced for different drivers. A 40-year-old with a clean record and good credit pays $2,154 a year. One recent at-fault accident raises that to $3,163, and poor credit raises it to $3,700, about 72% more.
Sequoia insurance by age and driver profile, Study D (per year)
| Age | Good driver and credit | Recent at-fault accident | Poor credit |
| 18 | $6,799 | $9,983 | $11,679 |
| 25 | $3,069 | $4,507 | $5,273 |
| 30 | $2,391 | $3,511 | $4,107 |
| 40 | $2,154 | $3,163 | $3,700 |
| 55 | $1,922 | $2,823 | $3,302 |
Full coverage on a new Sequoia, about 13,000 miles a year, single-car policy. Source: Study D, Toyota Sequoia insurance.
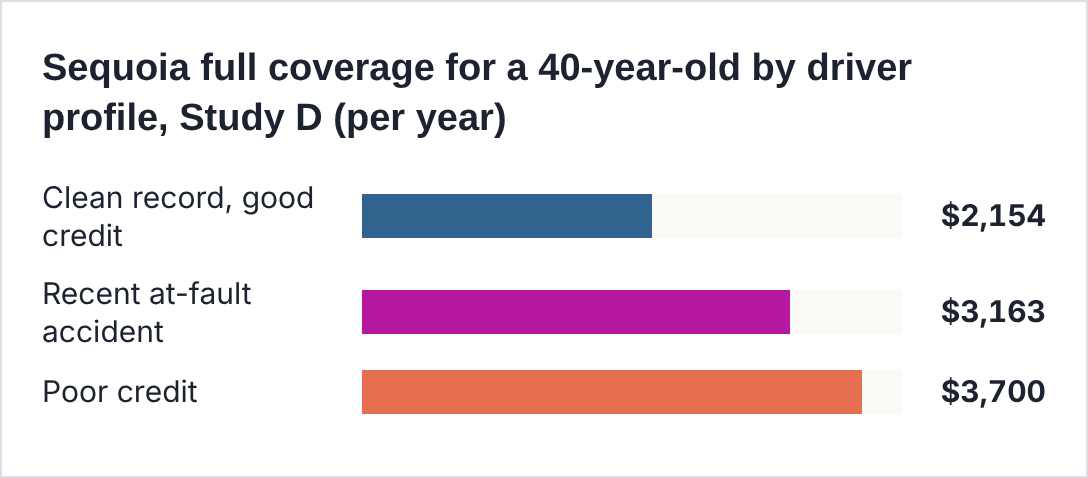
Source: Study D, Toyota Sequoia insurance.
Age brings the biggest change. An 18-year-old pays $6,799 a year in Study D, more than three times the 40-year-old’s price, and the cost falls to $3,069 by 25 and $1,922 by 55. Poor credit costs a 40-year-old $1,546 a year, more than an at-fault accident’s $1,009, in states that allow credit to be used.
Recovering after a claim
- Shop at your next renewal, because insurers weigh accidents differently.
- Ask about accident forgiveness before you need it.
- Take a defensive driving course if your state allows a discount or point reduction.
- Join a usage-based program to earn a safe-driving discount.
Coverage choices for a full-size family SUV
A Sequoia often carries a full load of family and gear, and it can tow a large camper or boat, so a few coverages deserve extra attention:
- Higher liability limits. With up to eight seats, one crash can injure several people. Limits of 100/300/100 or higher protect your savings far better than a state minimum.
- Uninsured and underinsured motorist coverage. It pays your family’s injuries when the at-fault driver has too little insurance or none.
- Rental reimbursement. Choose a daily limit high enough to rent a large SUV or minivan.
- Gap insurance. On a loan or lease with little money down, it covers the difference between your balance and the SUV’s value if it is totaled.
- Trailer coverage. Your auto liability usually extends to a trailer you tow, but damage to the trailer itself typically needs its own policy.
PRO TIP #9
Ask whether your policy replaces child car seats after a crash. Federal guidance calls for replacing a car seat after a moderate or severe crash, and coverage for it varies by insurer.
Towing with a Sequoia
If you pull a camper, boat, or utility trailer with your Sequoia, know where your coverage stops. Progressive explains that your auto liability coverage applies to damage you cause while towing, but it typically does not cover damage to the trailer itself or what is inside it. If you tow something valuable, insure it separately, and tell your auto insurer if you tow regularly.
Towing also adds weight and stopping distance, so a crash while towing can cause more damage. That is one more reason to carry liability limits well above your state minimum on a Sequoia.
Five mistakes that raise Sequoia premiums
- Renewing without shopping. For the same 2025 Sequoia, Study A’s prices run from $1,741 to $4,890 a year.
- Quoting the wrong generation or trim. A 2023 hybrid costs more to insure than a 2022 V8, and a Capstone is worth about $20,000 more than an SR5.
- Letting your credit slide. In Study D, poor credit adds $1,546 a year for a 40-year-old in most states.
- Keeping a low rental limit. A small rental car will not carry a family of eight while your Sequoia is in the shop.
- Forgetting the trailer. Your auto policy may not pay for damage to a camper or boat trailer you tow.
10 discounts for Sequoia owners
These discounts come from each insurer’s own pages. Availability and amounts vary by state, and percentages are maximums or averages, not guarantees.
1. Home and auto bundle
Some insurers advertise average or maximum multi-policy savings, but those figures are from different customer populations and discount bases, not guaranteed Sequoia savings. Ask for an actual combined home-and-auto quote, and review additional cost-cutting strategies before changing coverage.
2. Multiple vehicles
GEICO offers up to 25% off for more than one vehicle, and Progressive says its multi-car customers save 12% on average.
3. Safe-driving programs
State Farm’s Drive Safe & Save offers up to 30%, Liberty Mutual’s RightTrack up to 30%, and USAA’s SafePilot 10% for joining and up to 30% at renewal. Nationwide’s SmartRide offers 10%, and Progressive says Snapshot users save $328 a year on average.
4. Hybrid vehicle
Every 2023 and newer Sequoia is a hybrid, and The Hartford’s AARP program lists a discount for hybrid and electric vehicles. It does not publish the amount, so ask.
5. Good student
State Farm offers up to 25% for students with good grades, GEICO up to 15%, and Progressive about 5%.
6. Clean record
GEICO offers up to 22% for drivers with five years free of accidents.
7. Newer vehicle
Travelers offers a discount on cars less than three years old in most states, though not in California.
8. Safety equipment
State Farm offers up to 40% off certain medical coverages for factory airbags, and GEICO lists 5% for anti-lock brakes.
9. Online quote and paperless signing
Progressive offers about 7% for quoting online and about 10% for signing documents online, and The Hartford lists 8% for an online quote.
10. Military and mature drivers
GEICO offers up to 15% for military members, and The Hartford takes 10% off for AARP members. The senior and military sections below have more.
PRO TIP #10
Families with several drivers and vehicles often qualify for a bundle, a multi-vehicle discount, and a good student discount at once. Ask each company to list every discount on its quote.
Sequoia insurance for teen drivers
A young driver may face much higher Sequoia insurance premiums than an experienced driver. Study C estimates $10,254 per year for its 18-year-old male Sequoia sample; Study D estimates $6,799 for a different 18-year-old clean-record profile. Neither amount can be compared directly with the nationwide cost of adding a teenager to a family policy, where the vehicle and household are not necessarily Sequoia-specific.
The ages 16, 17 and 19 below use national, non-Sequoia-specific family insurance statistics as context. They do not identify the lowest-priced Sequoia insurer at those ages. The 18-year-old values above are the only vehicle-specific examples given in this section.
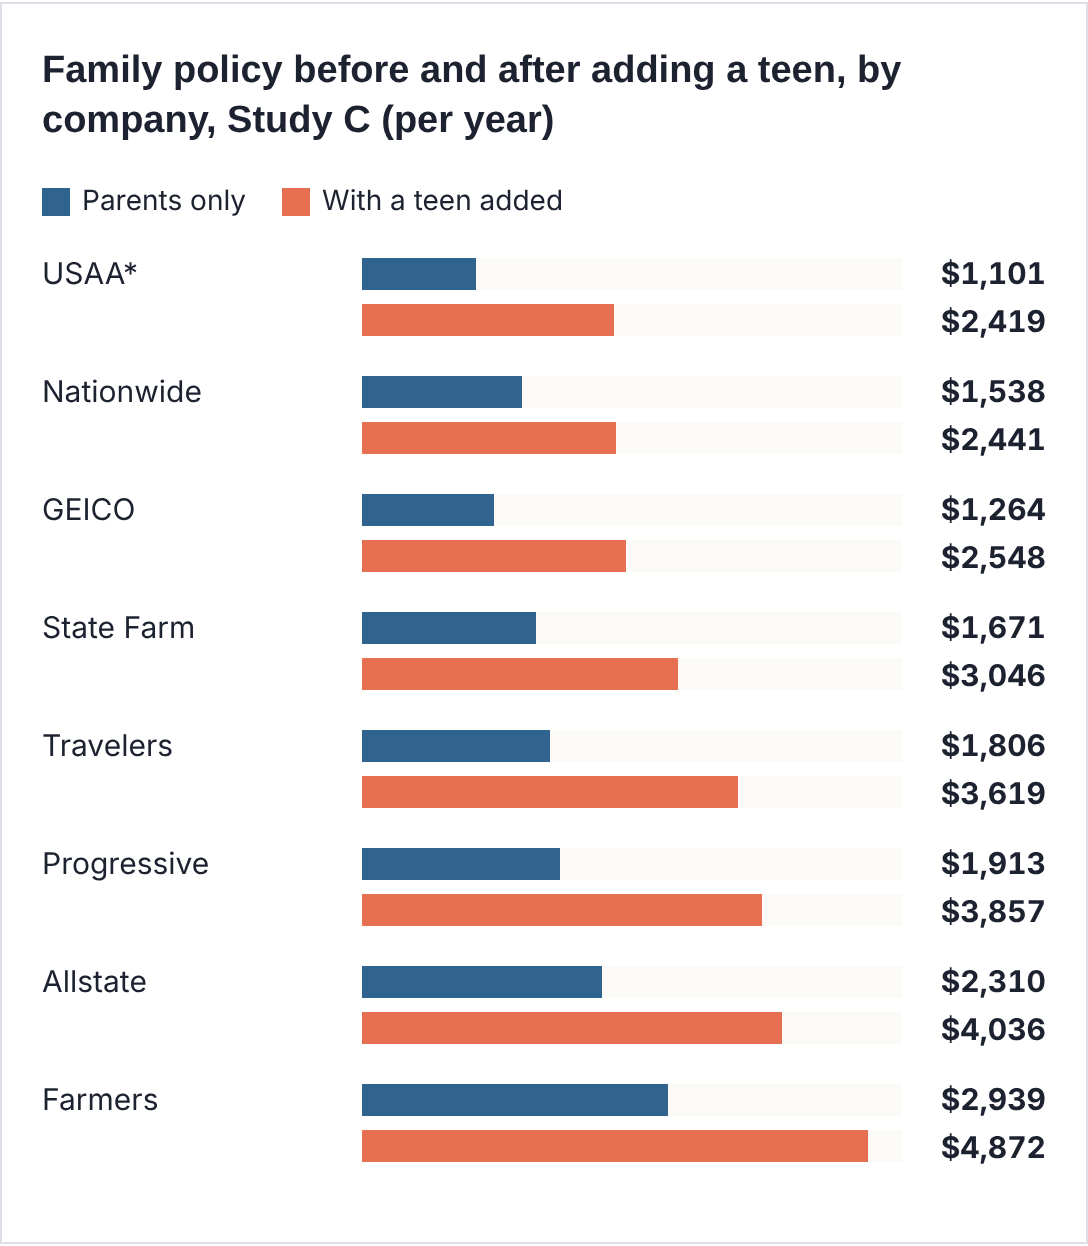
Full-coverage family premium; national data, no specific test vehicle. *USAA sells only to military families. Source: Study C.
Nationwide adds the least for a teen in Study C, $903 a year, and its family total of $2,441 is nearly tied with USAA’s $2,419.
Age 16: family-policy benchmark (not Sequoia-specific)
Study C’s general national sample estimates roughly $4,050 a year in added family-policy cost for a 16-year-old, without identifying a Sequoia as the insured vehicle. The reported GEICO separate-policy estimate comes from a different national driver study, not a Sequoia quote. Check the actual household policy and disclose every eligible driver truthfully.
Age 17: family-policy benchmark (not Sequoia-specific)
At age 17, the national family-policy benchmark cited in Study C is approximately $3,740 annually; the separate-policy GEICO benchmark belongs to another study. Those amounts do not establish the cheapest insurer for a 17-year-old Sequoia driver.
Cheapest Toyota Sequoia insurance for an 18-year-old
For an 18-year-old driving a Sequoia under Study C’s stated assumptions, the published average is $10,254 annually. A generic national study of adding an 18-year-old to a family policy yields an entirely different estimate; no specific Sequoia premium can be inferred from that household benchmark.
Age 19: family-policy benchmark (not Sequoia-specific)
The cited $3,105 annual age-19 amount is a national estimate for adding a teenager to an unspecified household policy. Another study’s separate-policy Travelers rate uses a different driver and unspecified vehicle. Neither is a 19-year-old Sequoia quote.
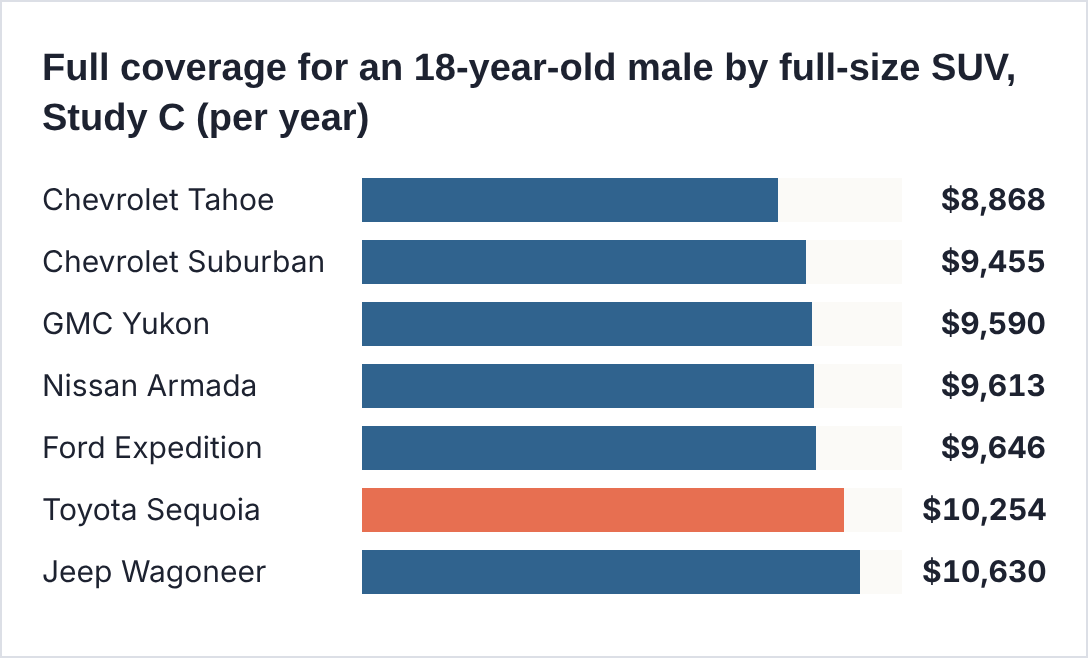
100/300/100 full coverage. Source: Study C, cheap SUV insurance rates, September 16, 2026.
Among full-size SUVs in Study C, the Sequoia costs $1,386 a year more than a Chevrolet Tahoe for an 18-year-old, and $376 less than a Jeep Wagoneer.
Keeping a teen’s Sequoia premium down
- Ask whether a compliant family policy is available and more affordable than a separate policy; eligibility and household-driver assignment vary. Disclose who actually drives the Sequoia and how frequently. Do not assign a young driver to a different car merely to obtain a lower premium if that would misstate their use.
- Disclose every household driver and their actual access and use of each vehicle; let the insurer apply its permitted driver-assignment rules. An artificially favorable assignment can create underwriting or claim disputes.
- Claim good student discounts of up to 25% at State Farm or up to 15% at GEICO.
- Enroll in a safe-driving app program, and requote at every birthday from 16 to 19.
PRO TIP #11
A big SUV is harder for a new driver to park and maneuver. Practice in an empty lot first, and remember that in Study D, one at-fault accident adds about $3,200 a year to an 18-year-old’s Sequoia premium.
Sequoia insurance for senior drivers
For a Sequoia-specific illustration, Study D lists its 55-year-old sample at $1,922 annually. The 65-, 70- and 75-year-old figures quoted from Study C are national all-vehicle averages, not Sequoia quotes, and should not be presented as expected Sequoia costs.
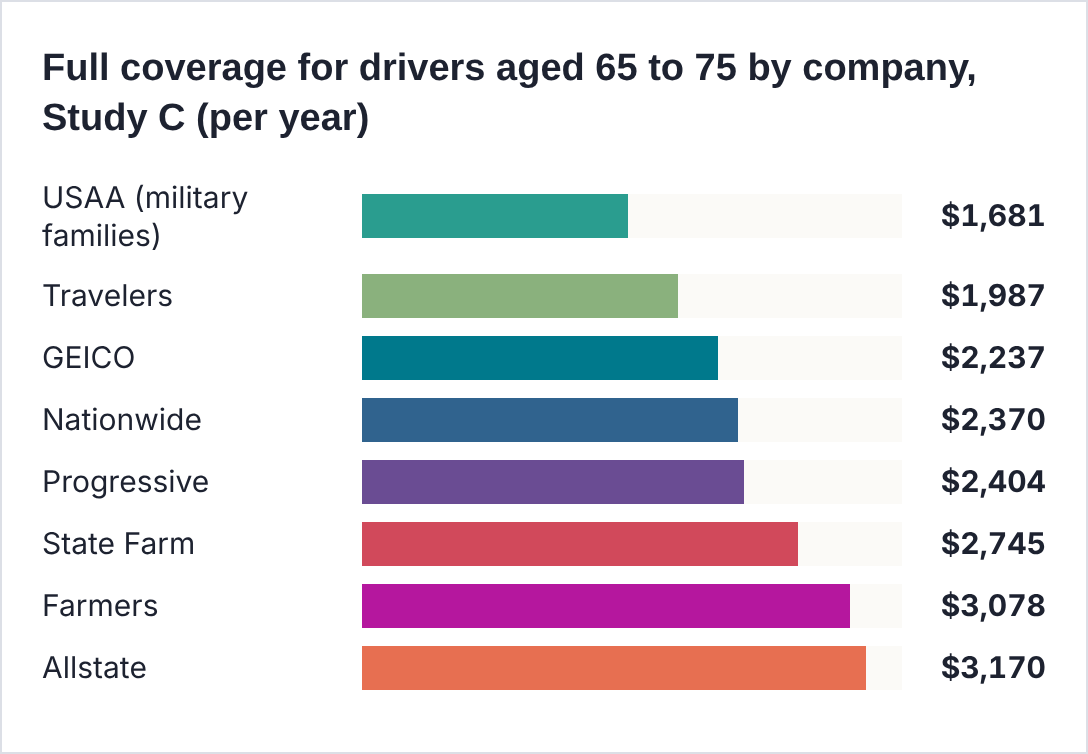
100/300/100 with a $500 deductible; no test vehicle named. Source: Study C, car insurance for seniors, April 16, 2026.
Travelers led certain Sequoia-specific examples in Studies B and C. Study C’s separate published senior-rate comparison did not specify a Sequoia, so its $1,987 rate does not establish Travelers as the cheapest Sequoia insurer for seniors.
Savings tips for older Sequoia owners
- Take an approved mature driver course. AARP says 33 states and Washington, D.C., require insurers to give a discount for one, and Kiplinger reports savings of up to 10%.
- Get a quote from The Hartford’s AARP program, which lists 10% off for AARP members, 5% for a defensive driving course, up to 15% through its TrueLane app, and a hybrid and electric vehicle discount.
- If you tow a camper on trips, review your liability limits and insure the trailer separately.
- Report your lower mileage after retirement.
PRO TIP #12
Retirees who drive the grandchildren often should keep uninsured motorist coverage and high liability limits. A full Sequoia carries a lot of people to protect.
Pay-per-mile for a Sequoia that stays home
If your Sequoia sees little annual mileage, a mileage-based policy may be worth comparing. However, a base monthly charge plus per-mile fees can make a long-trip SUV expensive to insure under some programs. Review usage-based and pay-per-mile coverage and obtain actual quotes; program availability and mile-counting limits vary by insurer and state.
Lemonade, which owns Metromile, sells car insurance in nine states and gives an example of a $29 base rate plus 6 cents a mile. Long road trips add up quickly, so compare a per-mile plan with a standard low-mileage discount.
Sequoia insurance for military families
USAA is a strong choice for military families with a Sequoia. It was the second-cheapest company in both Study A and Study B for a 2025 model, at $2,043 and $2,139 a year, and it earned the highest J.D. Power scores in every region in 2026.
Full coverage for military members vs. civilians, Study C (per year)
| Insurer | Military | Civilian | Military savings |
| USAA | $1,465 | $1,572 | $107 |
| Travelers | $1,818 | $2,103 | $285 |
| Auto-Owners | $1,908 | $2,051 | $143 |
| GEICO | $1,951 | $2,148 | $197 |
| Nationwide | $2,210 | $2,463 | $253 |
| Progressive | $2,382 | $2,675 | $293 |
| State Farm | $2,575 | $2,874 | $299 |
| Farmers | $2,676 | $3,085 | $409 |
| Allstate | $2,698 | $3,205 | $507 |
Full coverage; no test vehicle named. Savings are our subtraction. Source: Study C, best car insurance for military members, August 13, 2026.
Study C’s military-versus-civilian table uses national samples without a named test vehicle. The listed differences do not establish a military Sequoia discount from each company; an eligible driver should request the exact insurer discount and policy terms.
Military discounts to ask about
- USAA advertises up to 60% off for a vehicle in storage, except in North Carolina and Virginia, and up to 15% off comprehensive coverage for a vehicle garaged on a base.
- GEICO offers up to 15% for active-duty, retired, Guard, and Reserve members and up to 25% when you are deployed overseas.
- Armed Forces Insurance can arrange auto coverage for military families through partner insurers.
PRO TIP #13
Getting orders for a new base? Update your Sequoia’s garaging address before the move and request new quotes there, since prices and the cheapest company can change from state to state.
Sequoia insurance, explained in five panels
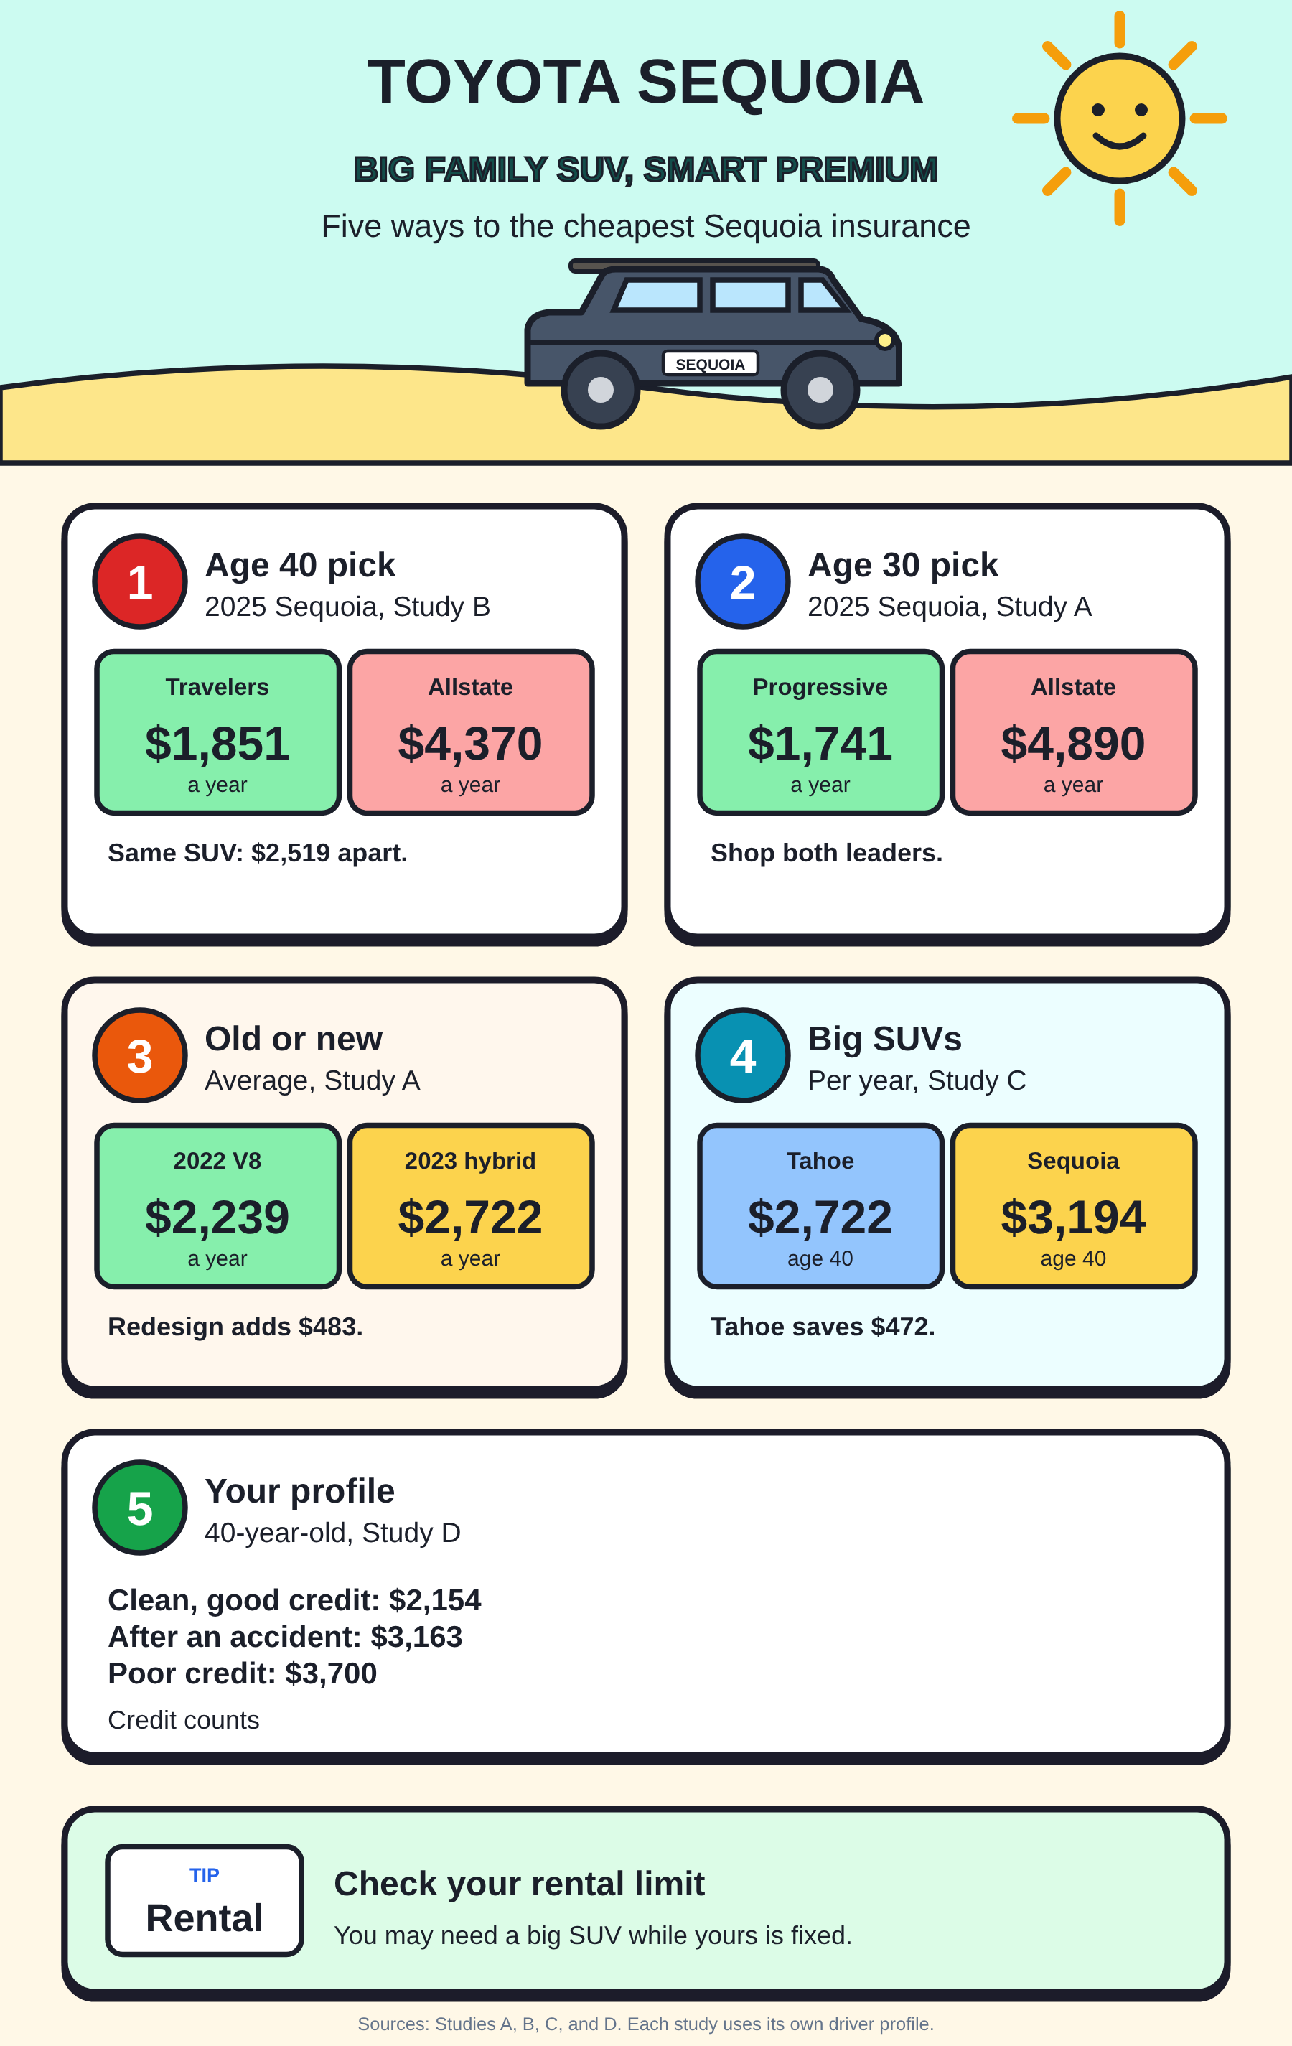
An original cartoon summary of five ways to get the cheapest Sequoia insurance.
Questions and answers on the cheapest Toyota Sequoia insurance
Who has the cheapest Sequoia insurance?
Travelers had the lowest 2025 price for a 40-year-old in Study B, $1,851 a year, and Study C also names it cheapest. Progressive led Study A at $1,741 for a 30-year-old, and USAA was second in both company studies.
How much does Sequoia insurance cost per month?
Full coverage averages about $180 to $266 a month across the studies in this guide. Liability-only coverage is about $96 a month in Study B.
Why is the Sequoia expensive to insure?
The Sequoia is a large and relatively costly-to-repair hybrid SUV, with substantial insured vehicle value. Published 2026 MSRPs in this guide range from about $66,000 to $87,000 with destination; the 2027 base MSRP is $69,900 before destination. These features can affect physical-damage premiums, but the studies do not isolate the price impact of hybrid parts. The gap between liability-only and full coverage also includes different liability limits and policy terms.
Is a 2022 Sequoia cheaper to insure than a 2023?
Yes. The 2022 V8 averages $2,239 a year in Study A against $2,722 for the 2023 hybrid, and $2,592 against $3,009 in Study B.
Is the Sequoia more expensive to insure than a Chevrolet Tahoe?
On average, yes, by $472 a year in Study C. With Travelers, though, the two are only $41 apart.
Which Sequoia trim is cheapest to insure?
No reviewed insurer study publishes trim-level Sequoia premiums. SR5 has the lowest 2026 MSRP in the referenced list, but the lower list price does not guarantee the lowest insurance premium. Quote the exact trim and VIN.
Is the Sequoia an IIHS Top Safety Pick?
No. It scored Marginal in the updated moderate overlap test and for vehicle-to-vehicle front crash prevention, and its standard headlights rate Poor.
Was my Sequoia recalled?
Some 2023 to 2025 Sequoias need a backup camera software update, and some 2024 models needed a tire inspection. Check your VIN at nhtsa.gov.
Does credit affect Sequoia insurance?
In most states, yes. In Study D, poor credit raises a 40-year-old’s price from $2,154 to $3,700 a year. California and Hawaii do not allow credit to raise rates.
How much is Sequoia insurance for an 18-year-old?
Study C puts an 18-year-old male at $10,254 a year as the main driver, and Study D puts an 18-year-old with good credit at $6,799. Adding a teen to a parent’s policy usually costs much less.
Which state has the cheapest Sequoia insurance?
Among the 15 states in Study D, Hawaii is cheapest at $997 a year for a clean driver with good credit.
Does towing a trailer change my Sequoia insurance?
Your auto liability coverage usually applies while you tow, but damage to the trailer itself typically needs its own policy. Tell your insurer if you tow often.
Is the Sequoia cheaper to insure than the Land Cruiser?
No, but it is close. Study B puts the Sequoia at $3,194 a year and the Land Cruiser at $3,177 for a 40-year-old, a $17 difference.
Who has the cheapest Sequoia insurance in Florida?
Nationwide had the lowest price in Study B’s Florida sample for a 2025 Sequoia, at $2,166 a year, followed by Travelers at $2,336 and State Farm at $2,573.
Is USAA cheaper than Progressive for a Sequoia?
It depends on the study. Progressive was cheaper in Study A, at $1,741 a year against $2,043 for USAA, but USAA was cheaper in Study B, at $2,139 against $2,746. Military families should get both quotes.
Are 2027 Sequoia insurance rates available?
Toyota first previewed the 2027 Sequoia in July 2026 and released U.S. MSRP details in November 2026, starting at $69,900 before destination. The rate studies summarized here do not supply comparable 2027 Sequoia premiums. Use a VIN-specific quote for a 2027 vehicle.
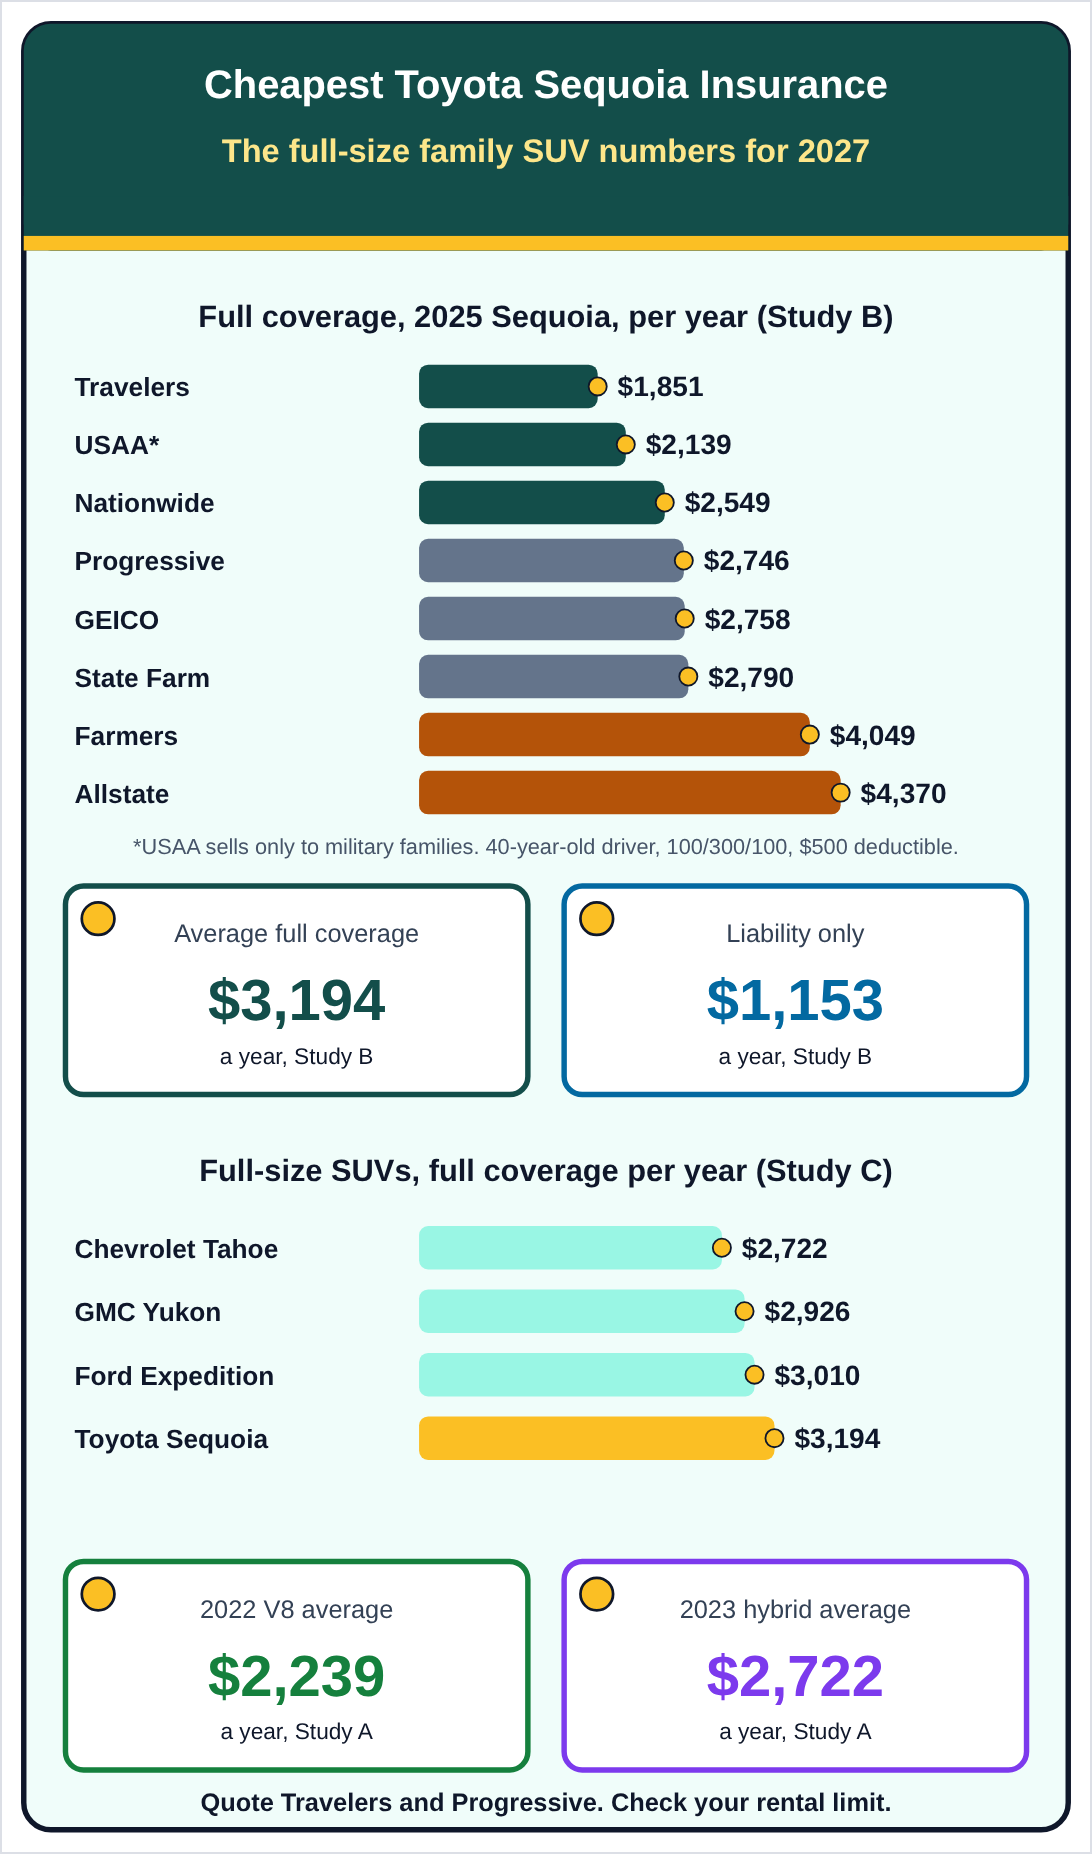
Sequoia insurance in one picture.
The final word on the cheapest Toyota Sequoia insurance
The Sequoia is the most expensive Toyota SUV to insure in Study B, and the 2023 hybrid redesign raised prices by about $400 to $500 a year on average. Even so, it costs less than a Jeep Wagoneer, and with Travelers it is nearly as cheap to insure as a Chevrolet Tahoe.
For this model, quoted prices vary materially by insurer, location and driver profile. Travelers led Study B for its 40-year-old sample and Progressive led Study A for its 30-year-old sample; a different household may get the opposite outcome. Obtain same-coverage quotes, check the exact SUV’s configuration and inspect outstanding recalls. You can also review ways to compare prices before renewal, noting that no future rate reduction is guaranteed.
Sources
- Study A: The Zebra, Toyota Sequoia insurance.
- Study B: Insurance.com, Toyota Sequoia car insurance and Toyota insurance (October 26, 2026), and teen car insurance costs (August 13, 2026).
- Study C: CarInsurance.com, Toyota car insurance cost (March 23, 2026); cheap SUV insurance rates (September 16, 2026); cost of adding a teen driver (August 4, 2026); car insurance for seniors (April 16, 2026); best car insurance for military members (August 13, 2026); top financially rated insurers (December 16, 2025); and insurers ranked by NAIC complaint data (August 13, 2026).
- Study D: CarEdge, Toyota Sequoia insurance.
- Service ratings: J.D. Power 2026 U.S. Auto Insurance Study coverage (June 9, 2026); J.D. Power 2026 regional scores; Amica, J.D. Power 2026 results; and J.D. Power 2026 Auto Claims Satisfaction Study coverage (October 27, 2026).
- Insurer pages: Progressive discounts; Progressive, utility trailer insurance; GEICO discounts; GEICO military discounts; State Farm discounts; Nationwide discounts; Nationwide SmartMiles; Lemonade, pay-per-mile car insurance (June 25, 2026); Liberty Mutual RightTrack; Travelers discounts; Farmers discounts; USAA discounts; The Hartford AARP discounts; Armed Forces Insurance, auto; and Toyota, Toyota Auto Insurance.
- Vehicle and safety data: Cars.com, what’s new on the 2026 Sequoia (July 22, 2025); PickupTruckTalk, 2027 Sequoia changes (July 23, 2026); Toyota, 2025 U.S. sales results (January 5, 2026); Cars.com, how safe is the 2026 Sequoia (June 12, 2026); Kelley Blue Book, backup camera recall (October 20, 2025); and Kelley Blue Book, tire damage recall (October 25, 2024).
- Other sources: AARP, auto insurance discounts; and Kiplinger, ways seniors save on car insurance (September 3, 2026).
- Manufacturer and primary verification: Toyota U.S. 2027 Sequoia, Nov. 4, 2026; Kelley Blue Book 2027 MSRP by trim, Nov. 4, 2026; IIHS 2026 Sequoia; NHTSA recall 25V657; AM Best Erie, Sep. 5, 2025; AM Best State Farm, Nov. 14, 2025.
Disclaimer
This article summarizes published insurance rate studies, satisfaction surveys, financial strength ratings, crash-test results, and recall notices for the Toyota Sequoia. It is general information only and is not insurance, legal, or financial advice. All prices are averages, estimates, or sample quotes for the driver profile each source chose.
Your own premium depends on your location, age, driving and claims history, credit where the law allows it, household drivers, mileage, whether you tow, your Sequoia’s model year, trim, and drivetrain, and the limits and deductible you select. Rental, trailer, and car seat coverage vary by policy, so confirm the details with your insurer.
We are not affiliated with Toyota Motor North America, Inc., J.D. Power, AM Best, IIHS, or any insurer named here, including Travelers, Progressive, USAA, Nationwide, Erie, American Family, GEICO, State Farm, UAIC, Mercury, Farmers, Allstate, AIG, Amica, Liberty Mutual, Lemonade, The Hartford, Auto-Owners, and Armed Forces Insurance. No company paid for placement or reviewed this article before publication, and our rankings are editorial opinions, not endorsements.
Toyota, Sequoia, i-FORCE MAX, TRD Pro, Capstone, 1794 Edition, Toyota Safety Sense, and other model and trim names are trademarks of their respective owners.