
Cheapest Toyota GR86 Insurance: Companies, Rates & Coverage
Enthusiasts hunting for the cheapest Toyota GR86 insurance quickly learn that a $32,000 sports car can carry a premium more like a luxury SUV’s. Study B’s October 2026 average for a 40-year-old driver is $3,505 a year, or $292 a month, yet Study A puts a 2025 GR86 at $2,176 with Progressive and $5,997 with Allstate.
The GR86 is a small, rear-wheel-drive coupe built with Subaru, which sells a near twin as the BRZ. It uses a 228-horsepower 2.4-liter flat-four and offers a six-speed manual as standard, with a six-speed automatic as an option. The current generation arrived for the 2022 model year, replacing the Toyota 86, and Toyota sold 9,940 GR86s in the United States in 2025. Comparing the GR86 with vehicles with lower sample insurance costs can help buyers understand the trade-off.
This guide explains what GR86 owners pay and how to pay less. It ranks the 10 cheapest companies and the best ones for service, compares liability-only and full coverage, and covers trims, model years back to the Toyota 86, the 2027 update, crash tests, track-day coverage, rivals, state prices, 10 discounts, and advice for young drivers, seniors, and military families.
Toyota GR86 insurance at a glance
| Measure | Figure | Source |
| Average full coverage, 40-year-old driver | $3,505 a year ($292 a month) | Study B, Oct 2026 |
| Average liability-only (50/100/50) | $1,148 a year | Study B, Oct 2026 |
| Cheapest national company, 2025 model, 40-year-old | State Farm, $2,624 a year | Study B, Oct 2026 |
| Cheapest company open to all, 2025 model, 30-year-old | Progressive, $2,176 a year | Study A |
| Average for a 40-year-old with good credit | $2,389 a year | Study D |
| Average for an 18-year-old male driver | $11,545 a year | Study C, Mar 2026 |
| Five-year insurance estimate, 2025 model | $18,175 | Study E |
Each study prices its own sample driver, limits, and deductible, so compare figures within one study. Full study names appear in the Sources section.
10 GR86 insurers to compare: published rates, not a universal ranking
Two published studies provide company-level GR86 premiums, but they use different drivers and assumptions. The following companies are shown as a comparison shortlist, not a mathematically valid cross-study ranking of the cheapest insurers. Compare prices only within the same study and request matching coverage quotes from companies operating in your state.
2025 GR86 full coverage by company in two studies (per year)
| Insurer | Study A, 30-year-old male | Study B, 40-year-old driver | Study B, Florida |
| State Farm | $2,601 | $2,624 | $2,043 |
| Progressive | $2,176 | $3,426 | $4,890 |
| Travelers | — | $2,631 | $2,479 |
| USAA* | $1,914 | $1,903 | — |
| Erie | $2,380 | $2,000 | — |
| GEICO | $2,860 | $2,669 | $3,178 |
| Nationwide | $2,453 | $3,054 | $2,379 |
| American Family | $3,666 | $2,956 | — |
| Allstate | $5,997 | $4,154 | $4,516 |
| Farmers | $4,982 | $4,941 | — |
Full coverage. Study A: 30-year-old male, no violations. Study B: 40-year-old, 100/300/100 with a $500 deductible, October 2026; Erie and American Family figures come from Study B’s broader company list, and the Florida column prices a GR86 in that state. *USAA sells only to military families.
1. State Farm
State Farm is the cheapest national company in Study B for a 2025 GR86, at $2,624 a year, and it charges almost the same in Study A, $2,601. It also had the lowest price in Study B’s Florida sample, $2,043.
2. Progressive
Progressive is the cheapest company open to everyone in Study A, at $2,176 a year for a 2025 model. Study B prices it much higher, at $3,426, so your profile and state will decide whether it wins.
3. Travelers
Travelers charges $2,631 a year in Study B, just $7 more than State Farm, and for the 2022 to 2024 models it charged under $2,000 a year there, the lowest of any company open to everyone.
4. USAA
USAA has the lowest GR86 price in both studies, $1,914 a year in Study A and $1,903 in Study B. Only military members, veterans, and their families can buy it.
5. Erie
Erie charges $2,380 a year in Study A and $2,000 in Study B’s full company list. It sells in a limited number of states but leads three regions in J.D. Power’s 2026 satisfaction study.
6. GEICO
GEICO costs $2,669 a year in Study B and $2,860 in Study A, and it was one of the cheapest companies for the older Toyota 86 in Study B.
7. Nationwide
Nationwide charges $2,453 a year in Study A and $3,054 in Study B. It was second-cheapest in Study B’s Florida sample, at $2,379.
8. American Family
American Family costs $2,956 a year in Study B’s company list and $3,666 in Study A, and it sells in fewer states than the national companies.
9. Allstate
Allstate charges $4,154 a year in Study B and $5,997 in Study A, the highest price in that study.
10. Farmers
Farmers costs about $4,950 a year in both studies. Its bundle savings of 10% or more help homeowners, but it is rarely the cheapest choice for a GR86.
PRO TIP #1
Quote State Farm, Progressive, and Travelers first, then add Erie or USAA if either is available to you. In Study A, Allstate charges $3,821 a year more than Progressive for the same 2025 GR86.
GR86 insurers rated on service
A crash in a low, wide sports car can bring a costly repair bill, so how an insurer treats you after a claim matters. We looked at each insurer’s J.D. Power 2026 satisfaction scores, AM Best financial strength rating, and NAIC complaint index, where 1.00 is the expected number of complaints for a company of its size.
Service ratings for GR86 insurers
| Insurer | J.D. Power 2026 (regional range) | AM Best rating | NAIC complaint index |
| State Farm | 632 to 669 | A+ | 0.79 |
| Progressive | 604 to 645 | A+ | 0.71 |
| Travelers | 584 to 657 | A++ | 0.52 |
| USAA* | 707 to 763 | A++ | 1.18 |
| Erie | 652 to 704 | A+ | 0.89 |
| GEICO | 631 to 668 | A++ | 0.69 |
| Nationwide | 612 to 685 | A | 0.63 |
| American Family | 632 to 649 | A | 0.33 |
| Allstate | 612 to 660 | A+ | 1.10 |
| Farmers | 558 to 675 | A | 0.86 |
J.D. Power results represent regional satisfaction scores, not one national ranking. AM Best ratings reflect the listed insurers and legal entities and can change; State Farm Mutual Automobile Insurance Company was downgraded from A++ to A+ on November 14, 2025. NAIC complaint indexes are reported by third-party source and should be matched to the actual underwriting company and year. *USAA has eligibility restrictions.
Best mix of price and support: State Farm
State Farm posted the lowest rate among insurers open to most drivers in Study B for the specified 2025 GR86 sample. Its AM Best financial strength rating was reduced to A+ in November 2025, and its quoted price cannot be assumed to apply to other drivers or states.
Cheapest for a 30-year-old: Progressive
Progressive led the companies open to everyone in Study A and holds an A+ rating with a complaint index of 0.71.
Fewest complaints among the leaders: Travelers
Travelers pairs a near-tie with State Farm on price in Study B with an A++ rating and a complaint index of 0.52.
Best claims service: Amica and Nationwide
J.D. Power’s October 2026 claims study ranked Amica first with 775 points and Nationwide second with 743, compared with an average of 700.
Top choice for military drivers: USAA
USAA is the cheapest company in both GR86 studies and scored 707 to 763 in every J.D. Power region.
PRO TIP #2
If you have added aftermarket wheels, an exhaust, or a body kit, ask each company about custom parts and equipment coverage. Policies differ on how much add-on equipment they cover, so get the limit in writing.
The single cheapest GR86 insurer
There is no verified single cheapest GR86 insurer for most drivers. State Farm was the lowest-priced broadly available carrier among the specific insurers in Study B, at $2,624 per year; Progressive led the broadly available companies in Study A, at $2,176. Different drivers, locations and coverages explain why these rankings should not be combined into one universal winner.
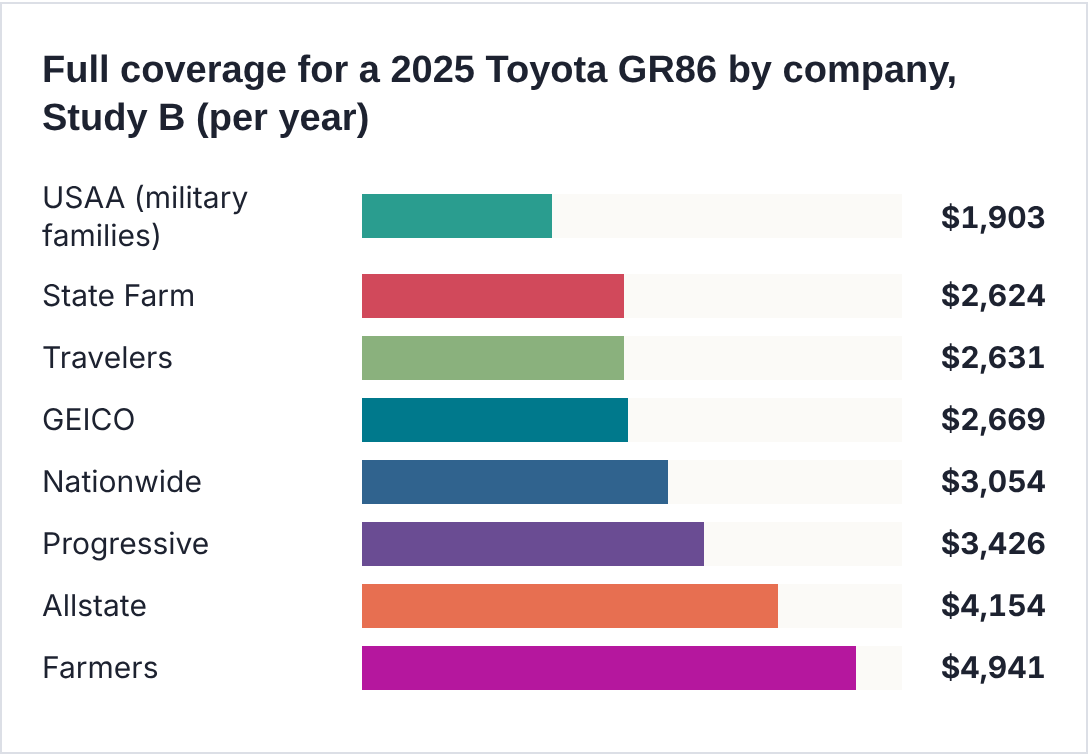
40-year-old driver, clean record, 100/300/100 with a $500 deductible. Source: Study B, Toyota GR86 car insurance, October 26, 2026.
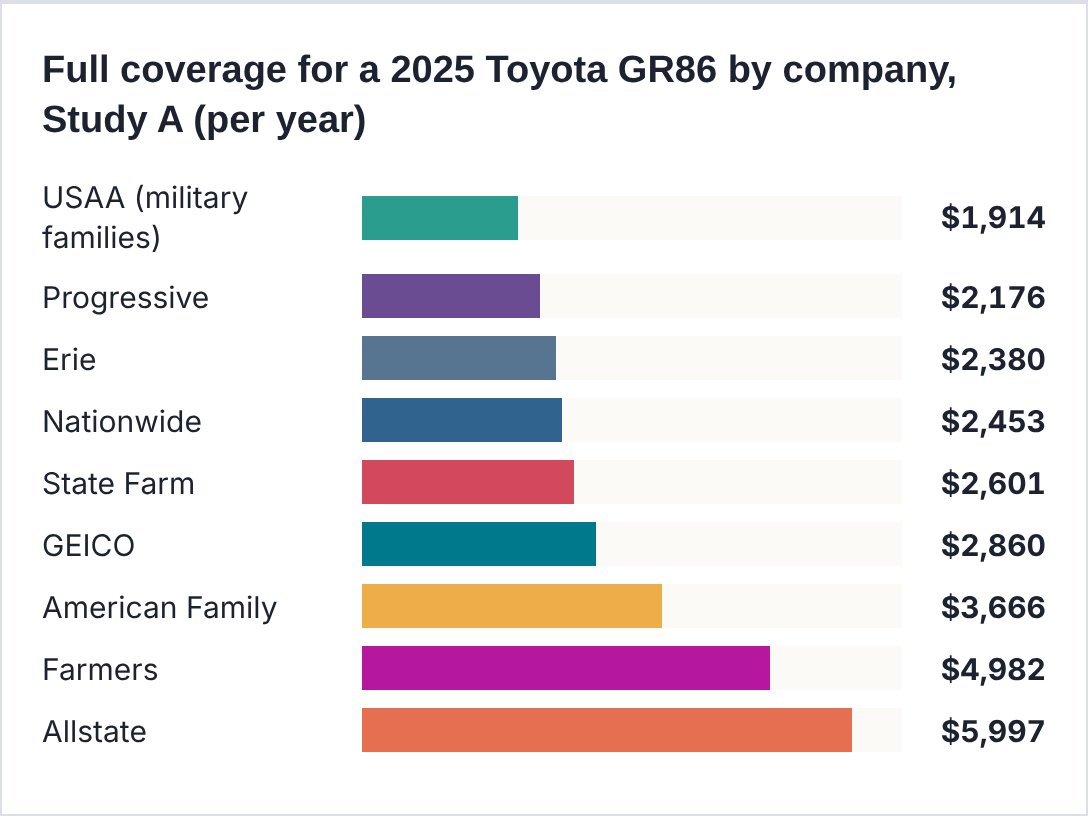
30-year-old male, full coverage, no violations. Source: Study A, Toyota GR86 insurance.
Getting a lower GR86 quote
- Note your model year, trim, and transmission, and whether you have the Performance Package.
- List all modifications, from wheels to exhaust, so they are covered.
- Quote State Farm, Progressive, Travelers, and Erie, plus USAA if you qualify. comparing auto insurance quotes with identical limits is useful when choosing coverage.
- Price the same coverage with a $500 deductible and with a $1,000 deductible. car insurance deductibles and out-of-pocket claims is useful when choosing coverage.
- Ask about telematics, good student, and bundle discounts.
How we put this list together
We gathered GR86 and Toyota 86 rates from five sources published or updated between 2025 and November 2026. Studies A and B list prices by company and model year, so they set the ranking, and the others supply averages, age and credit data, and five-year costs. We then compared service ratings. The Sources section names Studies A through E.
Toyota’s own auto insurance
Toyota Insurance Management Solutions sells Toyota Auto Insurance, with claims support from Toggle, a Farmers company. Its last announced expansion, in 2023, covered 12 states, including Arizona, California, Colorado, Georgia, Illinois, Ohio, and Texas, and it can also insure other brands you own. Add it to your list if it is sold in your state.
GR86 insurance vs. other Toyotas
In Study B, the GR86 is the second most expensive Toyota to insure, at $3,505 a year for a 40-year-old. Only the GR Supra costs more, at $3,564, and the GR86 costs $746 more than a Corolla and $616 more than a Camry.
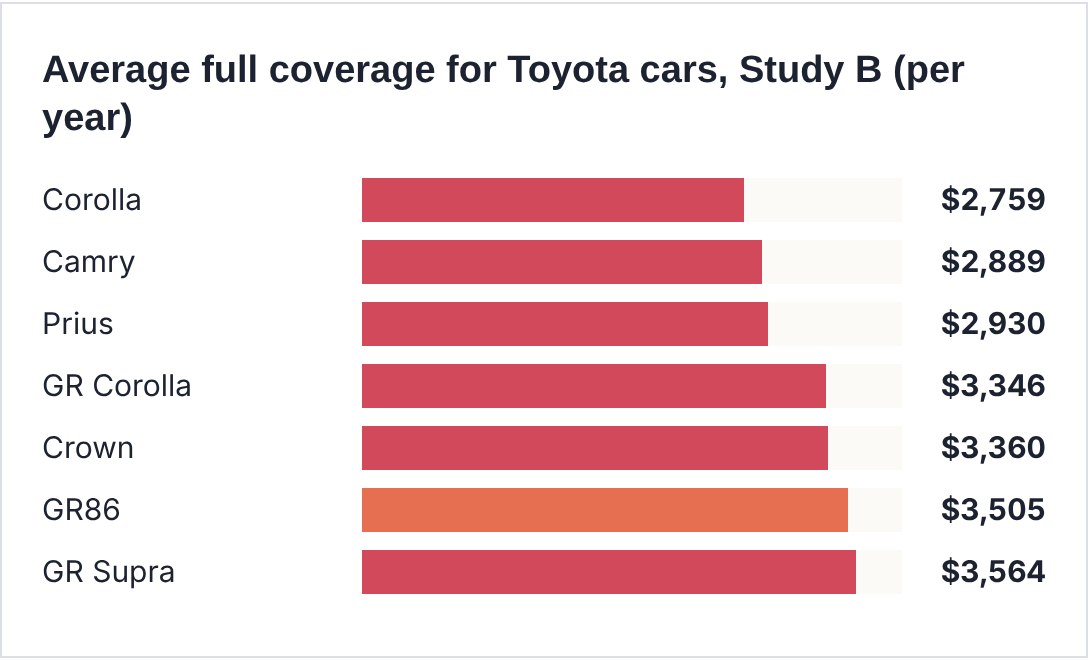
40-year-old driver, clean record, 100/300/100 with a $500 deductible. Source: Study B, Toyota insurance, October 26, 2026.
Study D sees it differently. Its estimate for a 40-year-old with good credit is $2,389 a year for the GR86, less than its figures for the Corolla, at $2,642, and the GR Corolla, at $2,627. The two studies use different methods, which is one more reason to get real quotes.
What pushes GR86 premiums up
- Sports car status. In Study B’s Toyota table, the three GR performance models, the GR86, GR Corolla, and GR Supra, are among the four most expensive Toyotas to insure.
- Young drivers. Study C puts an 18-year-old male in a GR86 at $11,545 a year, second only to the GR Supra among Toyotas.
- Repair costs. Low-slung body panels, performance tires, and optional Brembo brakes on the Performance Package add to the cost of a repair.
- Modifications. Wheels, exhausts, and suspension parts are common upgrades, and coverage for them may cost extra.
Liability-only coverage for a GR86
Liability-only insurance pays for damage and injuries you cause to others, but not for your own car. Study B prices 50/100/50 liability on a GR86 at $1,148 a year, about $96 a month, against $3,505 for full coverage.
Liability-only vs. full coverage for Toyota cars, Study B (per year)
| Model | Liability only | Full coverage | Full vs. liability premium gap* |
| Corolla | $1,186 | $2,759 | 57% |
| Camry | $1,170 | $2,889 | 60% |
| GR Corolla | $1,123 | $3,346 | 66% |
| GR86 | $1,148 | $3,505 | 67% |
| GR Supra | $1,046 | $3,564 | 71% |
40-year-old driver, clean record; full coverage is 100/300/100 with a $500 deductible, while the liability-only sample is 50/100/50. *Gap = (full coverage premium − liability-only premium) ÷ full coverage premium. Because liability limits differ, this is not the portion of the premium that pays for damage to the GR86. Source: Study B, October 2026.
In this dataset, full coverage costs substantially more than liability-only. The premium difference is not a measured collision-and-comprehensive premium: it can also reflect different bodily injury and property damage liability limits and other coverages, so it must not be labeled the cost of insuring the GR86 itself.
When liability-only can work
It can make sense on an older, paid-off Toyota 86 or early GR86 that you could replace without hardship. On a newer car, or any car with a loan, keep full coverage, since your lender will require it and a single crash could total a car worth $30,000 or more. Before deciding, compare the limits of liability-only car insurance with the cost of protecting the vehicle itself.
PRO TIP #3
Even on an older 86, keep comprehensive coverage. It is usually the cheaper part of full coverage and protects against theft, vandalism, hail, and flood.
Full coverage for a GR86
Full coverage combines liability with collision and comprehensive. Across the studies below, it ranges from $2,389 to $3,635 a year, depending on the driver and the method. For a broader explanation of policy components, see collision, comprehensive and liability coverage basics.
GR86 full coverage by study
| Study | Full coverage | Sample driver and model |
| Study B (Oct 2026) | $3,505 a year | 40-year-old, 100/300/100, $500 deductible, 2025 model |
| Study C (Mar 2026) | $3,505 a year | 40-year-old male, 100/300/100 |
| Study A, 2025 model | $3,136 a year | 30-year-old male, no violations |
| Study D | $2,389 a year | 40-year-old, good credit, about 13,000 miles a year |
| Study E, 2025 model | $3,635 a year | Five-year estimate of $18,175, divided by five |
Study E’s yearly figure is our division of its five-year total. Sources: Studies A through E.
Five years of GR86 insurance
Insurance is the biggest running cost of GR86 ownership in Study E. Its five-year insurance estimate for a 2025 model, $18,175, is nearly three times its $6,682 fuel estimate and more than half the car’s sticker price.
Five-year GR86 insurance estimates
| Source | Five-year insurance cost | Per year |
| Study B average x 5 | $17,525 | $3,505 |
| Study D average x 5 | $11,945 | $2,389 |
| Study E, 2025 model | $18,175 | $3,635 |
The Study B and D five-year figures and the per-year values are our arithmetic. Study E publishes its own five-year total.
GR86 trims and what they mean for insurance
The referenced 2026 GR86 pricing covers the base model, Premium and limited Yuzu Edition. No rate study here establishes which trim has the lowest insurance premium; purchase price alone cannot reliably predict a trim-specific insurance difference.
2026 Toyota GR86 prices by trim
| Trim | Price with destination | Key features |
| GR86 | $31,995 | Six-speed manual standard; automatic $1,100 extra; Performance Package optional |
| Premium | $34,595 | 18-inch wheels and upgraded equipment; GR Aero Kit optional |
| Yuzu Edition | $37,560 | Limited to 860 cars; Yuzu Yellow paint; Performance Package with Brembo brakes and Sachs dampers |
Prices as of October 2025, including a $1,195 destination fee, from the vehicle sources listed in Sources.
Base GR86
The base GR86 is the least expensive version to buy, and its lower value leaves less for collision and comprehensive coverage to protect. It offers the Performance Package, with Brembo brakes and Sachs dampers, as an option.
Premium
The Premium adds $2,600 to the price, along with 18-inch wheels and extra equipment, including rear sonar warning. Its higher value adds a little to collision and comprehensive costs.
Yuzu Edition
Only 860 Yuzu Editions were built for the United States. Because of its special paint and small production run, ask your insurer whether it offers agreed value or original-parts coverage if you own one.
Manual or automatic
The automatic transmission was priced higher in the 2026 source. Historical IIHS crash-prevention equipment and award eligibility differed by transmission; that older finding should not be assumed to describe all 2026 or 2027 manual-transmission vehicles. Confirm equipment for the exact model year.
PRO TIP #4
Choosing between the base GR86 and Premium? Ask for two insurance quotes with identical limits and deductibles. A $2,600 vehicle price difference does not establish that the insurance premium will increase by the same amount or by a fixed percentage.
What to expect from the 2027 GR86
Toyota announced updates to the U.S.-market 2027 GR86 in June 2026 and indicated a summer 2026 dealer arrival. These are vehicle changes, not insurer-verified 2027 rates:
- A retuned throttle for smoother response and a revised shift feel between fifth and fourth gear.
- A new Thunder Gray paint color and an available Cockpit Red interior.
- Revised cameras for better vehicle and object detection.
- No change to the exterior design or the 228-horsepower engine.
No cited rate comparison in this article establishes company-level insurance premiums for a 2027 GR86. Check the current U.S. Toyota MSRP separately and quote the exact VIN and trim rather than extrapolating a 2025 rate.
Crash tests, safety gear, and recalls
IIHS reported strong results for the tested GR86 configurations, but the 2022 TOP SAFETY PICK+ award is a historical award tied to that year and equipment; it is not proof that every 2027 trim qualifies for the same award. Confirm current model-specific ratings, headlights and crash-prevention equipment before comparing trims.
IIHS ratings for the Toyota GR86
| Test or feature | Rating |
| Small overlap front, driver and passenger sides | Good |
| Headlights, every trim and transmission | Good |
| Front crash prevention, pedestrian (day) | Superior |
| Child seat anchors (LATCH) | Acceptable |
| 2022 award | Top Safety Pick+ (automatic models) |
Sources: IIHS, 2025 Toyota GR86 ratings, and May 2022 coverage of the GR86 and Subaru BRZ awards listed in Sources.
The rear seats are small, and only two positions have full child seat anchors, so the GR86 is best treated as a second car for families with young children.
Recall to check
In 2023, Subaru reported a defect in about 5,700 2022 GR86s built from November 2021 to April 2022. The rear light assemblies could leave the turn signal temporarily inoperable, so drivers behind might not see a turn or hazard signal. Dealers replace both rear light assemblies free of charge. Check your VIN at nhtsa.gov, especially on a used 2022.
Track days and your GR86 insurance
The GR86 is built for driving enthusiasts, and many owners take it to autocross or track events. Many personal auto policies exclude damage that happens during racing or timed events, so read your policy’s exclusions before you go.
- Ask your insurer in writing whether high-performance driving events are covered or excluded.
- If they are excluded, look into separate track-day insurance, which some specialty insurers sell for single events.
- Illegal street racing can trigger exclusions or other coverage disputes. Do not assume an automatic denial or coverage; the outcome depends on the policy and jurisdiction.
GR86 and Toyota 86 insurance by model year
Older cars cost less to insure. In Study A, a 30-year-old pays an average of $3,136 a year for a 2025 GR86 but $2,607 for a 2022, the first year of the current generation, a saving of $529.
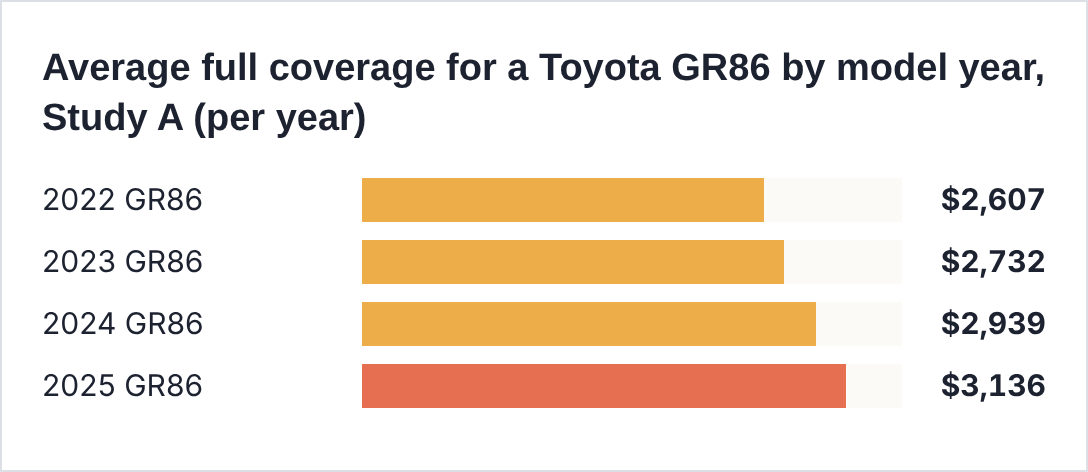
30-year-old male, full coverage, no violations. Source: Study A, Toyota GR86 insurance.
Study B goes further back, to the earlier Toyota 86 of 2018 to 2020. It lists no 2021 model, and its prices fall steadily with age for most companies.
GR86 and Toyota 86 full coverage by company and model year, Study B (per year)
| Insurer | 2025 | 2023 | 2022 | 2020 | 2018 |
| USAA* | $1,903 | $2,021 | $1,890 | $1,708 | $1,574 |
| State Farm | $2,624 | $2,335 | $2,253 | $2,219 | $2,088 |
| Travelers | $2,631 | $1,986 | $1,956 | $2,230 | $2,093 |
| GEICO | $2,669 | $2,479 | $2,356 | $2,061 | $1,976 |
| Nationwide | $3,054 | $3,173 | $3,164 | $3,077 | $2,941 |
| Progressive | $3,426 | $3,214 | $2,791 | $2,610 | $2,300 |
| Allstate | $4,154 | $3,784 | $3,303 | $3,298 | $3,083 |
| Farmers | $4,941 | $4,971 | $4,733 | $4,445 | $4,018 |
40-year-old driver, 100/300/100 with a $500 deductible. The 2018 to 2020 cars are the earlier Toyota 86. *USAA sells only to military families. Source: Study B, Toyota GR86 car insurance, October 26, 2026.
For a 2018 Toyota 86, USAA charges $1,574 a year and GEICO $1,976, the lowest open-to-all price in the table. Travelers is the standout for 2022 and 2023 GR86s, at under $2,000 a year.
PRO TIP #5
Buying a used 2022 GR86? Confirm the rear light recall was done, then quote Travelers, GEICO, and State Farm, the cheapest open-to-all companies for that year in Study B.
GR86 vs. other sports cars
Few studies price affordable sports cars side by side, but the data we found tells a clear story. Among Toyota’s three GR models, the GR86 is the cheapest to insure in Study D, while Study C’s national averages show a Mazda MX-5 Miata costing less than a GR86.
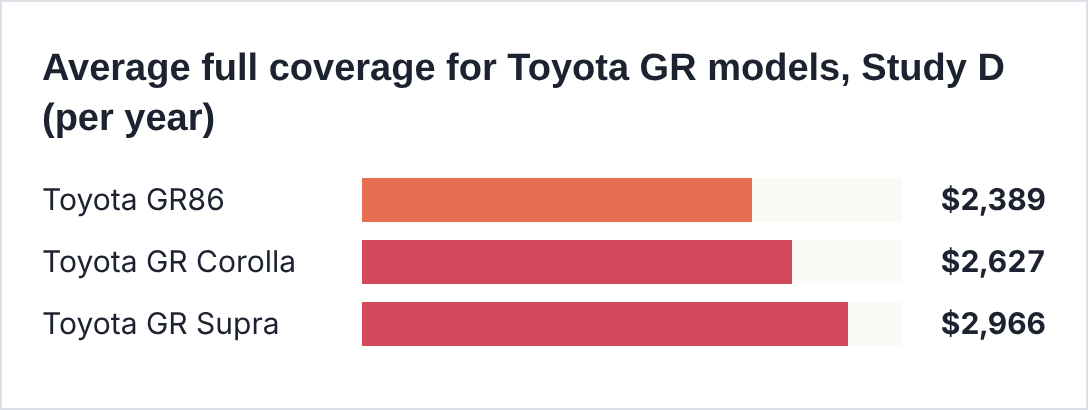
40-year-old, good driver and credit, about 13,000 miles a year. Source: Study D, Toyota insurance estimates.
In Study D, a GR86 costs $238 a year less to insure than a GR Corolla and $577 less than a GR Supra. Study B ranks the GR Corolla below the GR86, at $3,346 against $3,505, so the order depends on the study.
GR86 vs. Mazda MX-5 Miata
The Miata is a relevant competitor, but the quoted Miata and GR86 figures come from tables with different policy and sample assumptions. They do not prove that a specific driver will pay less for a Miata. Request same-driver quotes for both vehicles.
GR86 vs. Subaru BRZ
The BRZ is built alongside the GR86 and shares its engine and body. None of the studies we used published a BRZ figure on the same basis, so quote both cars with the same company if you are deciding between them.
GR86 insurance by state
Your state can change your GR86 premium more than any other single factor. Study B’s state averages run from $1,951 a year in Hawaii to $7,315 in Louisiana, a gap of more than $5,300.
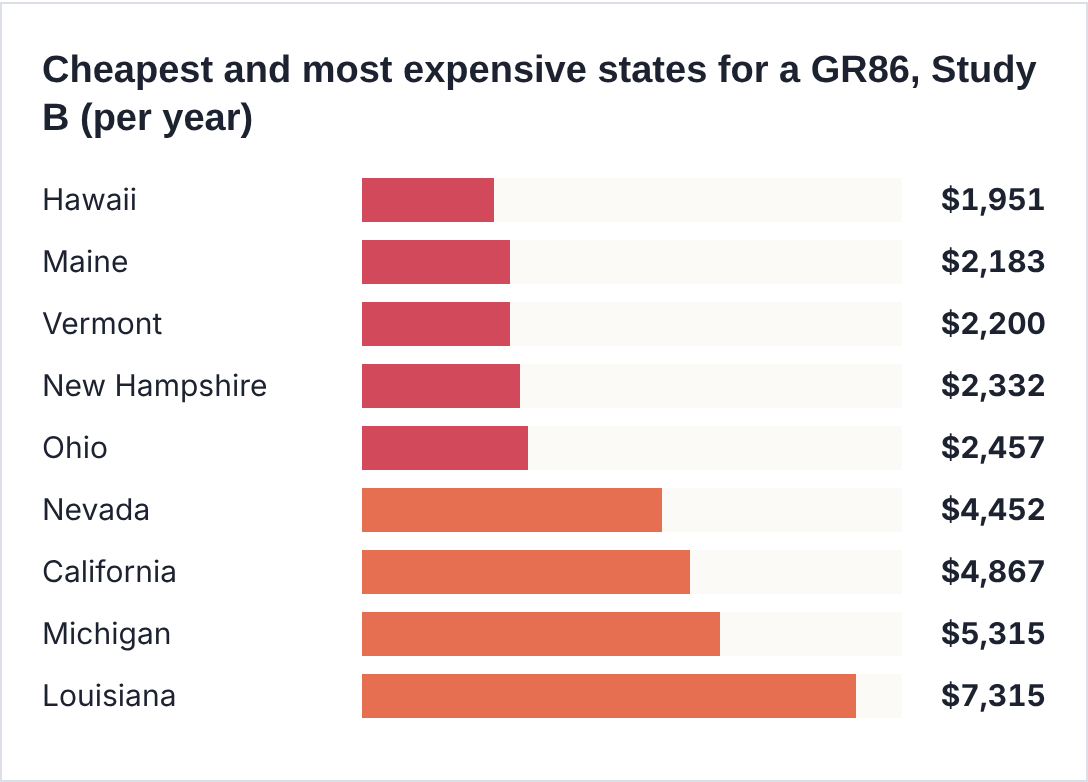
40-year-old driver, full coverage. Source: Study B, Toyota insurance, October 26, 2026.
GR86 insurance in 15 states, Study D (per year)
| State | Good driver | Recent at-fault accident | Poor credit |
| Alabama | $2,531 | $3,676 | $4,679 |
| Alaska | $2,093 | $2,902 | $2,821 |
| Arizona | $2,367 | $3,421 | $5,041 |
| Arkansas | $2,595 | $4,077 | $4,489 |
| California | $2,889 | $5,109 | $2,889 |
| Colorado | $2,696 | $3,773 | $4,787 |
| Connecticut | $3,444 | $5,342 | $6,781 |
| Delaware | $2,852 | $3,800 | $4,881 |
| Florida | $3,395 | $4,697 | $6,121 |
| Georgia | $2,768 | $4,139 | $4,173 |
| Hawaii | $1,106 | $1,501 | $1,106 |
| Idaho | $1,921 | $2,547 | $3,096 |
| Illinois | $2,011 | $3,039 | $3,465 |
| Indiana | $2,066 | $3,158 | $3,544 |
| Iowa | $1,636 | $2,244 | $2,639 |
40-year-old driver, full coverage, good credit unless noted. California and Hawaii do not allow credit-based pricing, so their good-driver and poor-credit figures match. Source: Study D, Toyota GR86 insurance.
Both studies agree that Hawaii is the cheapest state. Study D shows California drivers facing the biggest penalty for an at-fault accident, $2,220 a year.
GR86 insurance in Florida
Study B’s Florida average for a GR86 is $3,629 a year. Its Florida company sample shows a wide range, from State Farm at $2,043 to AIG at $6,353.
GR86 full coverage in Florida by company, Study B (per year)
| Insurer | Average premium |
| State Farm | $2,043 |
| Nationwide | $2,379 |
| Travelers | $2,479 |
| UAIC | $2,764 |
| GEICO | $3,178 |
| Mercury | $3,512 |
| Allstate | $4,516 |
| Progressive | $4,890 |
| AIG | $6,353 |
Florida sample from Study B, Toyota GR86 car insurance, October 26, 2026.
PRO TIP #6
Moving states with your GR86? Get quotes at the new address before you register it there. In Study B, the average in Louisiana is more than three times the average in Hawaii. State rules and rating factors also affect how credit-related insurance pricing works, where legally permitted.
Age, record, and credit: the GR86 price drivers
Study D shows how the driver changes the price of the same GR86. A 40-year-old with a clean record and good credit pays $2,389 a year. One at-fault accident lifts that to $3,508, and poor credit to $4,103, about 72% more.
GR86 insurance by age and driver profile, Study D (per year)
| Age | Good driver and credit | Recent at-fault accident | Poor credit |
| 18 | $7,541 | $11,072 | $12,953 |
| 25 | $3,404 | $4,999 | $5,848 |
| 30 | $2,652 | $3,894 | $4,556 |
| 40 | $2,389 | $3,508 | $4,103 |
| 55 | $2,132 | $3,130 | $3,662 |
Full coverage on a new GR86, about 13,000 miles a year, single-vehicle policy. Source: Study D, Toyota GR86 insurance.
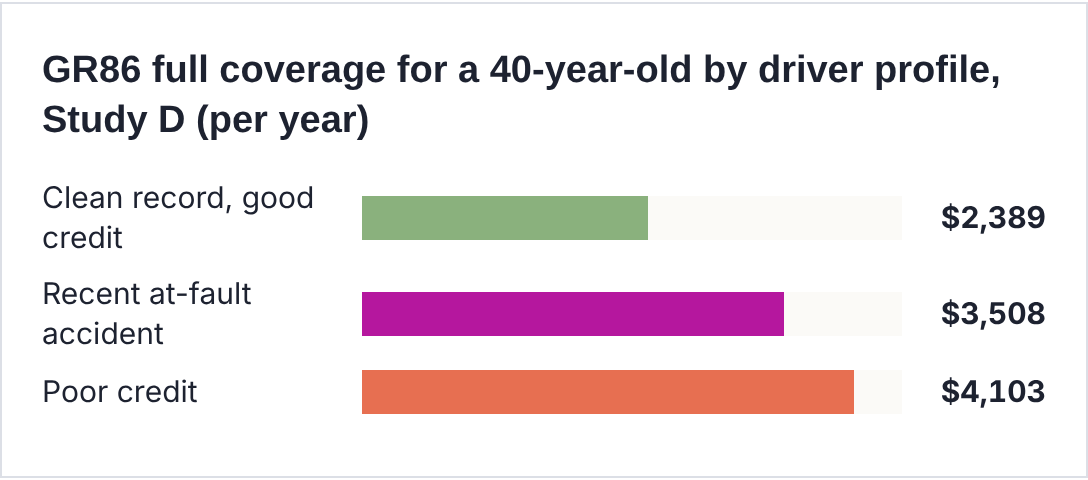
Source: Study D, Toyota GR86 insurance.
Age has the largest effect. A clean 18-year-old pays $7,541 a year, about 3.2 times the 40-year-old price, falling to $3,404 at 25 and $2,132 at 55. In states that allow credit-based pricing, poor credit costs a 40-year-old $1,714 a year extra, more than the $1,119 added by an accident.
Coverage choices for a sports car
A GR86 owner may need to check equipment coverage and track exclusions especially carefully. The following are optional protections or policy provisions, subject to eligibility, limits, exclusions and state rules:
- Custom parts and equipment. If you add wheels, an exhaust, seats, or a body kit, ask how much add-on equipment your policy covers and buy more if needed.
- Gap insurance. May cover an eligible loan shortfall after a covered total loss, subject to policy limits and exclusions; it does not automatically pay every amount owed.
- Higher liability limits. A minimum policy may not be enough if you cause a serious crash, so consider 100/300/100 or more.
- Uninsured and underinsured motorist coverage. It covers your injuries when the at-fault driver has little or no insurance.
- Rental reimbursement. A daily limit that covers a basic rental keeps you moving while the GR86 is repaired.
PRO TIP #7
Keep receipts and photos for every modification. If your GR86 is stolen or totaled, they help prove what the upgrades were worth.
Five mistakes GR86 owners make on insurance
- Not shopping around. For the same 2025 GR86, Study A’s prices run from $1,914 to $5,997 a year.
- Hiding modifications. An insurer may refuse to pay for parts it did not know about.
- Assuming track days are covered. Many policies exclude racing and timed events.
- Ignoring credit. Poor credit adds $1,714 a year for a 40-year-old in Study D.
- Putting a young driver on the GR86 by default. An 18-year-old costs $11,545 a year to insure as its main driver in Study C.
10 discounts for GR86 drivers
Every discount below is from the insurer’s own website. Offers vary by state, and the amounts are maximums or averages, not promises. Compare the final policy price with usage-based auto insurance options rather than focusing on the headline percentage.
1. Driving app programs
State Farm’s Drive Safe & Save and Liberty Mutual’s RightTrack offer up to 30%. USAA’s SafePilot gives 10% for joining and up to 30% at renewal; Nationwide’s SmartRide 10%, and Progressive says Snapshot users save $328 a year on average.
2. Good student
State Farm offers up to 25% for students with good grades, GEICO up to 15%, and Progressive about 5%. Travelers asks for a B average or better.
3. Driver training
Travelers offers a discount for young drivers who complete an approved driver education course.
4. Bundling home and auto
Progressive says bundlers save more than $1,000 a year on average, Nationwide cites $1,032, and The Hartford $963. Farmers lists savings of 10% or more.
5. Multiple vehicles
GEICO offers up to 25% for insuring more than one vehicle, and Progressive says multi-car customers save 12% on average.
6. Accident-free driving
GEICO lists up to 22% for five years with no accidents, and Travelers has a safe driver discount for households without recent accidents or violations.
7. New car
Travelers offers a discount for cars less than three years old in most states, though not in California.
8. Safety equipment
State Farm offers up to 40% off certain medical coverages for factory airbags, and GEICO lists 5% for anti-lock brakes.
9. Online quote and paperless signing
Progressive offers about 7% for an online quote and about 10% for signing documents online, and The Hartford lists 8% for quoting online.
10. Military and AARP
GEICO offers up to 15% for military members, and The Hartford takes 10% off for AARP members. See the senior and military sections below.
PRO TIP #8
If the GR86 is a weekend car, insure it on the same policy as your daily driver to earn the multi-car discount, and report its lower mileage.
GR86 insurance for teenage and young drivers
The GR86 is popular with young enthusiasts, but it is one of the most expensive Toyotas for them to insure. Study C prices an 18-year-old male as the main driver at $11,545 a year, about 3.3 times the 40-year-old price. In Study D, a clean 18-year-old pays $7,541, and one at-fault accident raises that by $3,531, to $11,072.
No study publishes GR86 prices by company for each teen age, so the guidance below combines GR86 figures with national data on the cost of adding a teen to a family policy.
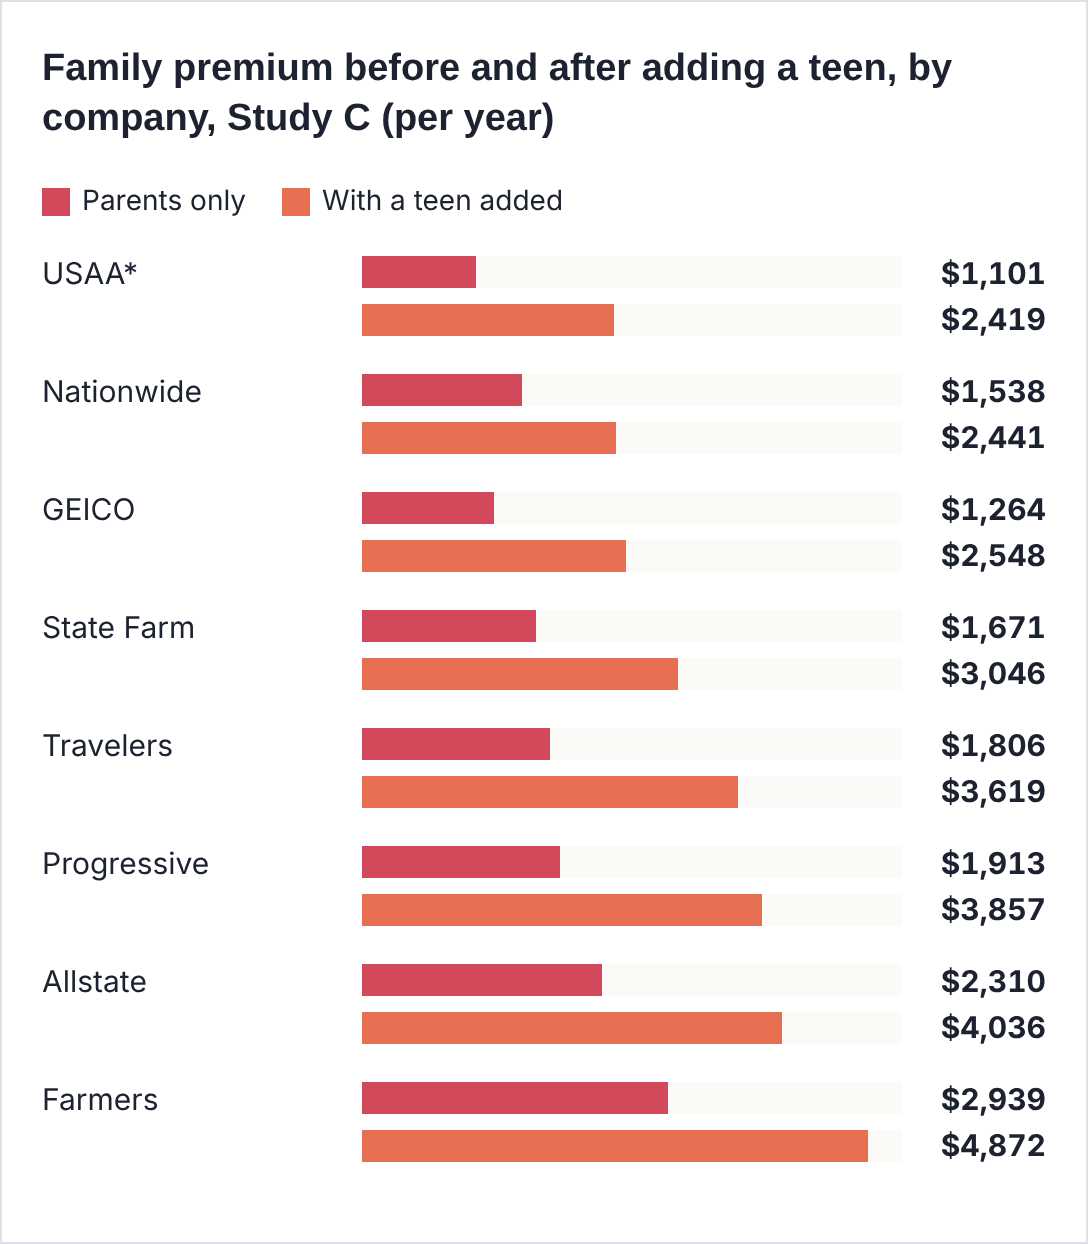
Full-coverage family premium; national data, no specific test vehicle. *USAA sells only to military families. Source: Study C.
The household-policy chart in Study C is not specific to the Toyota GR86. The reported differences by insurer describe that study’s family and vehicle assumptions and cannot be used as the incremental cost of adding a teen to a GR86 policy. Drivers should request actual quotes that include every household driver rather than assume a generic family figure applies.
Cheapest Toyota GR86 insurance for a 16-year-old
For a generic family policy—not specifically a GR86—Study C estimates about $4,050 in added annual costs for a 16-year-old. This should not be compared directly with separately insured GR86 rates, because vehicle, household and coverage assumptions differ.
Cheapest Toyota GR86 insurance for a 17-year-old
At 17, the same generic family-policy estimate falls to about $3,740 annually, but it is not GR86-specific. Study B’s separate-policy comparison uses a different study population and should be treated independently.
Cheapest Toyota GR86 insurance for an 18-year-old
Study C’s generic family-policy data estimates about $3,478 in annual additional premium for an 18-year-old, while its GR86 sample for an 18-year-old main driver is $11,545. Those numbers are not directly comparable because the vehicles, households and policies are different.
Cheapest Toyota GR86 insurance for a 19-year-old
For age 19, the reported generic added family premium was about $3,105 per year in Study C. The separate-policy prices from Study B are for a different sample, not for a quoted GR86 family-policy alternative.
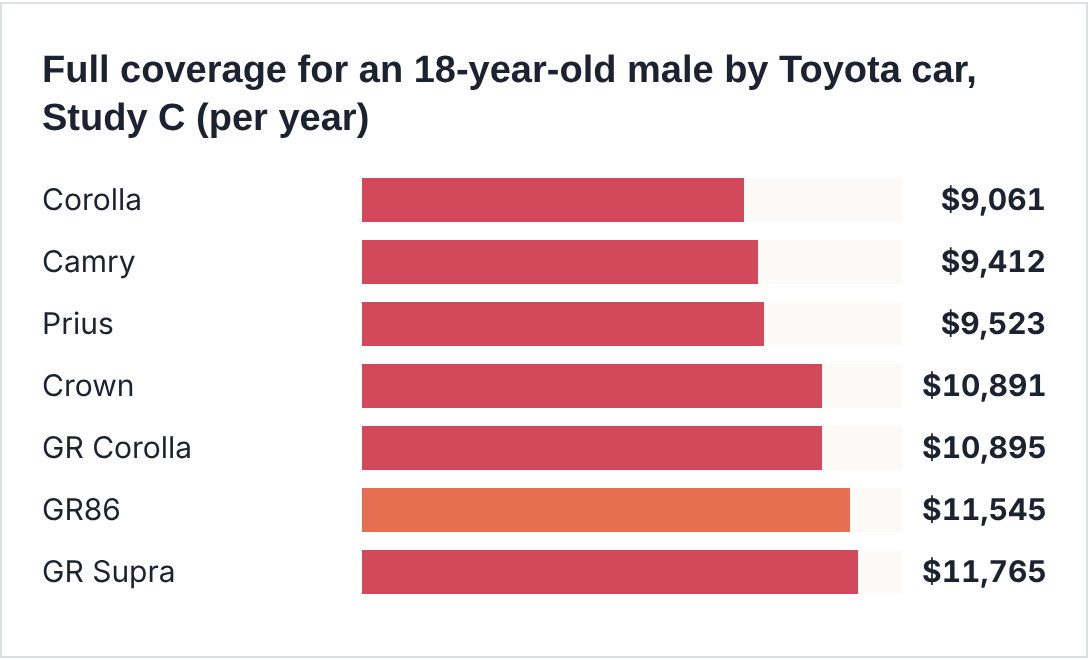
100/300/100 full coverage. Source: Study C, Toyota car insurance cost, March 23, 2026.
In the cited Study C model comparisons, the Corolla and Camry samples have lower premiums than the GR86 for an 18-year-old. These figures are model-specific estimates, whereas the teenage family-policy tables above do not use a GR86, so those costs must not be treated as GR86-specific quotes.
Ways to keep a young driver’s GR86 premium down
- Keep the young driver on a family policy rather than a separate one.
- Have them earn good student discounts of up to 25% at State Farm or 15% at GEICO.
- Complete an approved driver education course, which Travelers rewards.
- Enroll in a telematics program, and requote every birthday until 25.
- Skip modifications until the driver has a few clean years.
PRO TIP #9
Rates fall sharply in a driver’s early 20s. In Study D, a clean GR86 driver pays $7,541 at 18 but $3,404 at 25, so keep the record clean and shop again each year.
GR86 insurance for drivers 55 and older
Older enthusiasts pay some of the lowest GR86 rates. In Study D, a 55-year-old with a clean record and good credit pays $2,132 a year, $257 less than a 40-year-old. Study C’s national senior figures, which use no specific test vehicle, rise slowly from $2,353 a year at 65 to $2,498 at 70 and $2,742 at 75.
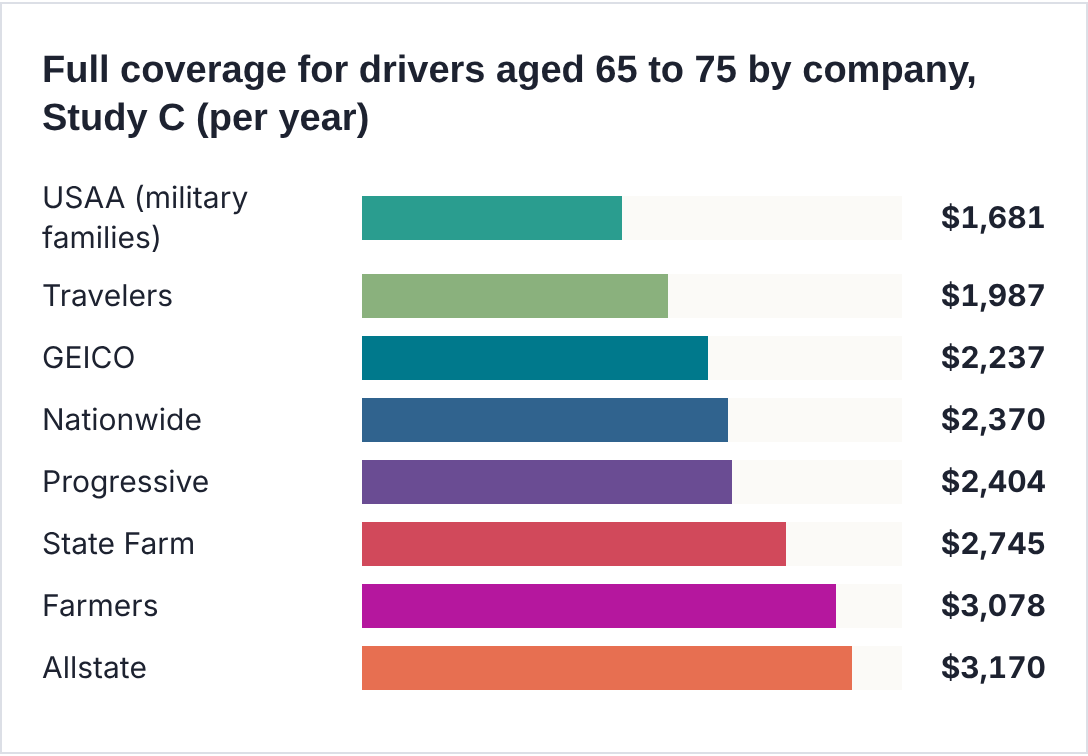
100/300/100 with a $500 deductible; no test vehicle named. Source: Study C, car insurance for seniors, April 16, 2026.
Travelers is the cheapest company open to all seniors in Study C, at $1,987 a year, and it is also among the cheapest GR86 insurers in Study B.
Savings tips for mature GR86 owners
- Take a mature driver course. AARP says 33 states and Washington, D.C., require insurers to give a discount for one, and Kiplinger reports savings of up to 10%.
- Quote The Hartford’s AARP program, which lists 10% for members, 5% for a defensive driving course, and up to 15% through its TrueLane app.
- Report a low annual mileage if the GR86 is a weekend car.
- Store it with comprehensive-only coverage over winter if your insurer and state allow it.
PRO TIP #10
Storing your GR86 for the winter? Ask whether you can drop collision and keep comprehensive while it is parked, then restore full coverage before you drive it again.
Pay-per-mile for a weekend GR86
A sports car driven mainly on weekends is a natural fit for mileage-based insurance. Nationwide SmartMiles charges a base rate plus a per-mile rate and counts only the first 250 miles of any day. It is not offered in Alaska, Hawaii, Louisiana, Michigan, North Carolina, New York, or Oklahoma. Owners with very low annual mileage can also investigate pay-per-mile car insurance savings before choosing a plan.
Lemonade, the owner of Metromile, sells car insurance in nine states and gives an example of a $29 base rate plus 6 cents a mile. Long road trips add up fast, so compare it with a standard low-mileage discount.
GR86 insurance for military families
USAA is the cheapest GR86 insurer in both company studies, at $1,914 a year in Study A and $1,903 in Study B, and it earned the highest J.D. Power scores in every region in 2026.
Full coverage for military members vs. civilians, Study C (per year)
| Insurer | Military | Civilian | Military savings |
| USAA | $1,465 | $1,572 | $107 |
| Travelers | $1,818 | $2,103 | $285 |
| Auto-Owners | $1,908 | $2,051 | $143 |
| GEICO | $1,951 | $2,148 | $197 |
| Nationwide | $2,210 | $2,463 | $253 |
| Progressive | $2,382 | $2,675 | $293 |
| State Farm | $2,575 | $2,874 | $299 |
| Farmers | $2,676 | $3,085 | $409 |
| Allstate | $2,698 | $3,205 | $507 |
Full coverage; no test vehicle named. Savings are our subtraction. Source: Study C, best car insurance for military members, August 13, 2026.
All nine companies in Study C charged service members less than civilians. State Farm, the cheapest national GR86 insurer in Study B, gave military drivers $299 off, and Travelers had the lowest military price after USAA, at $1,818.
Military discounts to ask about
- USAA advertises up to 60% off for a vehicle in storage, except in North Carolina and Virginia, and up to 15% off comprehensive coverage for a vehicle garaged on a base.
- GEICO offers up to 15% for active-duty, retired, Guard, and Reserve members and up to 25% when deployed.
- Armed Forces Insurance can arrange auto coverage for military families through partner insurers.
PRO TIP #11
Deploying and leaving your GR86 behind? A storage discount and comprehensive-only coverage can cut your bill sharply while the car sits, but restore full coverage before anyone drives it.
GR86 insurance savings in five cartoon panels
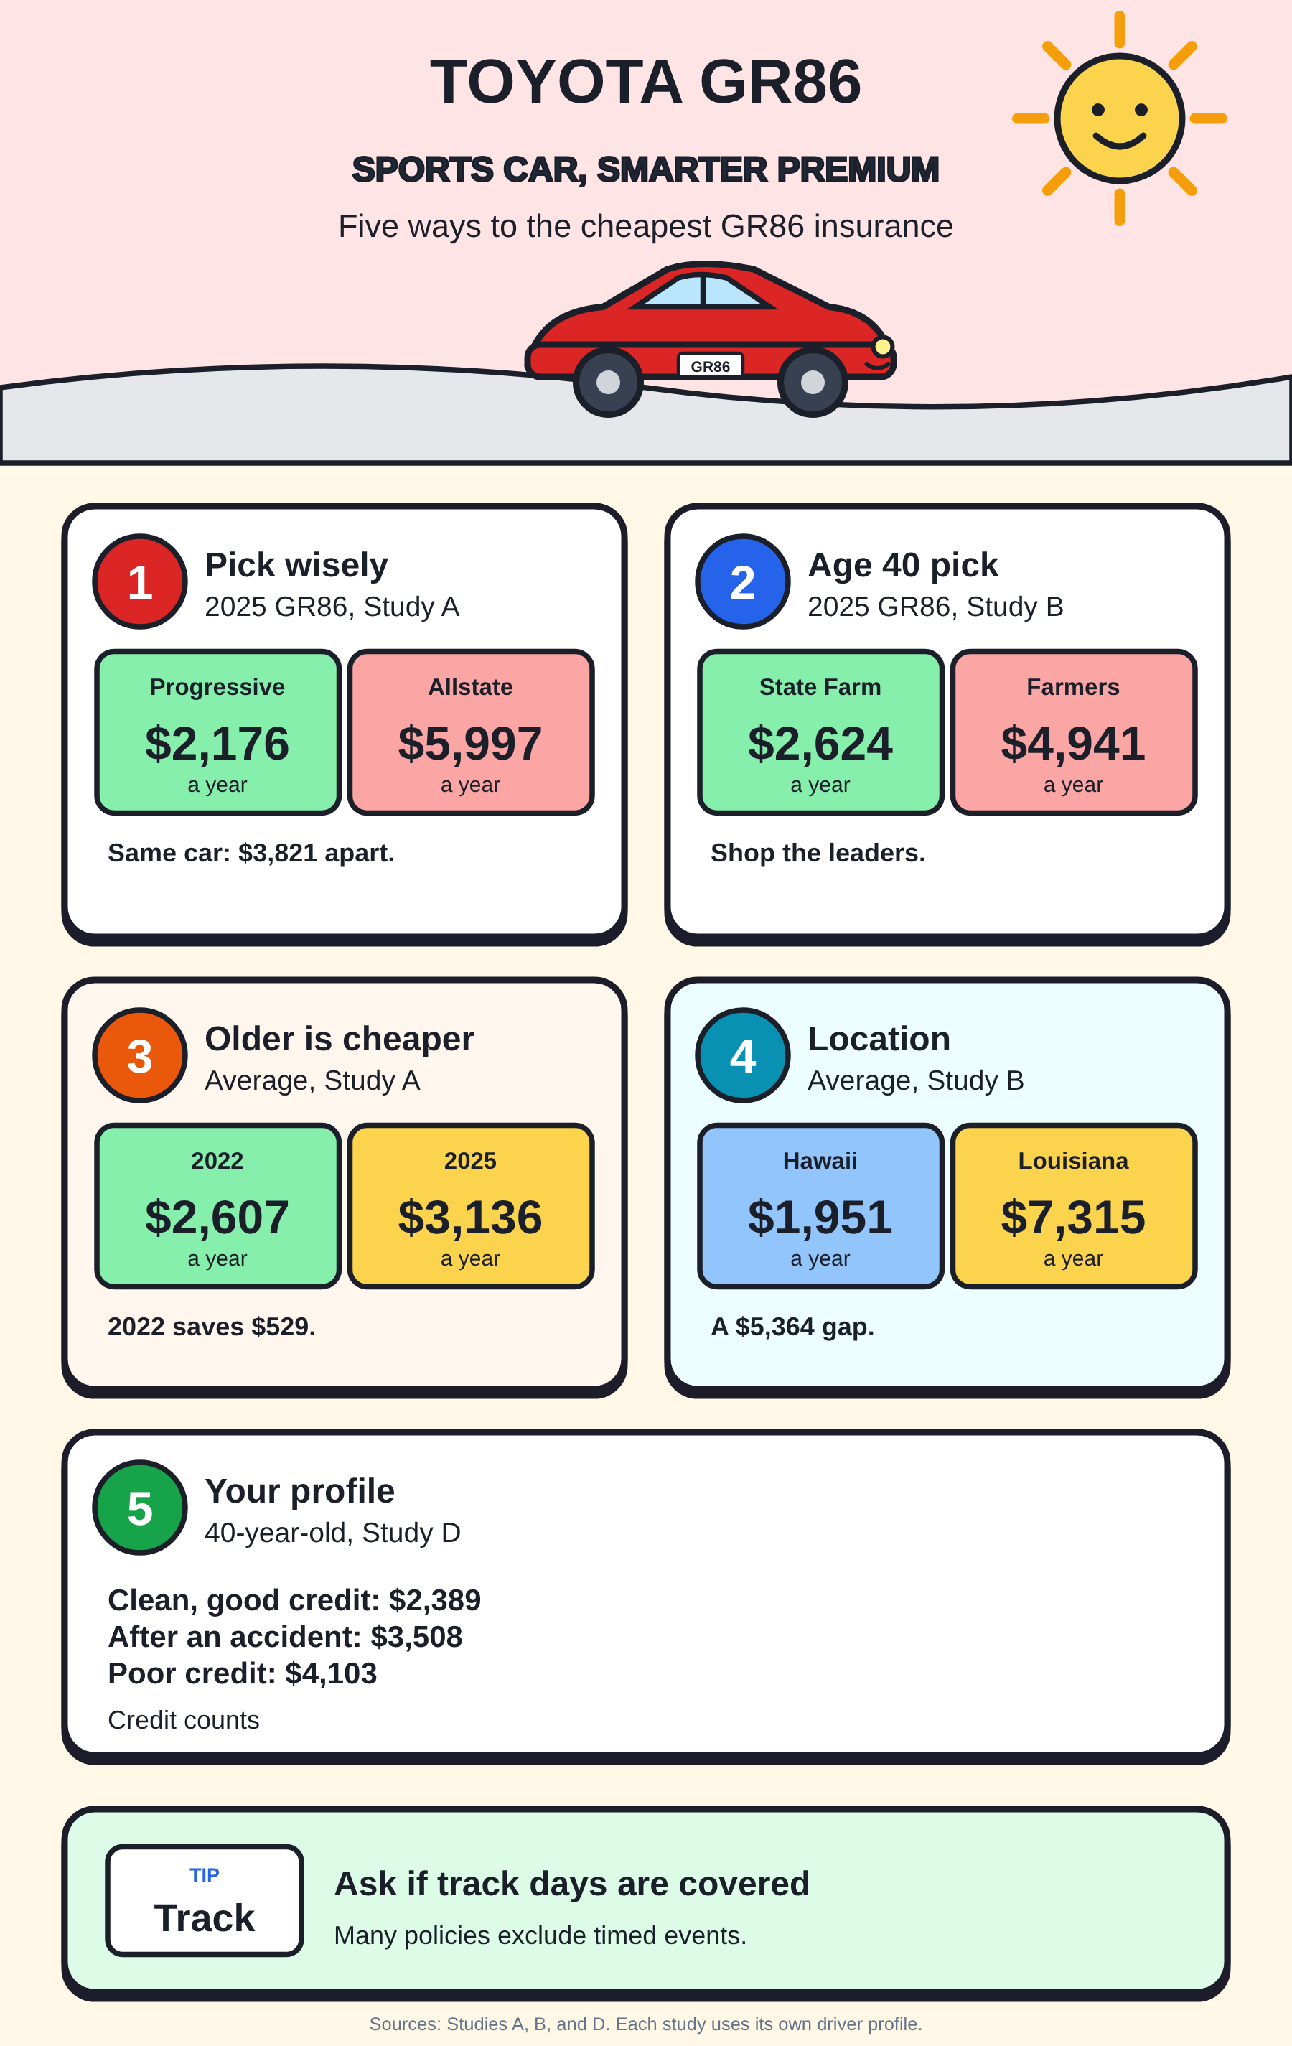
Editorial caution: this preserved infographic summarizes published studies with differing assumptions. Figures are not individualized quotes and should not be compared across sources as equivalent policies.
An original cartoon covering the biggest ways to save on GR86 insurance.
Answers about the cheapest Toyota GR86 insurance
Who has the cheapest Toyota GR86 insurance?
USAA is cheapest in both company studies, but it serves only military families. Among companies open to everyone, State Farm leads Study B at $2,624 a year for a 40-year-old, and Progressive leads Study A at $2,176 for a 30-year-old.
How much is GR86 insurance per month?
Study B’s full-coverage average is $292 a month for a 40-year-old, and Study D’s works out to about $199 a month for a driver with good credit. Liability-only averages about $96 a month in Study B.
Is the GR86 expensive to insure?
For a Toyota, yes. Study B ranks it second only to the GR Supra among Toyotas, at $3,505 a year, $746 more than a Corolla.
Is the GR86 cheaper to insure than a Miata?
The compared studies suggest that a Miata may have lower premiums, but they do not use identical methodology for both models; no universal conclusion is justified without matched quotes. Study C lists an MX-5 figure near $2,438 per year and a separate Toyota GR86 figure of $3,505.
Is an older Toyota 86 cheaper to insure?
Usually. In Study B, USAA charges $1,574 a year for a 2018 Toyota 86 and GEICO $1,976, compared with $1,903 and $2,669 for a 2025 GR86.
Will my insurance cover a track day?
Often not. Many personal auto policies exclude racing and timed events, so ask in writing and consider single-event track insurance from a specialty insurer.
Has the GR86 been recalled?
Yes. About 5,700 2022 GR86s were recalled because the rear lights could leave the turn signal temporarily inoperable. Dealers replace the light assemblies free of charge.
Which state has the cheapest GR86 insurance?
Hawaii, in both Study B, at $1,951 a year, and Study D, at $1,106 for a good driver.
How much is GR86 insurance for an 18-year-old?
Study C puts an 18-year-old male as the main driver at $11,545 a year, and Study D’s clean 18-year-old pays $7,541. Adding a teen to a family policy usually costs much less.
Are 2027 GR86 insurance rates available?
Not yet. The 2027 GR86 brings small updates, and no study had published 2027 insurance rates when we checked. Get a quote by VIN before you buy.
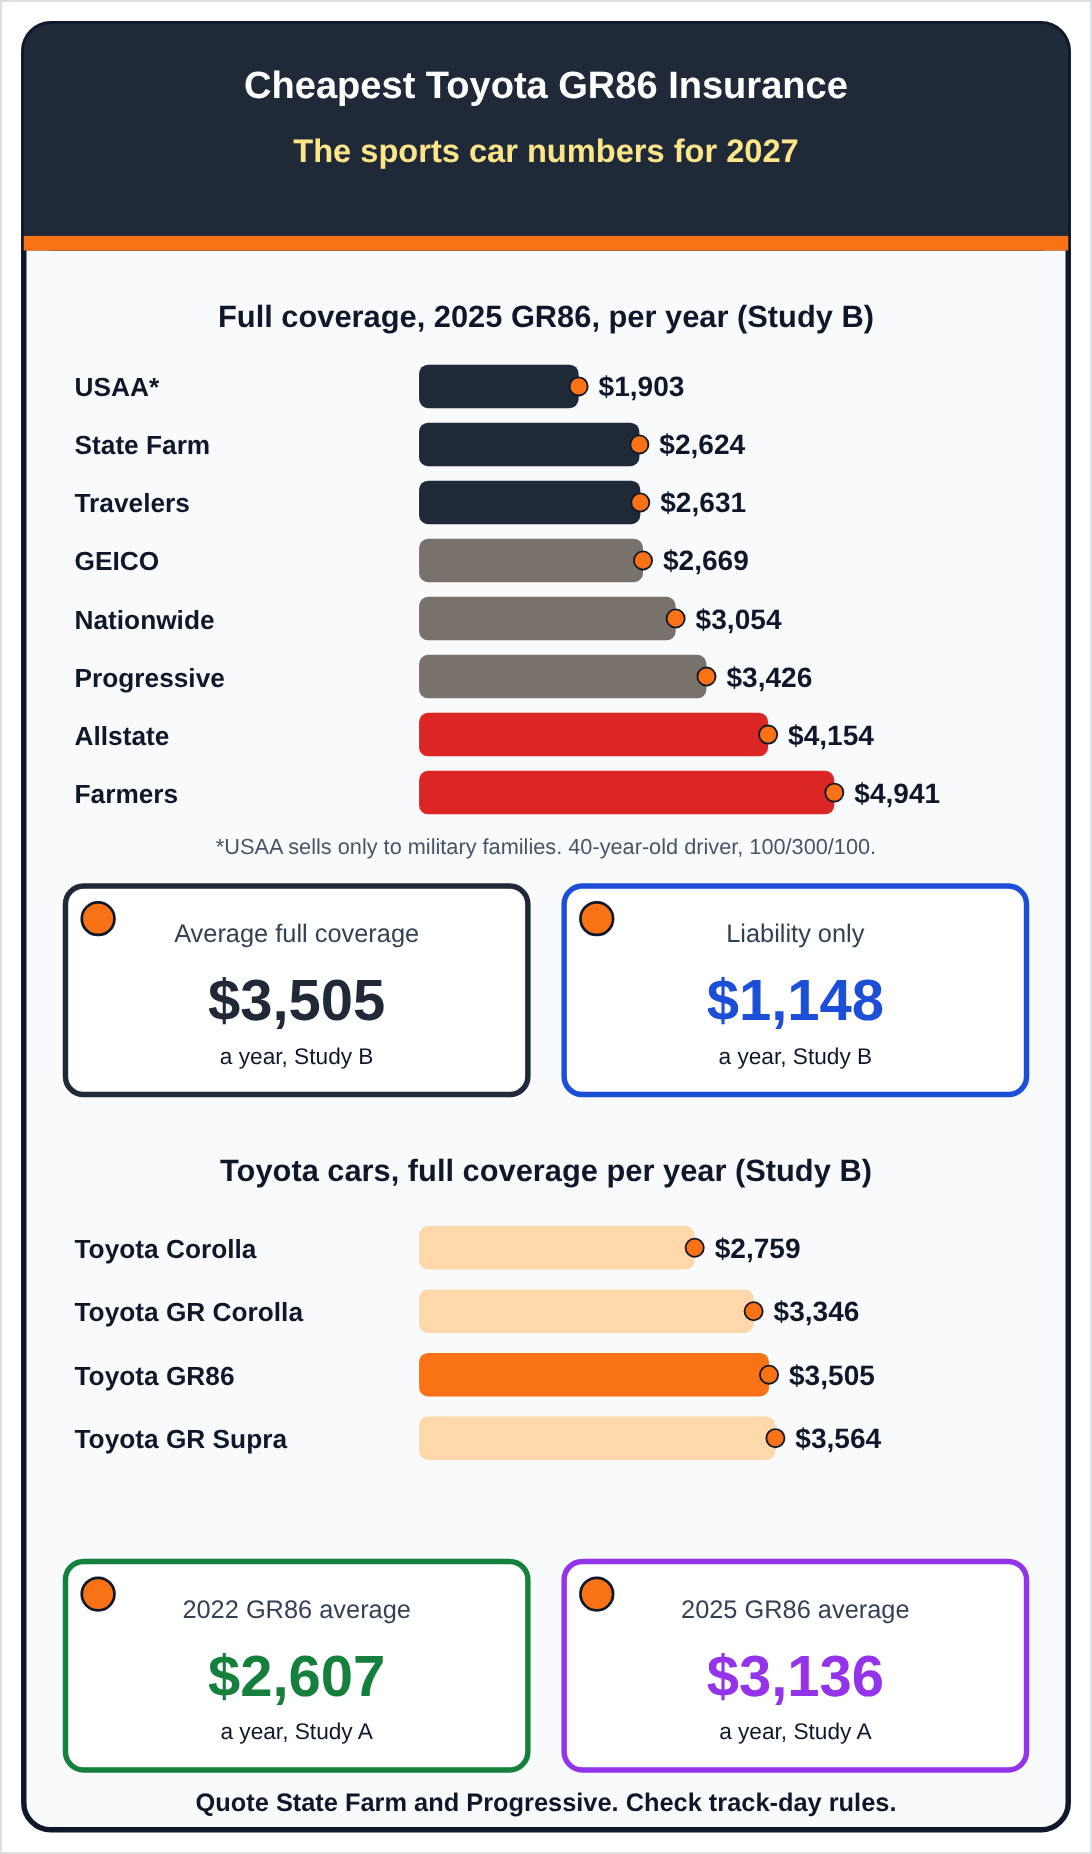
Editorial caution: this preserved infographic summarizes published studies with differing assumptions. Figures are not individualized quotes and should not be compared across sources as equivalent policies.
GR86 insurance in one picture.
The final word on the cheapest Toyota GR86 insurance
The GR86 may have substantial insurance costs relative to its purchase price, particularly for younger drivers. Study B shows an average of $3,505 a year for its sample GR86 driver, while other studies estimate materially different premiums. These are not quotes for an individual owner.
Comparing like-for-like quotes is usually more actionable than treating a multi-study ranking as a universal price list. State Farm and Travelers had lower prices in Study B, Progressive led among broadly available carriers in Study A, and USAA was lowest among eligible drivers in both. Check modification coverage, track-day exclusions, driver eligibility, and low-mileage discounts before selecting a policy. comparing insurance companies beyond headline rates is useful when choosing coverage.
Sources
- Study A: The Zebra, Toyota GR86 insurance.
- Study B: Insurance.com, Toyota GR86 car insurance and Toyota insurance (October 26, 2026), and teen car insurance costs (August 13, 2026).
- Study C: CarInsurance.com, Toyota car insurance cost (March 23, 2026); cheapest cars to insure (May 5, 2026); cost of adding a teen driver (August 4, 2026); car insurance for seniors (April 16, 2026); best car insurance for military members (August 13, 2026); top financially rated insurers (December 16, 2025); and insurers ranked by NAIC complaint data (August 13, 2026).
- Study D: CarEdge, Toyota GR86 insurance and Toyota model insurance comparison.
- Study E: Kelley Blue Book, 2025 Toyota GR86 cost to own.
- Service ratings: J.D. Power 2026 U.S. Auto Insurance Study coverage (June 9, 2026); J.D. Power 2026 regional scores; Amica, J.D. Power 2026 results; and J.D. Power 2026 Auto Claims Satisfaction Study coverage (October 27, 2026).
- Insurer pages: Travelers discounts; Progressive discounts; GEICO discounts; GEICO military discounts; State Farm discounts; Nationwide discounts; Nationwide SmartMiles; Lemonade, pay-per-mile car insurance (June 25, 2026); Liberty Mutual RightTrack; Farmers discounts; USAA discounts; The Hartford AARP discounts; Armed Forces Insurance, auto; and Toyota, Toyota Auto Insurance.
- Vehicle and safety data: Cars.com, how much is the 2026 Toyota GR86 (October 1, 2025); Cars.com, what’s new with the 2027 GR86 (June 2, 2026); CarGurus, 2027 Toyota GR86 pricing and specs; Toyota, 2025 U.S. sales results (January 5, 2026); IIHS, 2025 Toyota GR86 ratings; Auto123, GR86 and BRZ earn Top Safety Pick+ (May 4, 2022); and NHTSA, recall 23V609 notice.
- Other sources: AARP, auto insurance discounts; and Kiplinger, ways seniors save on car insurance (September 3, 2026).
- AM Best, State Farm auto insurer rating downgrade (November 14, 2025); Toyota USA, 2027 GR86 official model update (June 1, 2026); NAIC, consumer auto insurance coverage explanation.
Disclaimer
This article draws on published insurance rate studies, an ownership cost estimate, customer satisfaction surveys, financial strength ratings, IIHS crash tests, and NHTSA recall filings for the Toyota GR86 and the earlier Toyota 86. It is general information and does not replace advice from a licensed insurance agent, attorney, or financial professional. Prices are averages, estimates, or sample quotes for each source’s chosen driver.
Your premium depends on where you live, your age and driving record, credit where state law allows it, who else drives your car, your mileage, your GR86’s model year, trim, and transmission, any modifications, and the limits and deductible you choose. Coverage for aftermarket parts, track events, and stored vehicles varies widely, so get the terms in writing.
This article is an independent educational comparison and is not sponsored or endorsed by Toyota, Subaru or any insurer named. The editorial claims are based on the listed published data; rates, eligibility, discounts and company financial ratings may change. Check current policy documents and official sources before purchasing.
Toyota, GR86, GR Supra, GR Corolla, Toyota 86, Subaru BRZ, Mazda MX-5 Miata, and other names used here are trademarks of their respective owners.