
Temporary Car Insurance in Pennsylvania
Whether you are home from college in State College, borrowing a car in Pittsburgh for a month, or storing a car through a Philadelphia winter, getting temporary car insurance in Pennsylvania starts with one fact: insurers in the state do not sell policies shorter than six months. You can still be covered for just the weeks you need, but PennDOT's rules on plates and coverage lapses are strict, so the way you end coverage matters as much as the way you start it.
That makes Pennsylvania different from states where you can simply cancel and walk away. Here, a canceled policy starts a 30-day clock on your license plate, and missing it can cost more than the coverage itself.
This guide explains Pennsylvania's insurance requirements, PennDOT's 30-day plate-return rule and three-month suspensions, the $500 civil penalty, every short-term option with 2026 Pennsylvania prices, the tort and stacking choices that change your price, and a step-by-step plan. Every figure is sourced and dated, and hypothetical examples are labeled.
- No policies shorter than six months. Pennsylvanians use a standard policy canceled early, pay-per-mile, non-owner, rental, or a household member's policy.
- Return your plate and registration card within 30 days of canceling. Otherwise, PennDOT suspends the registration for three months.
- A lapse can be fixed with a $500 civil penalty, once in any 12-month period, instead of the suspension.
- Cheapest Pennsylvania coverage: Plymouth Rock averaged $46 a month for liability-only, and State Farm $83 for full coverage, in 2026 real-quote data.
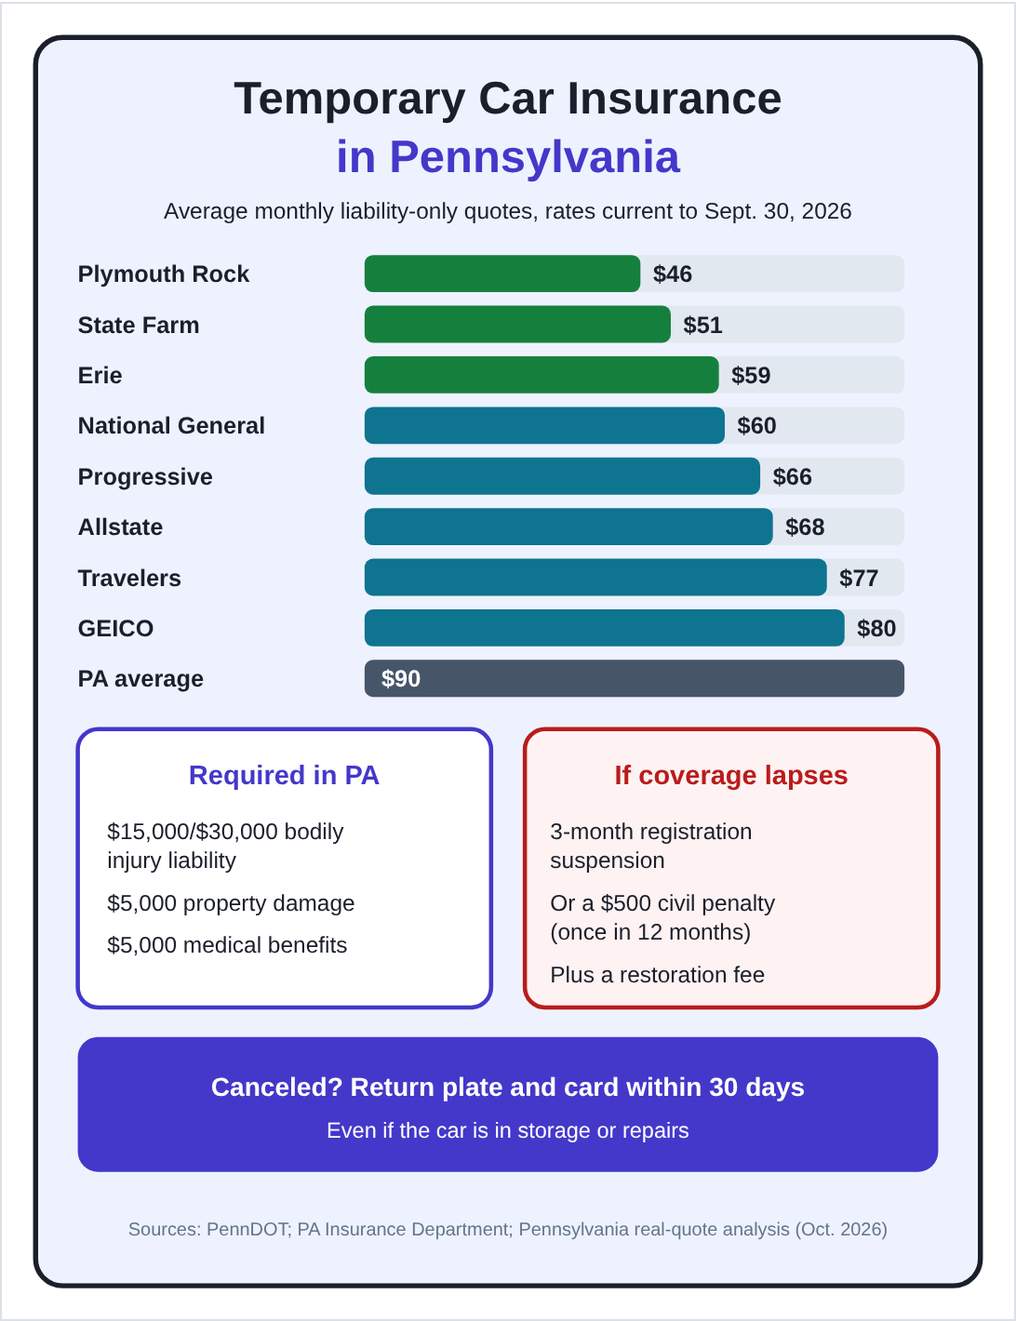
Average monthly liability-only quotes in Pennsylvania from a real-quote analysis updated November 4, 2026 (rates current to September 30, 2026), plus required coverage and PennDOT's lapse rules. Averages, not quotes.
BEFORE YOU BUYDecide whether the coverage is for a car registered to you in Pennsylvania, a borrowed car, or a rental. If it is your registered car, plan now how you will return the plate when you cancel.
Does temporary car insurance exist in Pennsylvania?
No, not as a policy term. A Pennsylvania quote analysis updated November 4, 2026, says plainly that "Pennsylvania car insurance companies don't offer policies for less than six months." It lists the realistic alternatives: canceling a standard policy early, pay-per-mile insurance, a non-owner policy, rental coverage, joining another person's policy, and stored-vehicle coverage. It names State Farm, Progressive, and GEICO among insurers offering cancelable policies.
Weekly-payment and pay-as-you-go programs sold in some other states, such as Insurify Car, do not list Pennsylvania in the 2026 sources we reviewed.
Short-term car insurance options in Pennsylvania
Option | How it works | Covers your own car? | Best for |
|---|---|---|---|
Standard policy, canceled early | Buy a six-month policy and cancel when done | Yes, with collision and comprehensive | Owners of Pennsylvania-registered cars |
Pay-per-mile insurance | Monthly base rate plus a per-mile charge | Yes, with full coverage | Cars that will barely be driven |
Non-owner insurance | Liability coverage when you drive cars you do not own | No | People who borrow or rent cars |
Rental car coverage | Bought for the rental period | Yes, with a damage waiver | Short rentals |
Added to someone else's policy | The owner adds you as a driver | Depends on their policy | Students home for summer, family stays |
Stored-vehicle coverage | Comprehensive-only while the car is off the road | Theft and damage only | Cars stored for months |
Pennsylvania car insurance requirements
Every registered vehicle in Pennsylvania, including cars, vans, motorcycles, RVs, trucks, and buses, must carry this minimum coverage, according to PennDOT and the Pennsylvania Insurance Department (PID):
Pennsylvania required coverage
Coverage | Minimum |
|---|---|
Bodily injury liability, one person | $15,000 |
Bodily injury liability, more than one person | $30,000 |
Property damage liability | $5,000 |
First-party medical benefits | $5,000 |
Uninsured/underinsured motorist | Must be offered; you may decline it in writing |
PennDOT, Insurance Overview, and Pennsylvania Insurance Department (accessed October 2026). Collision and comprehensive are optional by law but usually required by lenders.
Medical benefits pay your own medical bills after a crash, regardless of who caused it. Liability pays for injuries and damage you cause to others. Pennsylvania's minimums are low by national standards, and about 11.0% of Pennsylvania drivers were uninsured in 2023, according to the Insurance Research Council, so higher limits and uninsured motorist coverage are worth pricing even on a short-term policy.
Tort and stacking: two choices that change your price
Pennsylvania gives drivers two choices most states do not. When you buy a policy, you choose a tort option. PID says limited tort "offers you significant savings on your premium," but you generally cannot recover damages for pain and suffering unless an exception applies, such as a serious injury. Full tort keeps unrestricted rights to sue, and if you do not choose limited tort, you are treated as having chosen full tort.
Stacking lets you add together the uninsured and underinsured motorist limits for each vehicle on your policy. PID says stacked coverage applies unless you reject it, and "you will pay less in premiums if you reject stacked coverage." For a single car on a short-term policy, stacking matters less, but the tort choice can change the price of any policy.
Tort and stacking choices in Pennsylvania
Choice | Effect on price | What you give up |
|---|---|---|
Limited tort | Lower, per PID | Most claims for pain and suffering unless an exception applies |
Full tort | Higher | Nothing; keeps full rights to sue |
Reject stacked UM/UIM | Lower, per PID | Combined uninsured motorist limits across your vehicles |
Keep stacked UM/UIM | Higher | Nothing; matters most with several cars |
PennDOT's lapse rules: the key to ending coverage
Pennsylvania is strict about gaps. Insurers must notify PennDOT when you cancel a policy. If required coverage lapses, PennDOT suspends the vehicle's registration for three months under 75 Pa.C.S. § 1786. To serve the suspension, you must surrender the plate and registration card, and you must pay a restoration fee and show proof of insurance before the registration is restored.
What happens when Pennsylvania coverage lapses
Situation | Result |
|---|---|
Plate and card returned to PennDOT within 30 days of cancellation | No suspension |
Lapse of 30 days or less, and you prove the car was not driven | No suspension |
Lapse longer than 30 days, plate not returned in time | Three-month registration suspension |
Civil penalty instead of suspension | $500 plus restoration fee and proof of insurance; once in any 12 months |
Car driven while uninsured | $300 minimum fine and a three-month suspension of your driving privilege |
PennDOT, Insurance Overview; 75 Pa.C.S. § 1786 (accessed October 2026). PennDOT lists restoration fees on Form MV-70S; a Pennsylvania quote analysis cites reinstatement fees of $119 for registration and $94 for a license.
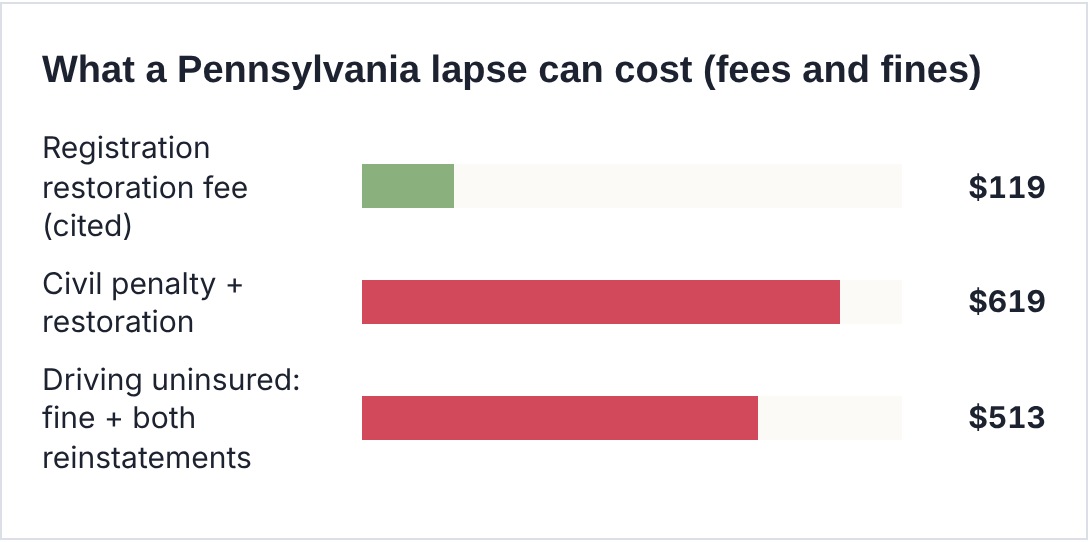
Our calculation from figures cited in a Pennsylvania quote analysis ($119 registration and $94 license reinstatement) and PennDOT/§ 1786 ($500 civil penalty; $300 minimum fine). Excludes the cost of new coverage and any court costs.
There is one important detail for short-term buyers: PennDOT says the plate and card must be returned even if the vehicle is in repairs or storage and not being driven. Mail them to Bureau of Motor Vehicles, Return Tag Unit, P.O. Box 68597, Harrisburg, PA 17106-8597, so they arrive within 30 days of cancellation.
Pennsylvania also does not require insurers to offer a grace period for premium payments, according to PID. If a payment is missed, the insurer can cancel the policy, and the lapse rules then apply.
PRO TIP #1Mail the plate the same week you cancel. Use a trackable method and keep the receipt. If PennDOT receives the plate and card within 30 days of cancellation, you avoid the three-month suspension, even if the car will sit unused.
PennDOT needs proof when you buy
Insurers must tell PennDOT when you cancel, but they are not required to notify PennDOT when you buy a new policy. If PennDOT sends you a proof letter, you must respond, or the registration can be suspended.
PennDOT accepts an insurance ID card, a declarations page from a new or renewed policy, a binder valid for 30 or 60 days signed by a licensed agent, an application to the Pennsylvania Assigned Risk Plan, or a signed carrier letter. Keep your ID card in the vehicle at all times.
Your temporary car insurance options in Pennsylvania
1. A standard policy canceled early
This is the most widely available route and the only one that reliably includes full coverage. You buy a six-month policy, use it as long as you need, return the plate, and cancel. Most insurers refund unused premium. With a pro rata refund, you get all of it back; with a short-rate refund, an insurer may keep 10% to 15% of the unearned premium, according to an analysis updated August 31, 2026.
Hypothetical: one month on a Pennsylvania liability-only policy
Refund method | Six-month premium | Premium used (1 month) | Penalty | Cost for one month |
|---|---|---|---|---|
Pro rata, no fee | $276 | $46 | $0 | $46 |
Short-rate, 10% of unearned | $276 | $46 | $23 | $69 |
Short-rate, 15% of unearned | $276 | $46 | $34.50 | $80.50 |
Hypothetical: our calculation, using Plymouth Rock's $46 monthly liability-only average in a Pennsylvania real-quote analysis (rates current to September 30, 2026) × 6 = $276. Unearned premium after one month: $230. Your quote and refund terms will differ.
Pennsylvania has no law setting a minimum or maximum down payment, so each insurer's payment plan decides what you pay to start. Ask for the amount due today and the refund method before you buy.
2. Pay-per-mile insurance
If your car will mostly sit, pay-per-mile insurance charges a monthly base rate plus a few cents per mile. Pennsylvania has more choices than some states: Nationwide SmartMiles does not exclude Pennsylvania on its availability list, and an November 2026 review lists Allstate Milewise in 22 states, including Pennsylvania. USAA's pay-per-mile program does not list Pennsylvania. Check each company's availability for your ZIP code.
3. Non-owner insurance
If you do not own a car but will drive borrowed or rented ones, a non-owner policy gives you liability coverage. The Pennsylvania analysis says non-owner policies typically cost less than insuring a car you own. A national analysis put non-owner coverage at $29 to $74 a month. It does not pay for damage to the car you drive.
4. Rental car coverage
The Pennsylvania analysis notes that rental companies provide minimum liability coverage, and that loss-of-use or administrative fees may apply if a rental is damaged or stolen. One national analysis put rental car insurance at $9 to $30 a day, and a June 2026 consumer report said counter coverage often costs $30 to $60 a day. Check your own policy and card benefits first; most cards offer only secondary coverage and usually exclude liability.
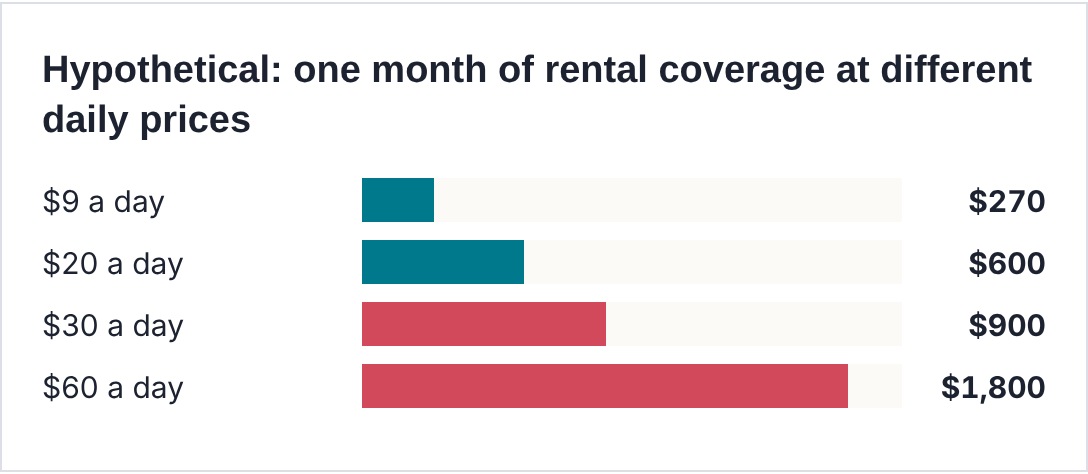
Our calculation: daily price × 30. Daily ranges from a national analysis (September 30, 2026) and a June 23, 2026, consumer report.
5. Being added to someone else's policy
This is often the best answer for college students home for the summer or relatives staying a few weeks. Adding a driver to an existing policy avoids buying a new one, though it may raise the owner's premium. Occasional drivers with permission may already be covered, but rules vary, so the owner should check with the insurer first.
6. Stored-vehicle coverage
If you are storing a car for months, the Pennsylvania analysis lists stored-vehicle coverage as an option. It protects against theft, fire, and other damage while the car sits, but it does not include liability, so you cannot legally drive. Remember PennDOT's rule: if you cancel the liability coverage, return the plate and registration card within 30 days, even though the car is in storage.
7. Insurers that skip credit checks
Two insurers that sell in Pennsylvania say they do not use credit in pricing: CURE, which serves Michigan, New Jersey, and Pennsylvania, and Glacier, which a 2026 analysis lists in Pennsylvania and Delaware. They can help drivers whose credit would raise a standard quote, but compare their prices with the cheapest mainstream companies.
8. The Pennsylvania Assigned Risk Plan
Drivers who cannot get coverage elsewhere can apply through the Pennsylvania Assigned Risk Plan. PennDOT even accepts a signed application to the plan as proof of insurance while the policy is being placed.
How much does short-term car insurance cost in Pennsylvania?
Pennsylvania is a relatively affordable state. In real-quote data, its averages were $90 a month for liability-only and $162 for full coverage, compared with $99 and $187 nationally. Prices are steady too: on April 22, 2026, PID said approved private passenger auto rate filings averaged a 0.2% decrease in 2025 and a 0.5% decrease so far in 2026, and that more than 200 insurers compete in the state.
Two 2026 analyses show the cheapest companies. Study A is a rate study updated August 25, 2026, using a 40-year-old driver. Study B is a real-quote analysis with rates current to September 30, 2026. Compare each only with itself.
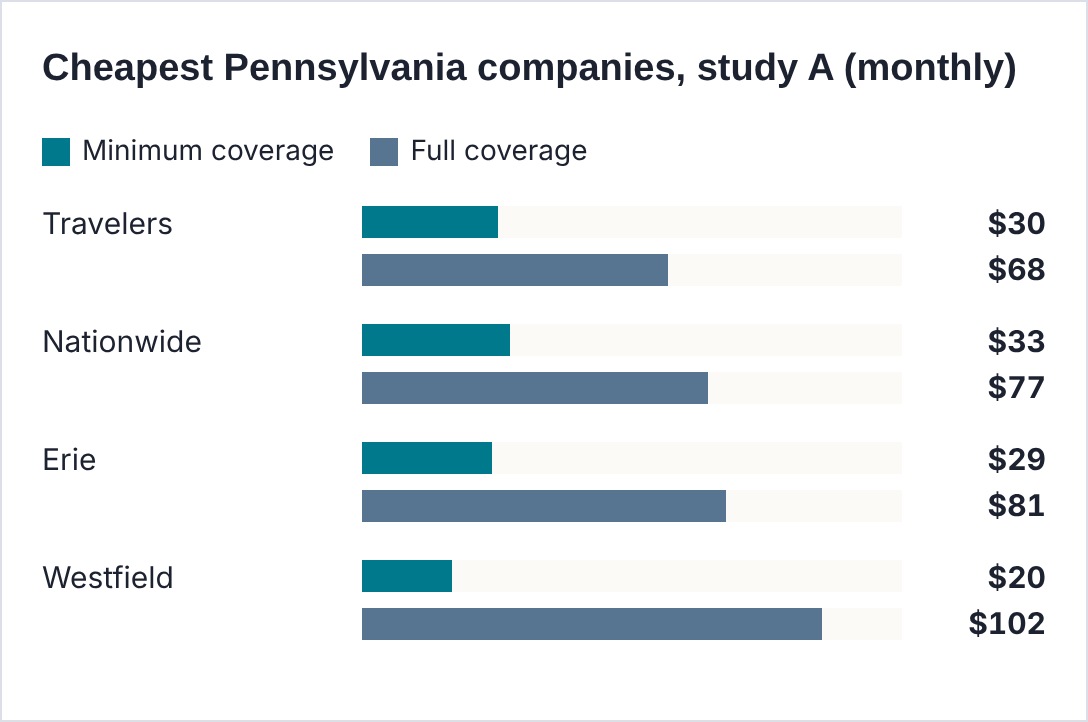
Study A: Pennsylvania rate study updated August 25, 2026; 40-year-old driver; full coverage at 100/300/100. Study full-coverage average: $123.
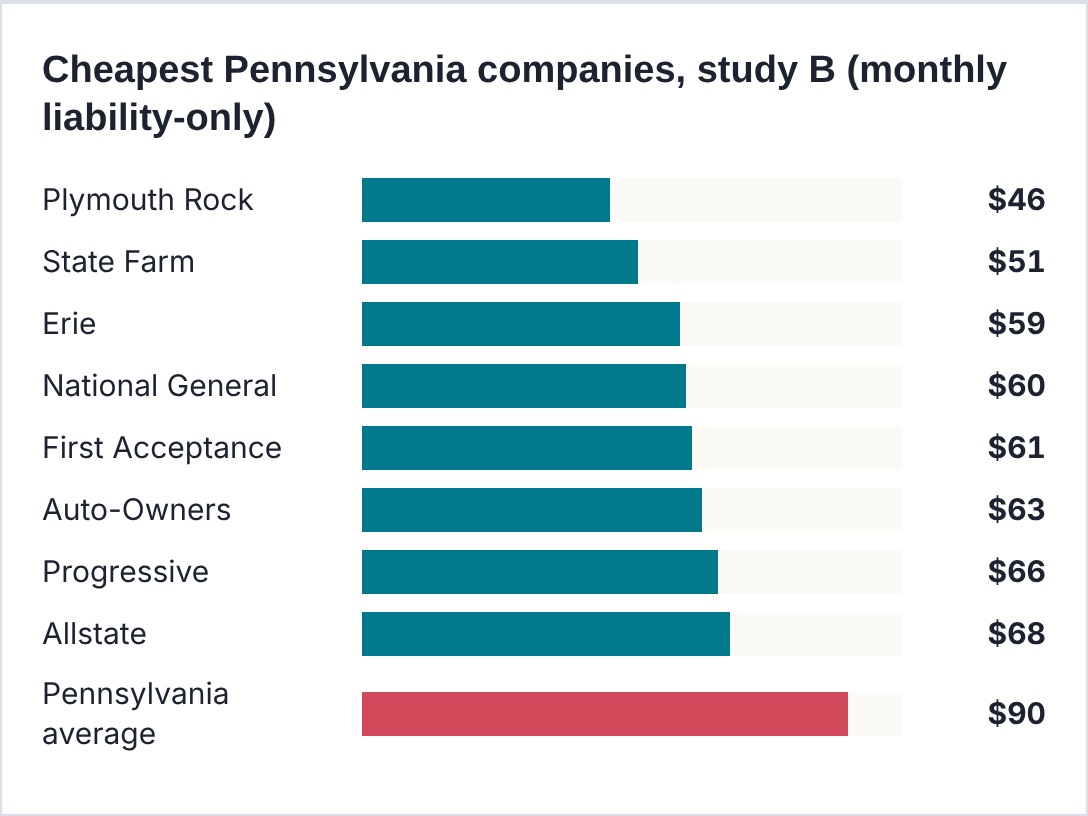
Study B: Pennsylvania real-quote analysis updated October 17, 2026; rates current to September 30, 2026. State Farm also had the cheapest full coverage at $83.
Hypothetical: monthly savings vs. the Pennsylvania average
Coverage | Average (monthly) | Cheapest company (monthly) | Savings per month (our calculation) |
|---|---|---|---|
Study A: full coverage | $123 | $68 (Travelers) | $55 |
Study B: liability-only | $90 | $46 (Plymouth Rock) | $44 |
Study B: full coverage | $162 | $83 (State Farm) | $79 |
Our calculation within each study. Averages, not quotes.
Discounts that help short-term buyers
One Pennsylvania discount is required by law: PID says insurers must give drivers 55 and older at least a 5% discount per vehicle after completing an approved driver improvement course. Limited tort and rejecting stacking also lower premiums, per PID, though each has trade-offs.
Buying a car in Pennsylvania: getting covered fast
If you already have a policy, call your insurer before you drive away. Many insurers give a grace period of about 7 to 30 days to add a newly bought car, according to a June 2026 rate study, though some give only a few days, and some give none. If you need a new policy, bring proof such as an ID card, declarations page, or binder, since PennDOT accepts each.
A vehicle-model rate study found the lowest average full-coverage premiums in Pennsylvania for the Honda HR-V, Honda CR-V, Volkswagen Tiguan, Ford Ranger, and Mini Cooper Countryman JCW, with the Subaru Outback tied for fifth, all within $47 of each other over six months.
Temporary coverage for special situations in Pennsylvania
College students. Pennsylvania has many college towns. A student bringing a car to campus for a semester usually does best on a parent's policy. A student who borrows or rents may want non-owner coverage.
Teens. The Pennsylvania analysis found State Farm cheapest for teens at $93 a month for liability-only and $157 for full coverage. In study A, the cheapest full coverage on a family policy was $211 at 18 and $132 at 25 (Travelers).
Visitors. If you are visiting with your own car, your home-state policy generally travels with you; confirm with your insurer. Without a car, use the owner's policy, rental coverage, or a non-owner policy.
New residents. Once you register a car in Pennsylvania, it needs Pennsylvania-compliant coverage, and PennDOT may ask for proof. Line up a policy before you register.
Drivers with a DUI or SR-22. The Pennsylvania analysis put DUI drivers at $145 a month and SR-22 drivers at $152 on average.
Best temporary option by Pennsylvania situation
Your situation | Best option | Why |
|---|---|---|
College student home for summer | Be added to a parent's policy | No new policy needed |
Borrowing a car while visiting | Owner's policy or a non-owner policy | No vehicle coverage needed |
Owning a PA car for a few months | Standard policy canceled early | Return the plate within 30 days of canceling |
Car will barely be driven | Pay-per-mile insurance | Low mileage keeps the bill down |
Storing a car for months | Stored-vehicle coverage, then return the plate if you drop liability | Avoids the three-month suspension |
Turned down by insurers | Pennsylvania Assigned Risk Plan | Legal assigned-risk coverage |
Keep, cancel, or store? The math for a parked car
Many Pennsylvanians looking for temporary coverage really have the opposite problem: a car that will sit for a few months. The cheapest-looking move, canceling outright, can be the most expensive if the plate is not returned in time. The table below compares three paths for a car parked for three months.
Hypothetical: a car parked for three months in Pennsylvania
Path | What you do | Approximate cost (our calculation) |
|---|---|---|
Keep liability coverage | Leave a low-cost liability policy in force | $138 (3 × $46) |
Cancel and return the plate | Mail plate and card within 30 days; re-register later | No premium; fees to reinstate the plate may apply |
Cancel and keep the plate | Miss the 30-day deadline | Three-month suspension, or $500 plus a restoration fee |
Hypothetical; our calculation using Plymouth Rock's $46 monthly liability-only average in study B. Your quote will differ, and some insurers set minimum premiums or fees.
For a short layup, keeping inexpensive liability coverage is often simpler than handling the plate. For a long layup, such as a winter or a military deployment, canceling and returning the plate, or switching to stored-vehicle coverage and returning the plate, can make more sense. Ask your insurer which choice keeps your continuous-coverage history intact, since a gap can raise future quotes.
Selling a car or moving out of Pennsylvania
In Pennsylvania, the license plate belongs to the owner, not the vehicle. When you sell a car, the seller removes the plate, so you can move it to another vehicle or return it. If you are not replacing the car, return the plate when you cancel the coverage, so PennDOT receives it within the 30-day window.
If you are moving to another state, keep your Pennsylvania coverage until the car is registered and insured in the new state. Then cancel the Pennsylvania policy and return the plate and registration card to PennDOT. Ending coverage first, while the Pennsylvania registration is still active, is what triggers the lapse rules.
How Pennsylvania compares with other states
Ending coverage: Pennsylvania vs. other states
State | What happens when coverage ends | Cost |
|---|---|---|
Pennsylvania | Return plate and card within 30 days, or a three-month registration suspension | $500 civil penalty option, once in 12 months |
New York | Surrender plates before coverage ends, or suspension or daily penalties | $8 to $12 a day for up to 90 days |
Florida | Insurer reports within 10 days; license and registration can be suspended | $150, $250, or $500 to reinstate |
Texas | No automatic lapse fee; driving uninsured brings fines | $175 to $1,000 if ticketed |
PennDOT; New York DMV; Florida Statutes § 324.0221; Texas Transportation Code § 601.191. Summarized.
How to get temporary car insurance in Pennsylvania, step by step
- Decide what you need to cover: your own car, a borrowed car, or a rental.
- Get quotes from Pennsylvania's cheapest companies, such as Plymouth Rock, State Farm, Erie, Travelers, and Progressive.
- Choose your tort option and stacking knowingly, and match them on every quote.
- Ask about the refund method and any cancellation fee.
- Compare pay-per-mile if the car will barely be driven.
- Keep your ID card in the car, and answer any PennDOT proof letter.
- Set payment dates after payday, since there is no required grace period.
- When you are done, cancel and return the plate and card so PennDOT receives them within 30 days.
Questions to ask a Pennsylvania insurer
- Is the refund pro rata or short-rate, and is there a cancellation fee?
- How much does limited tort save on this quote?
- What does rejecting stacked uninsured motorist coverage save?
- Do you offer stored-vehicle or pay-per-mile coverage?
- Do you offer the 55-and-older driver improvement course discount?
Pros and cons of temporary coverage in Pennsylvania
Pros | Cons |
|---|---|
Relatively low prices; liability from $46 a month | No policies shorter than six months |
Pay-per-mile options are available | Plates must be returned within 30 days of canceling |
Tort and stacking choices can lower the price | A lapse brings a three-month suspension or $500 penalty |
Rates fell slightly in 2025 and 2026 | No required grace period for missed payments |
Price-limited tort before you decide. PID says it offers significant savings, which matters on a short policy. But understand the trade-off first: you generally give up suing for pain and suffering unless an exception applies. If the savings are small on your quote, full tort may be worth keeping.
Common mistakes to avoid
Canceling without returning the plate. PennDOT must receive it within 30 days.
Assuming storage exempts you. The plate rule applies even if the car is in storage or repairs.
Ignoring PennDOT proof letters. Failing to respond leads to suspension.
Missing a payment. Pennsylvania insurers do not have to offer a grace period.
Comparing quotes with different tort choices. A limited tort quote and a full tort quote are not the same product, so match the choice before comparing prices.
Buying only the minimum limits without thinking. The $5,000 property damage minimum may not cover even a minor crash with a newer car, so price higher limits too.
Pennsylvania temporary car insurance at a glance
This illustrated summary pulls together the rules and options covered above.
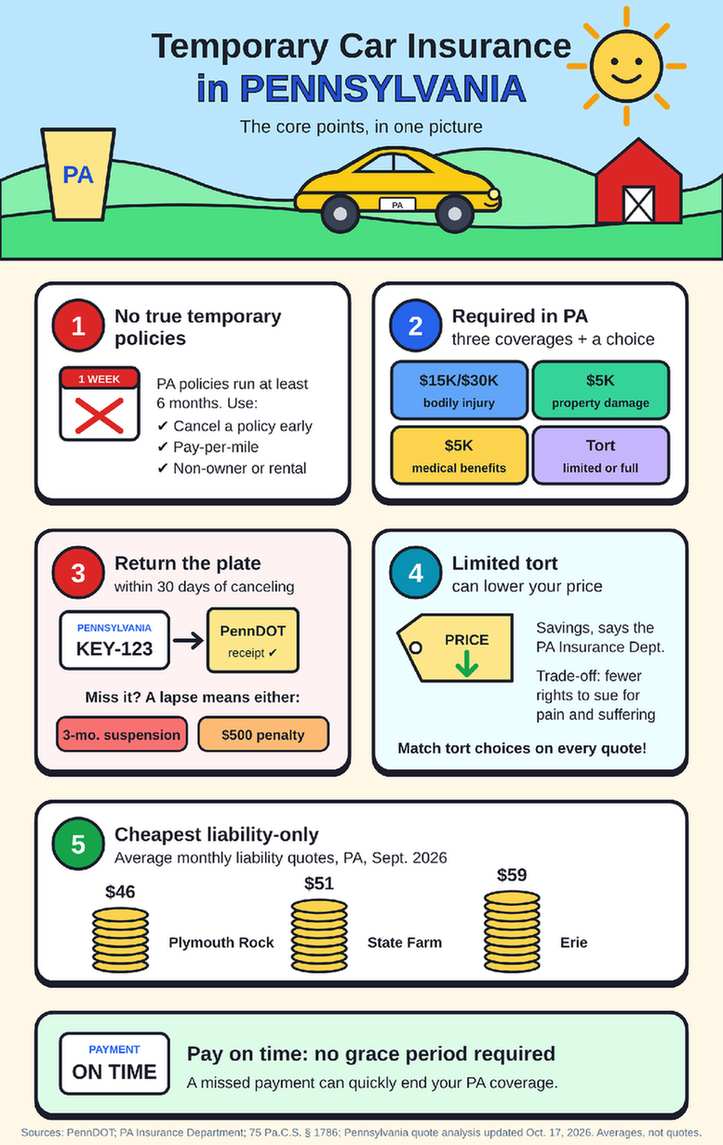
Pennsylvania temporary car insurance at a glance. Sources: PennDOT; Pennsylvania Insurance Department; 75 Pa.C.S. § 1786; Pennsylvania quote analysis updated November 5, 2026. Averages, not quotes.
Frequently asked questions
Can you get temporary car insurance in Pennsylvania?
Not as a short policy term. Pennsylvania insurers do not sell policies shorter than six months. You can cancel a standard policy early, use pay-per-mile, non-owner, or rental coverage, join a household member's policy, or keep stored-vehicle coverage on a car you are not driving.
What insurance is required in Pennsylvania?
Every registered vehicle needs $15,000/$30,000 bodily injury liability, $5,000 property damage liability, and $5,000 of first-party medical benefits. Insurers must offer uninsured and underinsured motorist coverage, which you can decline in writing. Lenders usually require collision and comprehensive, and higher limits are worth pricing given the state's uninsured drivers.
What happens if I cancel my car insurance in Pennsylvania?
Your insurer tells PennDOT. Return your plate and registration card so PennDOT receives them within 30 days of cancellation. If you do not, PennDOT suspends the registration for three months, unless you prove a lapse of 30 days or less with no driving.
What is the $500 civil penalty in Pennsylvania?
Instead of serving a three-month registration suspension for a lapse, you can pay a $500 civil penalty, plus a restoration fee and proof of current insurance, to keep the registration active. PennDOT allows this option no more than once in any 12-month period.
Do I need to return my plate if my car is in storage?
Yes, if you drop the required coverage. PennDOT says the plate and registration card must be surrendered even if the vehicle is in repairs or storage and not being driven. Keeping liability coverage in force, or stored-vehicle coverage plus returning the plate, avoids a suspension.
Is pay-per-mile insurance available in Pennsylvania?
Yes, from some companies. Nationwide SmartMiles does not exclude Pennsylvania, and a 2026 review lists Allstate Milewise in 22 states, including Pennsylvania. USAA's program does not list it. Check availability for your ZIP code before comparing prices, and confirm the plan meets Pennsylvania's minimum coverage.
Does limited tort save money in Pennsylvania?
Yes. The Pennsylvania Insurance Department says limited tort offers significant premium savings. In exchange, you generally cannot sue for pain and suffering unless an exception applies, such as a serious injury. Ask each insurer to quote both options side by side, so you can see the actual dollar difference before you sign.
What is the cheapest car insurance in Pennsylvania?
In real-quote data current to September 30, 2026, Plymouth Rock was cheapest for liability-only at $46 a month, and State Farm for full coverage at $83. In a separate rate study, Travelers led full coverage at $68, and Westfield minimum coverage at $20.
The final word on temporary car insurance in Pennsylvania
For most Pennsylvanians who need a few weeks or months of coverage on their own car, a standard six-month policy from a low-cost insurer, canceled with a pro rata refund, is the best temporary solution. Use pay-per-mile if the car will barely move, non-owner or rental coverage if you do not own the car, and a parent's policy for students home on break. Above all, return the plate and registration card to PennDOT within 30 days of canceling.
NEXT STEPWrite down the dates you need coverage and the car you will drive. Get three quotes with matching tort and stacking choices, ask about refund terms, keep your ID card in the car, and plan to mail your plate as soon as you cancel.
Prices, availability, cancellation terms, and state rules can change. The figures in this article are averages, published rules, and hypothetical calculations, not quotes. This article is for information only and is not legal or financial advice. The publisher is not an insurance company or a licensed insurance agency.
The bottom line on temporary car insurance in Pennsylvania: policies run at least six months, but a cancelable low-cost policy, pay-per-mile, non-owner, or rental coverage can cover a short need, as long as you follow PennDOT's 30-day plate rule.
Sources
- PennDOT, Insurance Overview (accessed October 2026).
- 75 Pa.C.S. § 1786, Required financial responsibility (accessed October 2026).
- Pennsylvania Insurance Department, Auto Insurance Guide and auto rate stabilization announcement (April 22, 2026).
- Pennsylvania Assigned Risk Plan (AIPSO) (accessed October 2026).
- Insurify, Temporary Car Insurance in Pennsylvania (updated October 17, 2026) and Pennsylvania Car Insurance (rates current to September 30, 2026).
- MoneyGeek, Cheapest Car Insurance in Pennsylvania (updated August 25, 2026) and Which Insurance Companies Don't Use Credit Scores? (updated October 1, 2026).
- CarInsurance.com, Cheapest Cars to Insure in Pennsylvania and New Car Grace Period (updated June 26, 2026).
- Insurance Information Institute, Uninsured Motorists, citing the Insurance Research Council.
- Nationwide, SmartMiles, Allstate, Milewise, and USAA, usage-based insurance (accessed October 2026).
- CURE Auto Insurance, company information (accessed October 2026).
- MoneyGeek, Car Insurance Refund (August 31, 2026).
- Insurify, One-Week Car Insurance (updated September 30, 2026) and First Alert 4, Understanding Rental Car Insurance (June 23, 2026).
- New York DMV, Auto Liability Insurance, Florida Statutes § 324.0221, and Texas Transportation Code, Chapter 601.