
Temporary Car Insurance in Illinois
Whether you are borrowing a car for a summer in Chicago, driving home from college in Champaign, or covering a car you plan to sell next month, finding temporary car insurance in Illinois is easier than in most states. True one-week policies are rare, but Illinois has weekly and pay-as-you-go programs that many states do not, and a state law that guarantees a full pro rata refund when you cancel a car insurance policy early.
This guide covers Illinois insurance requirements, the Secretary of State's electronic insurance checks, the fines for driving uninsured, every short-term option with 2026 Illinois prices, and a step-by-step plan. Every figure is sourced and dated, and hypothetical examples are labeled.
- Weekly coverage exists in Illinois. A 2026 real-quote analysis lists weekly liability coverage averaging $18 a week, plus pay-as-you-go and pay-per-mile options.
- Canceling early is low-risk. Illinois law requires insurers to refund unearned auto premium pro rata within 30 days, and bars short-rate penalty tables.
- The state checks your coverage electronically. An uninsured registered car can lead to a registration suspension and a $100 reinstatement fee.
- Cheapest Illinois coverage: Auto-Owners averaged $41 a month for liability-only and $74 for full coverage in 2026 real-quote data.
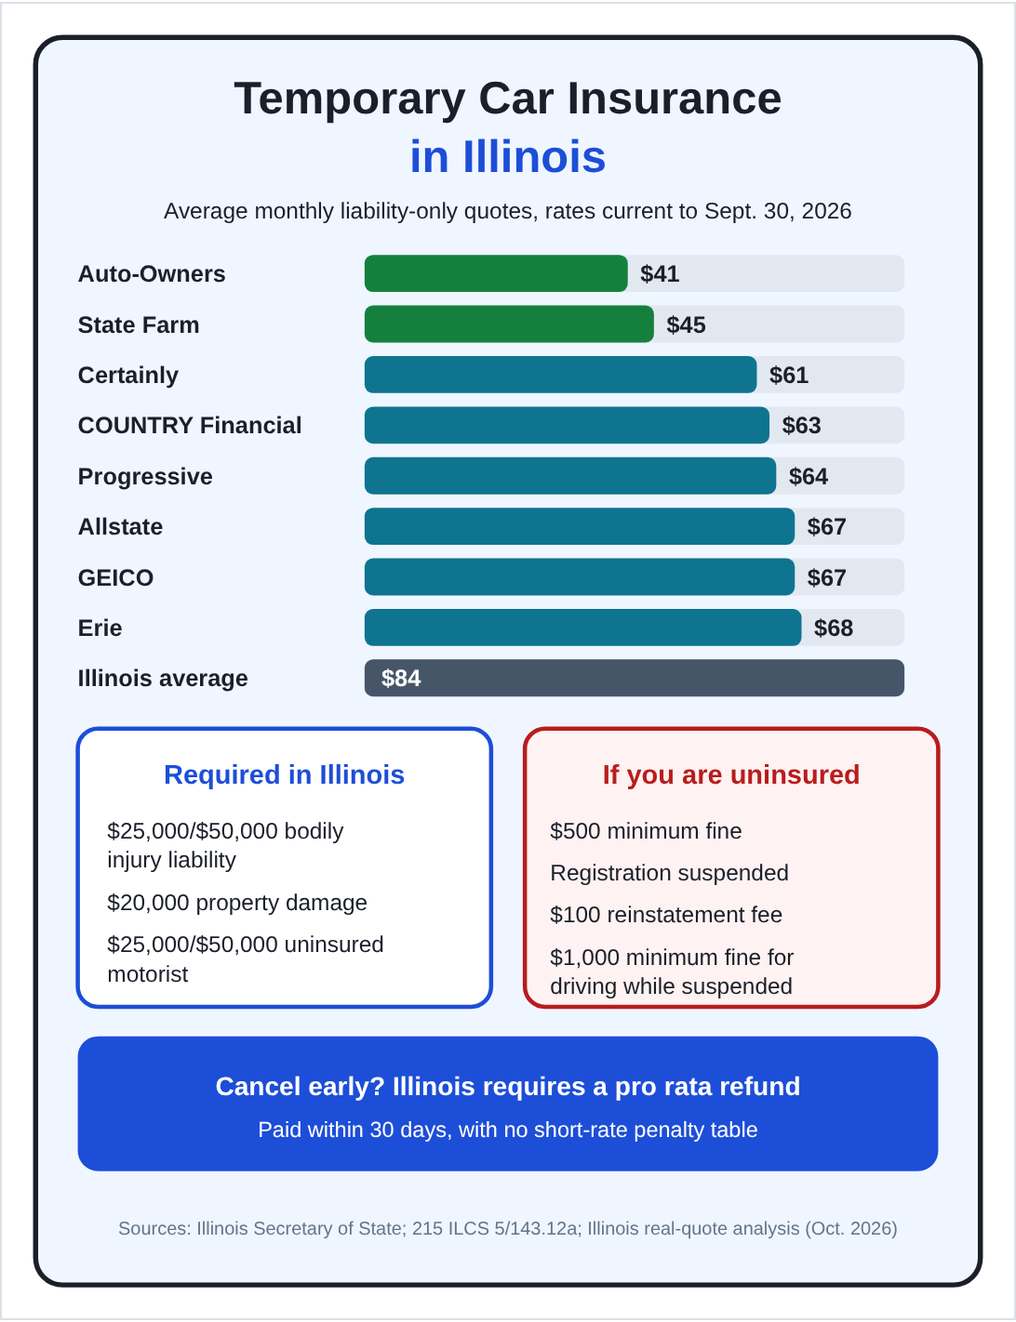
Average monthly liability-only quotes in Illinois from a real-quote analysis updated November 4, 2026 (rates current to September 30, 2026), plus required coverage, penalties, and the state's refund rule. Averages, not quotes.
Does temporary car insurance exist in Illinois?
Mostly no, but Illinois has more flexible choices than most states. An Illinois quote analysis updated November 4, 2026, says temporary car insurance is hard to find because traditional policies usually run six or 12 months. It then lists the options Illinois drivers do have: weekly coverage in seven-day increments through Insurify Car, monthly-billed policies, non-owner insurance, rental coverage, same-day policies, and pay-as-you-go or pay-per-mile coverage.
The same analysis lists average short-term prices in Illinois of $67 a month for Allstate, $102 for Insurify Car, and $115 for Hugo, with short-term coverage generally running $98 to $130 a month. Weekly liability coverage through Insurify Car averaged $18 a week.
Short-term car insurance options in Illinois
Option | How it works | Covers your own car? | Best for |
|---|---|---|---|
Weekly coverage (Insurify Car) | Liability-only coverage bought in seven-day increments | Liability only | A few weeks of driving |
Pay-as-you-go (Hugo) | Prepaid coverage you can turn off and on | Varies by plan | Irregular drivers |
Standard policy, canceled early | Buy a six-month policy and cancel; Illinois requires a pro rata refund | Yes, with full coverage | Owners who need collision and comprehensive |
Pay-per-mile insurance | Monthly base rate plus a per-mile charge | Yes, with full coverage | Cars that barely move |
Non-owner insurance | Liability when you drive cars you do not own | No | People who borrow or rent |
Rental car coverage | Bought for the rental period | Yes, with a damage waiver | Short rentals |
Illinois quote analysis updated November 4, 2026. Availability and plan details change; confirm for your ZIP code.
Illinois car insurance requirements
Every vehicle registered in Illinois must carry at least the following coverage, according to the Illinois Secretary of State:
Illinois required coverage
Coverage | Minimum |
|---|---|
Bodily injury liability, one person | $25,000 |
Bodily injury liability, more than one person | $50,000 |
Property damage liability | $20,000 |
Uninsured motorist bodily injury | $25,000 per person / $50,000 per crash |
Illinois Secretary of State, Mandatory Insurance brochure (VSD 361.17); Illinois quote analysis (October 2026). Collision, comprehensive, and medical payments coverage are optional under state law, though lenders usually require collision and comprehensive.
Uninsured motorist coverage matters in Illinois. About 15.2% of Illinois drivers were uninsured in 2023, the 17th-highest rate among the states, according to the Insurance Research Council. Even on a short-term policy, consider limits above the minimum: the $20,000 property damage minimum may not pay for a crash with a newer car.
How Illinois checks your insurance
Illinois does not ask you to turn in your license plates when you cancel a policy, but it does check coverage electronically. The Illinois Insurance Verification System launched in July 2021 and checks insurance on registered vehicles with data from insurers. A 2021 report said the system checks owners' insurance status at random at least twice a year, replacing the old practice of mailing proof-of-insurance requests to randomly chosen owners.
According to the Secretary of State, if the first check finds no qualifying policy, the vehicle is checked again after 30 days. If the second check also fails, the owner receives a suspension letter and has 30 days to prove coverage existed on the date of the first check. Otherwise, the registration is suspended, and restoring it takes proof of insurance and a $100 fee.
This is the key rule for short-term buyers: if your car stays registered, the state expects it to stay insured. Dropping coverage on a parked car can still trigger a letter, so check with the Secretary of State before you let coverage end on a registered vehicle.
Penalties for driving uninsured in Illinois
Violation | Penalty |
|---|---|
Driving an uninsured vehicle | Minimum $500 fine |
First offense, registration | Suspended until you pay $100 and show proof of insurance |
Repeat offense, registration | Four-month suspension, $100 fee, and proof of insurance |
Driving while registration is suspended for no insurance | Minimum $1,000 fine |
Court supervision or third conviction | SR-22 proof for three years, or a license suspension |
Illinois Secretary of State, Mandatory Insurance brochure (VSD 361.17, September 2023).
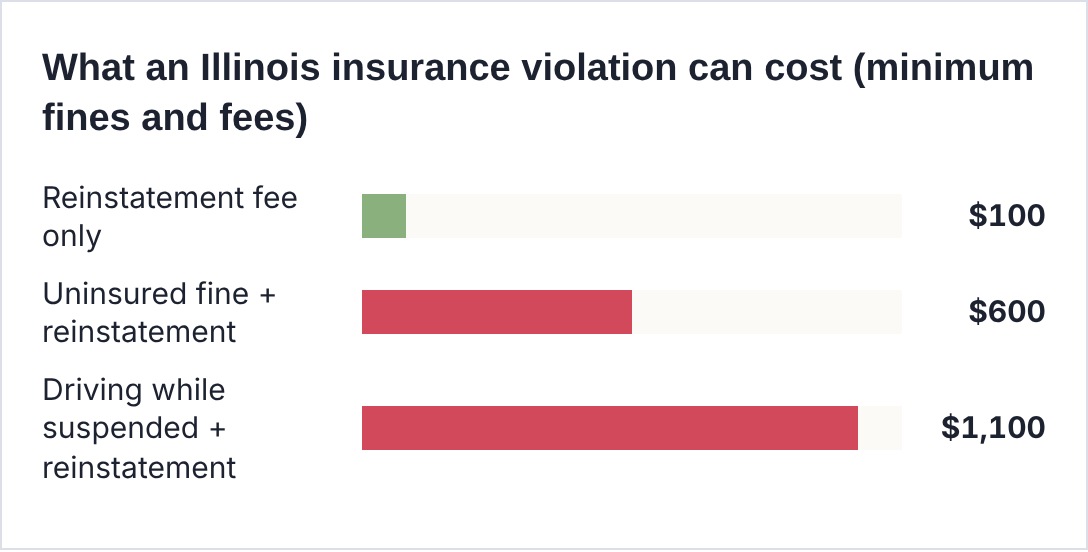
Our calculation from the Illinois Secretary of State's minimum fines and $100 reinstatement fee. Excludes court costs, higher fines, and the cost of new coverage.
Illinois accepts electronic proof of insurance on your phone, according to an Illinois law firm's 2026 guide, as well as an ID card, a declarations page, or a binder from your agent. Carry proof every time you drive, since an officer can cite you if you cannot show it.
PRO TIP #1Keep coverage active until the car is sold or off the road for good. Because Illinois checks registered vehicles electronically, a short gap can bring a suspension letter. If the car will sit, price a cheap liability policy or pay-per-mile coverage before you cancel.
Illinois' refund law makes canceling early safer
Illinois has one of the strongest consumer protections for short-term buyers. Under 215 ILCS 5/143.12a, when an automobile policy is canceled by either the insurer or the policyholder, the insurer must refund the unearned premium pro rata to the date of cancellation, and it may not use a short-rate table. The refund must be paid within 30 days.
In many states, insurers can keep 10% or more of the unearned premium when you cancel early. In Illinois, the statute requires pro rata, so a standard six-month policy canceled after a month works much like a one-month policy. Ask whether any separate fees apply, and pay by the month if you can, so less money is tied up while you wait for the refund.
Hypothetical: one month on an Illinois liability-only policy
Step | Amount |
|---|---|
Six-month premium (paid in full) | $246 |
Premium used (one month) | $41 |
Unearned premium refunded pro rata | $205 |
Net cost for one month | $41 |
Hypothetical; our calculation, using Auto-Owners' $41 monthly liability-only average in an Illinois real-quote analysis (rates current to September 30, 2026) × 6 = $246. Your quote will differ.
Your temporary car insurance options in Illinois
1. Weekly coverage
Illinois is one of the states where Insurify Car sells liability-only coverage in seven-day increments. The Illinois analysis put its average at $18 a week, or $102 a month. It covers liability only, so it will not pay to repair your own car.
Weekly coverage shines when you need a car for two or three weeks and do not own it, or when you want liability on a car you are about to sell. For longer stretches, compare its monthly total with a standard policy from a low-cost insurer, which you can cancel with a full pro rata refund.
2. Pay-as-you-go coverage
Hugo started in Illinois in 2020, according to a June 2026 review, and the Illinois analysis lists Hugo at an average of $115 a month. Hugo's older flex plans stopped selling new policies in March 2025, and plans now vary by state, so check current terms for your ZIP code.
3. A standard policy canceled early
Thanks to the pro rata refund law, this is often the cheapest route, and it is the only one that reliably includes collision and comprehensive. Buy from a low-cost insurer, then cancel when you are done.
4. Pay-per-mile insurance
Illinois has two major pay-per-mile choices. Allstate Milewise lists Illinois among its 22 states, and Nationwide SmartMiles does not exclude Illinois. Mile Auto launched in Illinois in 2018, but an October 2026 review lists its seven current states, and Illinois is not one of them. You pay a base rate plus a per-mile charge, which keeps costs low for a car that barely moves. Confirm current availability for your ZIP code.
5. Non-owner insurance
If you do not own a car but will borrow or rent one, a non-owner policy gives you liability coverage. A national analysis put non-owner coverage at $29 to $74 a month. It does not pay for damage to the car you drive.
6. Rental car coverage
For a short rental, one national analysis put rental car insurance at $9 to $30 a day, and a June 2026 consumer report said counter coverage often costs $30 to $60 a day. Check your own policy and credit card benefits first; most cards offer only secondary coverage and usually exclude liability.
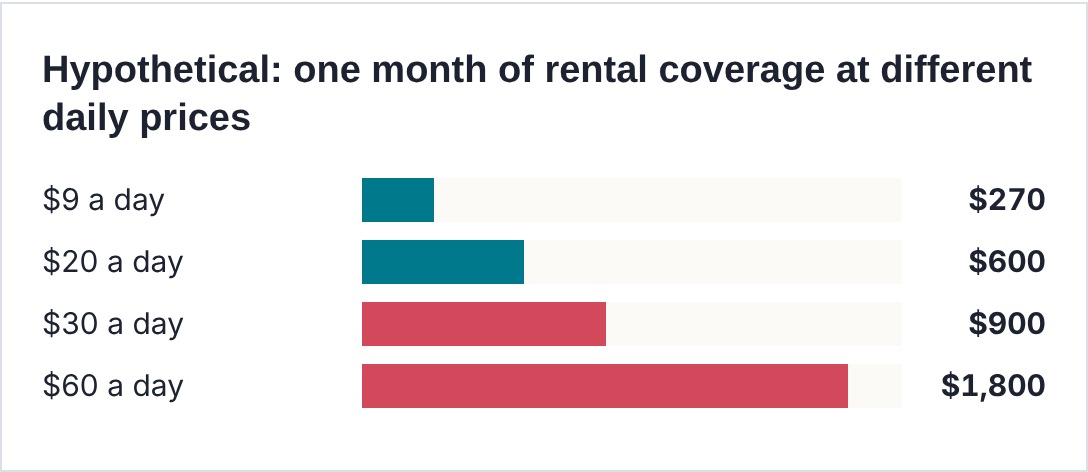
Our calculation: daily price × 30. Daily ranges from a national analysis (September 30, 2026) and a June 23, 2026, consumer report.
7. Being added to someone else's policy
For a college student home for the summer or a relative staying a few weeks, being added to the owner's policy is often the simplest answer. It may raise the owner's premium, so compare it with a weekly or non-owner policy.
8. The Illinois Automobile Insurance Plan
Drivers turned down in the regular market can apply to the Illinois Automobile Insurance Plan, the state's assigned-risk plan. Applicants must certify that they tried and failed to get insurance in Illinois within the past 60 days, and applications go through a licensed Illinois agent or broker.
How much does short-term car insurance cost in Illinois?
Illinois averages $84 a month for liability-only and $162 for full coverage in real-quote data, compared with about $99 and $187 nationally. Two 2026 analyses show the cheapest companies. Study A is a rate study updated November, 2026, using a 40-year-old driver. Study B is a real-quote analysis with rates current to September 30, 2026. Compare each only with itself.
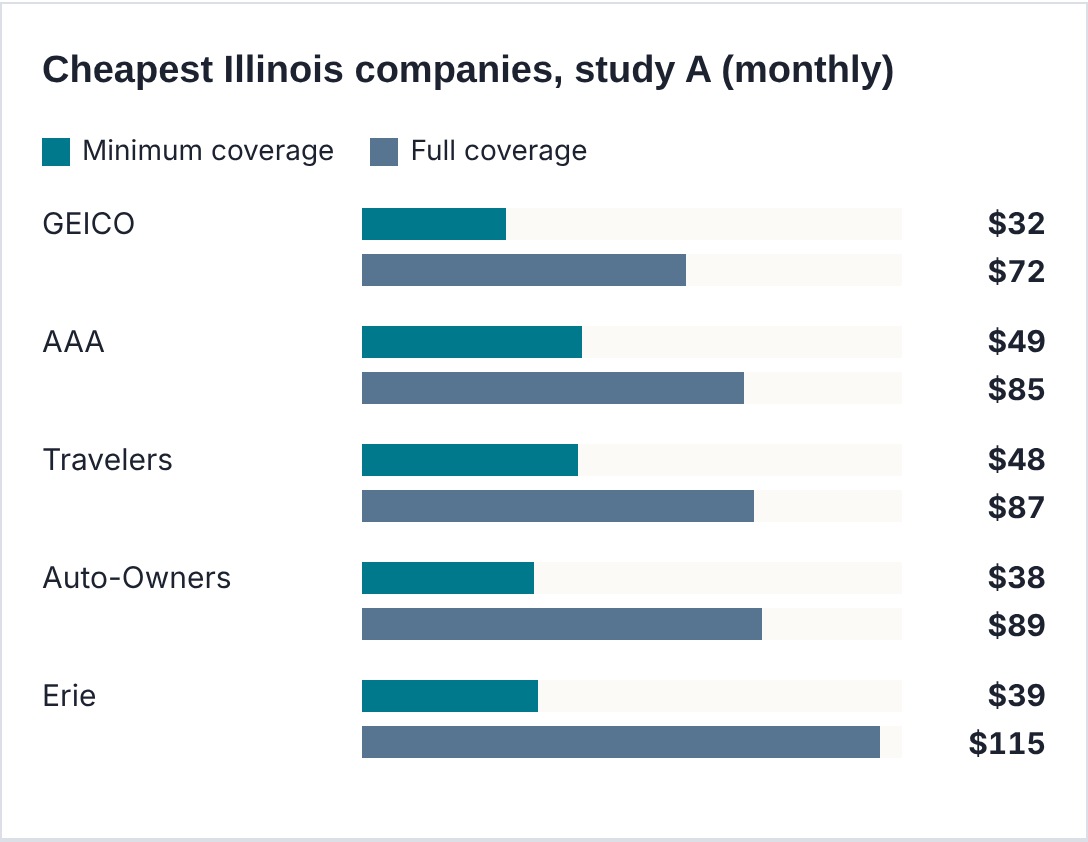
Study A: Illinois rate study updated November, 2026; 40-year-old driver, 2012 Toyota Camry; full coverage at 100/300/100 with a $1,000 deductible; minimum coverage includes uninsured motorist.
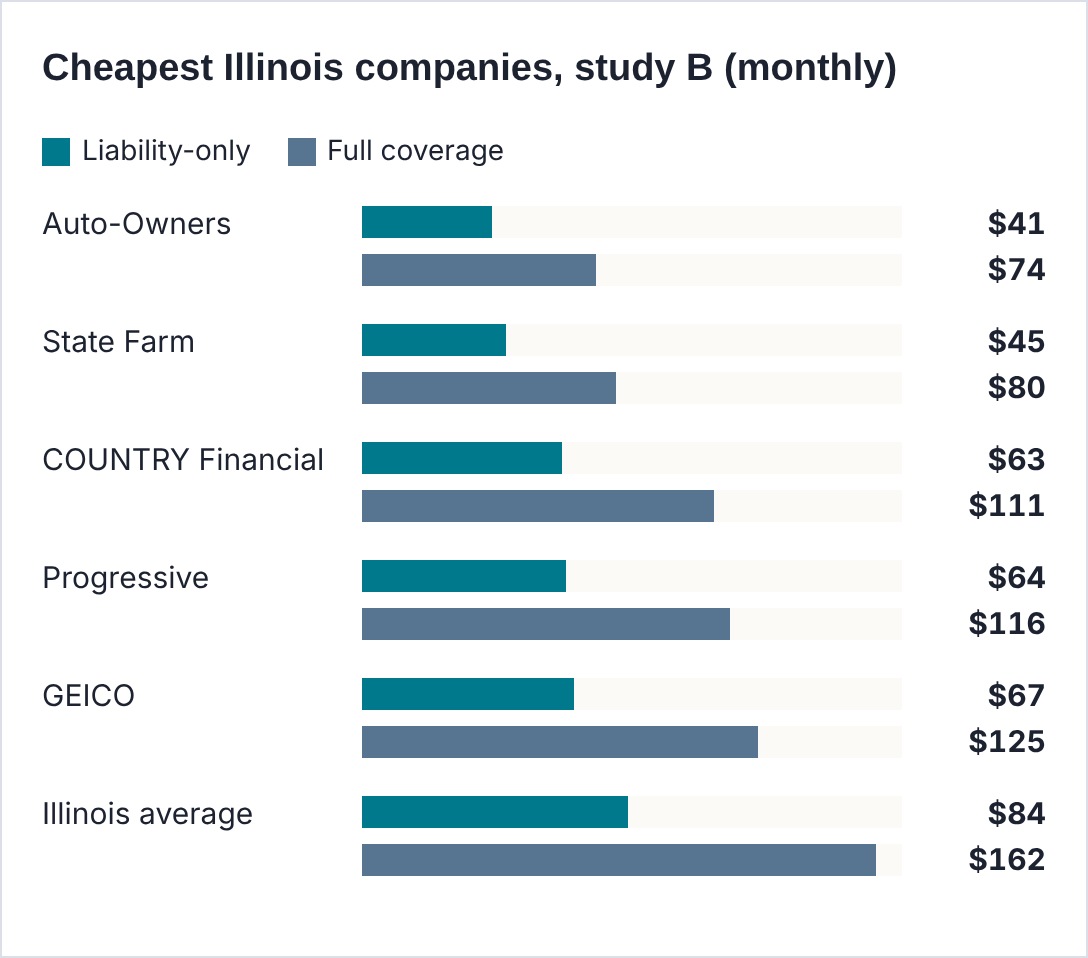
Study B: Illinois real-quote analysis updated November, 2026; rates current to September 30, 2026; driver in their 30s with a clean record.
Prices across Illinois cities
Where you live changes the price. In study A, the cheapest minimum coverage in Chicago cost $8 a month more than in Joliet and $19 more than in Champaign.
Cheapest minimum coverage in selected Illinois cities, study A
City | Cheapest company | Monthly |
|---|---|---|
Chicago | GEICO | $45 |
Cicero | Erie | $43 |
Skokie | GEICO | $40 |
Aurora | Auto-Owners | $38 |
Naperville | Auto-Owners | $38 |
Joliet | Auto-Owners | $37 |
Rockford | GEICO | $32 |
Springfield | Erie | $32 |
Peoria | GEICO | $30 |
Champaign | GEICO | $26 |
Study A: Illinois rate study updated November, 2026. Averages, not quotes.
Prices change in 2027
Illinois was one of only two states, along with Wyoming, without regulatory control over insurance rates. On August 4, 2026, Gov. JB Pritzker signed Senate Bill 714. Starting July 1, 2027, insurers must give 30 days' notice before raising auto premiums by more than 10%, and the Department of Insurance can review rates and order refunds of excessive premiums. That does not change today's prices, but it adds protection for drivers who renew.
Cheapest cars to insure in Illinois
If you are buying a car you may only keep for a while, the model matters. A vehicle-model rate study found these the cheapest to insure in Illinois for six months of full coverage:
Cheapest cars to insure in Illinois (six months, full coverage)
Vehicle | Average six-month premium |
|---|---|
Honda CR-V | $923 |
Mini Cooper Electric | $953 |
Honda HR-V | $957 |
Chevrolet Express | $957 |
Volkswagen Tiguan | $959 |
CarInsurance.com, Cheapest Cars to Insure in Illinois; full coverage at 100/300/100 with $500 deductibles. Averages, not quotes.
Temporary coverage for special situations in Illinois
College students. A student who brings a car to campus usually does best on a parent's policy. A student who borrows or rents may want weekly or non-owner coverage.
Teens. In study A, the cheapest full coverage on a family policy was $319 a month for a 16-year-old female and $324 for a male (Auto-Owners), falling to $147 at 25. In study B, Auto-Owners had the cheapest teen liability rate at $85.
Seniors. In study A, GEICO was cheapest for a 65-year-old at $78 a month for full coverage, and its course discount for drivers 50 and older can reach 5%.
Drivers with a DUI or SR-22. Study A found Travelers cheapest after a DUI at $127 a month for full coverage. Study B put DUI drivers at $124 for liability and SR-22 drivers at $149 on average.
Buying a car. Many insurers give a grace period of about 7 to 30 days to add a newly bought car, according to a June 2026 rate study, but some give only a few days. Call before you drive away.
Best temporary option by Illinois situation
Your situation | Best option | Why |
|---|---|---|
Borrowing a car for a few weeks | Weekly or non-owner coverage | Liability without a long policy |
Owning a car for a few months | Standard policy canceled early | Pro rata refund by law |
Car will barely be driven | Pay-per-mile insurance | Keeps the car insured cheaply |
Student home for summer | Be added to a parent's policy | No new policy needed |
Short rental | Rental coverage or your own policy | Covers the rental car |
Turned down by insurers | Illinois Automobile Insurance Plan | Assigned-risk coverage |
Parking a car for a few months in Illinois
Many people searching for temporary coverage actually have a car that will sit, such as a car stored for winter, a car waiting to be sold, or a car left behind during a long work assignment. Because the state checks registered vehicles, canceling outright is risky unless the car will no longer be registered. Here is how three common paths compare for a car parked for three months.
Hypothetical: a car parked for three months in Illinois
Path | What it involves | Approximate cost (our calculation) |
|---|---|---|
Keep a low-cost liability policy | Coverage stays active; no letters | $123 (3 × $41) |
Pay-per-mile policy | Base rate plus very few miles | Base rate × 3, plus miles driven |
Cancel while still registered | Risk of a suspension letter | $100 reinstatement fee, plus fines if driven |
Hypothetical; our calculation using Auto-Owners' $41 monthly liability-only average in study B. Your quote will differ.
If you are keeping a loan or lease on the car, the lender will usually require comprehensive and collision as well, so ask whether your insurer offers a reduced coverage option while the car is stored. Keep the proof of insurance handy, since the state may still ask for it.
Visitors, new residents, and sellers
Visitors. If you are visiting Illinois with your own car, your home-state policy generally travels with you, but confirm with your insurer. If you are borrowing a car, the owner's policy usually covers permitted drivers, and a non-owner or weekly policy can add your own liability coverage.
New residents. Once you register a car in Illinois, it must carry Illinois minimum coverage, including uninsured motorist coverage. Line up a policy that meets Illinois limits before you register, then cancel your old policy so you do not pay for two at once.
Sellers. If you are selling a car, keep it insured until the sale closes and the title transfers. After that, cancel and collect your pro rata refund, which Illinois requires within 30 days of your request.
How Illinois compares with other states
Ending coverage: Illinois vs. other states
State | What happens when coverage ends | Refund on early cancellation |
|---|---|---|
Illinois | Electronic checks; registration suspended until $100 fee and proof | Pro rata required by law |
Pennsylvania | Return plate within 30 days, or a three-month suspension | Depends on insurer |
New York | Surrender plates first, or suspension or daily penalties | Depends on insurer |
Florida | Suspension; $150 to $500 to reinstate | Depends on insurer |
Illinois Secretary of State; 215 ILCS 5/143.12a; PennDOT; New York DMV; Florida Statutes § 324.0221. Summarized.
How to get temporary car insurance in Illinois, step by step
- Decide what you need to cover: your own car, a borrowed car, or a rental.
- Price weekly and pay-as-you-go options if you need liability for only a few weeks.
- Get quotes from Illinois' cheapest companies, such as Auto-Owners, State Farm, GEICO, and Erie.
- Compare pay-per-mile if the car will mostly sit.
- Keep proof of insurance on your phone or in the car.
- When you are done, cancel in writing, and expect a pro rata refund within 30 days.
- Do not leave a registered car uninsured, or you risk a suspension letter.
Questions to ask an Illinois insurer
- Will my refund be pro rata, and are there any separate fees when I cancel?
- Can I pay monthly, so less premium is tied up?
- Do you offer pay-per-mile or reduced coverage for a stored car?
- Does your weekly or pay-as-you-go plan include anything beyond liability?
- Is digital proof of insurance available on my phone right away?
Pros and cons of temporary coverage in Illinois
Pros | Cons |
|---|---|
Pro rata refunds required by law | True one-week policies are rare |
Weekly and pay-as-you-go options | Weekly coverage is liability-only |
Two major pay-per-mile choices | Electronic checks catch coverage gaps |
Liability from $41 a month on average | Chicago prices run higher |
Do the math on weekly vs. monthly. In the Illinois analysis, weekly coverage averaged $18 a week, or $102 a month, while Auto-Owners averaged $41 a month for liability on a standard policy. For more than a few weeks, a cancelable policy with a pro rata refund may cost less.
Common mistakes to avoid
Dropping coverage on a registered car. The state's electronic checks can flag it.
Assuming weekly coverage protects your car. It is liability-only.
Not tracking your refund. Illinois insurers must pay it within 30 days of your cancellation request.
Driving without proof. An officer can cite you even if you are insured.
Paying six months up front without asking. Your refund is guaranteed, but monthly payments keep less of your money tied up while you wait for it.
Illinois temporary car insurance at a glance
This illustrated summary pulls together the rules and options covered above.
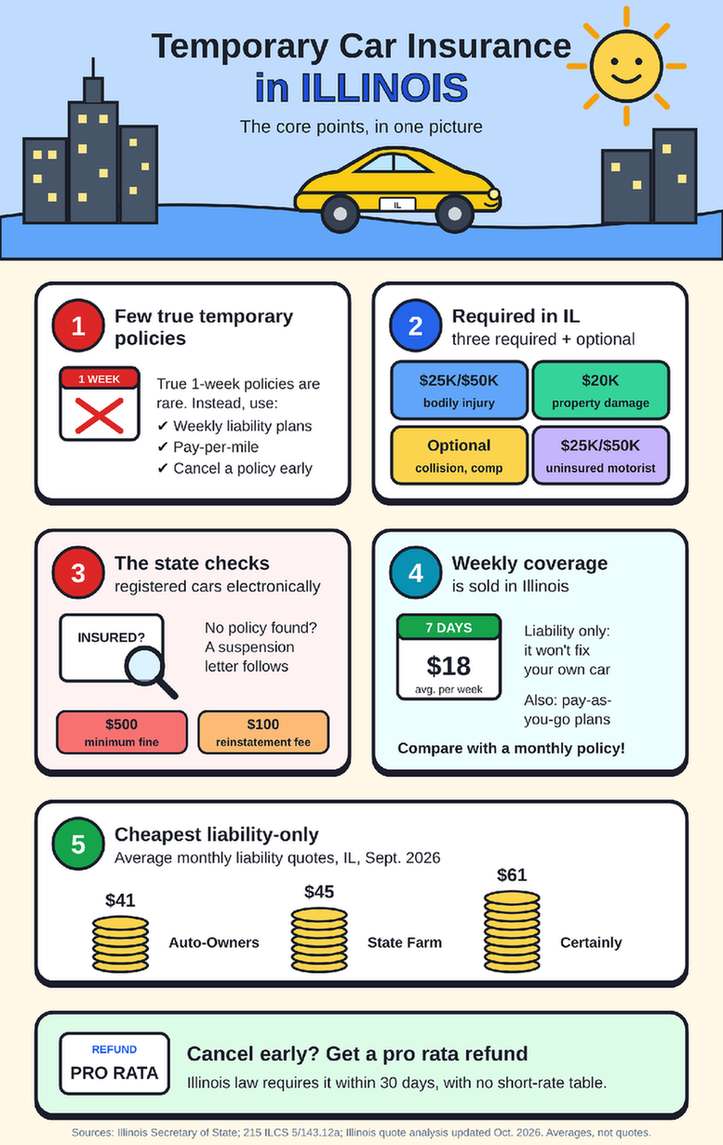
Illinois temporary car insurance at a glance. Sources: Illinois Secretary of State; 215 ILCS 5/143.12a; Illinois quote analysis updated November 2026. Averages, not quotes.
Frequently asked questions
Can you get temporary car insurance in Illinois?
Yes, in practical terms. True one-week policies are rare, but Illinois drivers can buy weekly liability coverage through Insurify Car, use pay-as-you-go or pay-per-mile coverage, buy non-owner or rental coverage, or cancel a standard policy early and receive a pro rata refund.
What insurance is required in Illinois?
Illinois requires $25,000 per person and $50,000 per crash in bodily injury liability, $20,000 in property damage liability, and uninsured motorist bodily injury coverage of $25,000 per person and $50,000 per crash. Collision and comprehensive are optional by law, though lenders usually require them.
Will I get a refund if I cancel early in Illinois?
Yes. Under 215 ILCS 5/143.12a, an insurer must refund unearned auto premium pro rata to the date of cancellation, whether you or the insurer cancels, and it cannot use a short-rate table. The refund is due within 30 days of your cancellation request.
How does Illinois know if my car is uninsured?
The Illinois Insurance Verification System checks registered vehicles against insurer data. If two checks 30 days apart find no policy, the Secretary of State sends a suspension letter. You then have 30 days to prove coverage, or the registration is suspended until you pay $100 and show proof.
What is the fine for driving uninsured in Illinois?
The minimum fine is $500, according to the Illinois Secretary of State. Driving while your registration is suspended for no insurance carries a minimum $1,000 fine. Repeat offenders face a four-month suspension, and some violations require SR-22 proof of insurance for three years.
How much is weekly car insurance in Illinois?
An Illinois real-quote analysis updated November, 2026, put Insurify Car's weekly liability coverage at an average of $18 a week, or about $102 a month. Weekly coverage is liability-only, so it does not cover damage to your own car.
Is pay-per-mile insurance available in Illinois?
Yes. Allstate Milewise lists Illinois among its 22 states, and Nationwide SmartMiles does not exclude Illinois. Mile Auto, which launched in Illinois in 2018, no longer lists the state. These plans charge a monthly base rate plus a per-mile fee. Confirm availability and pricing for your ZIP code before you buy.
What is the cheapest car insurance in Illinois?
In real-quote data current to September 30, 2026, Auto-Owners was cheapest at $41 a month for liability-only and $74 for full coverage. In a separate rate study, GEICO led full coverage at $72, and it also led minimum coverage at $32.
The final word on temporary car insurance in Illinois
Illinois is one of the friendlier states for short-term drivers. For a few weeks of liability, weekly or pay-as-you-go coverage is a real option. For anything longer, or when you need collision and comprehensive, a standard policy from a low-cost insurer canceled early is usually the best value, because state law guarantees a pro rata refund. Just remember that the state checks registered vehicles electronically, so keep a registered car insured.
NEXT STEPWrite down the dates you need coverage and the car you will drive. Price a weekly option, a pay-per-mile policy, and two low-cost standard policies, then choose the one with the lowest total cost for your dates.
Prices, availability, cancellation terms, and state rules can change. The figures in this article are averages, published rules, and hypothetical calculations, not quotes. This article is for information only and is not legal or financial advice. The publisher is not an insurance company or a licensed insurance agency.
The bottom line on temporary car insurance in Illinois: weekly, pay-as-you-go, and pay-per-mile coverage fill short gaps, and the state's pro rata refund law makes canceling a standard policy early a safe, low-cost way to cover a few months.
Sources
- Illinois Secretary of State, Mandatory Insurance brochure (VSD 361.17, September 2023).
- 215 ILCS 5/143.12a, refund of unearned premium (accessed October 2026).
- StateScoop, Illinois insurance verification system (September 2021) and Illinois Lawyer Now, driving without insurance in Illinois (February 2026).
- Illinois Automobile Insurance Plan (AIPSO) (accessed October 2026).
- WTTW, Pritzker signs bills allowing state to review insurance rate hikes (August 4, 2026).
- Insurify, Temporary Car Insurance in Illinois (updated October 17, 2026) and Illinois Car Insurance (updated October 18, 2026).
- MoneyGeek, Cheapest Car Insurance in Illinois (updated October 15, 2026).
- Insurance Information Institute, Uninsured Motorists, citing the Insurance Research Council.
- Insurify, Allstate Milewise review, Nationwide, SmartMiles, and Insurance Journal, Mile Auto launches in Oregon and Illinois (November 8, 2018), and Insurify, Mile Auto review (updated October 18, 2026).
- OCHO, Hugo Insurance Reviews (June 2026).
- CarInsurance.com, Cheapest Cars to Insure in Illinois and New Car Grace Period (updated June 26, 2026).
- Insurify, One-Week Car Insurance (updated September 30, 2026) and First Alert 4, Understanding Rental Car Insurance (June 23, 2026).
- PennDOT, Insurance Overview, New York DMV, Auto Liability Insurance, and Florida Statutes § 324.0221.